
We're Not Very Worried About SaltX Technology Holding's (STO:SALT B) Cash Burn Rate
We can readily understand why investors are attracted to unprofitable companies. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. Nonetheless, only a fool would ignore the risk that a loss making company burns through its cash too quickly.
Given this risk, we thought we'd take a look at whether SaltX Technology Holding (STO:SALT B) shareholders should be worried about its cash burn. For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). Let's start with an examination of the business' cash, relative to its cash burn.
How Long Is SaltX Technology Holding's Cash Runway?
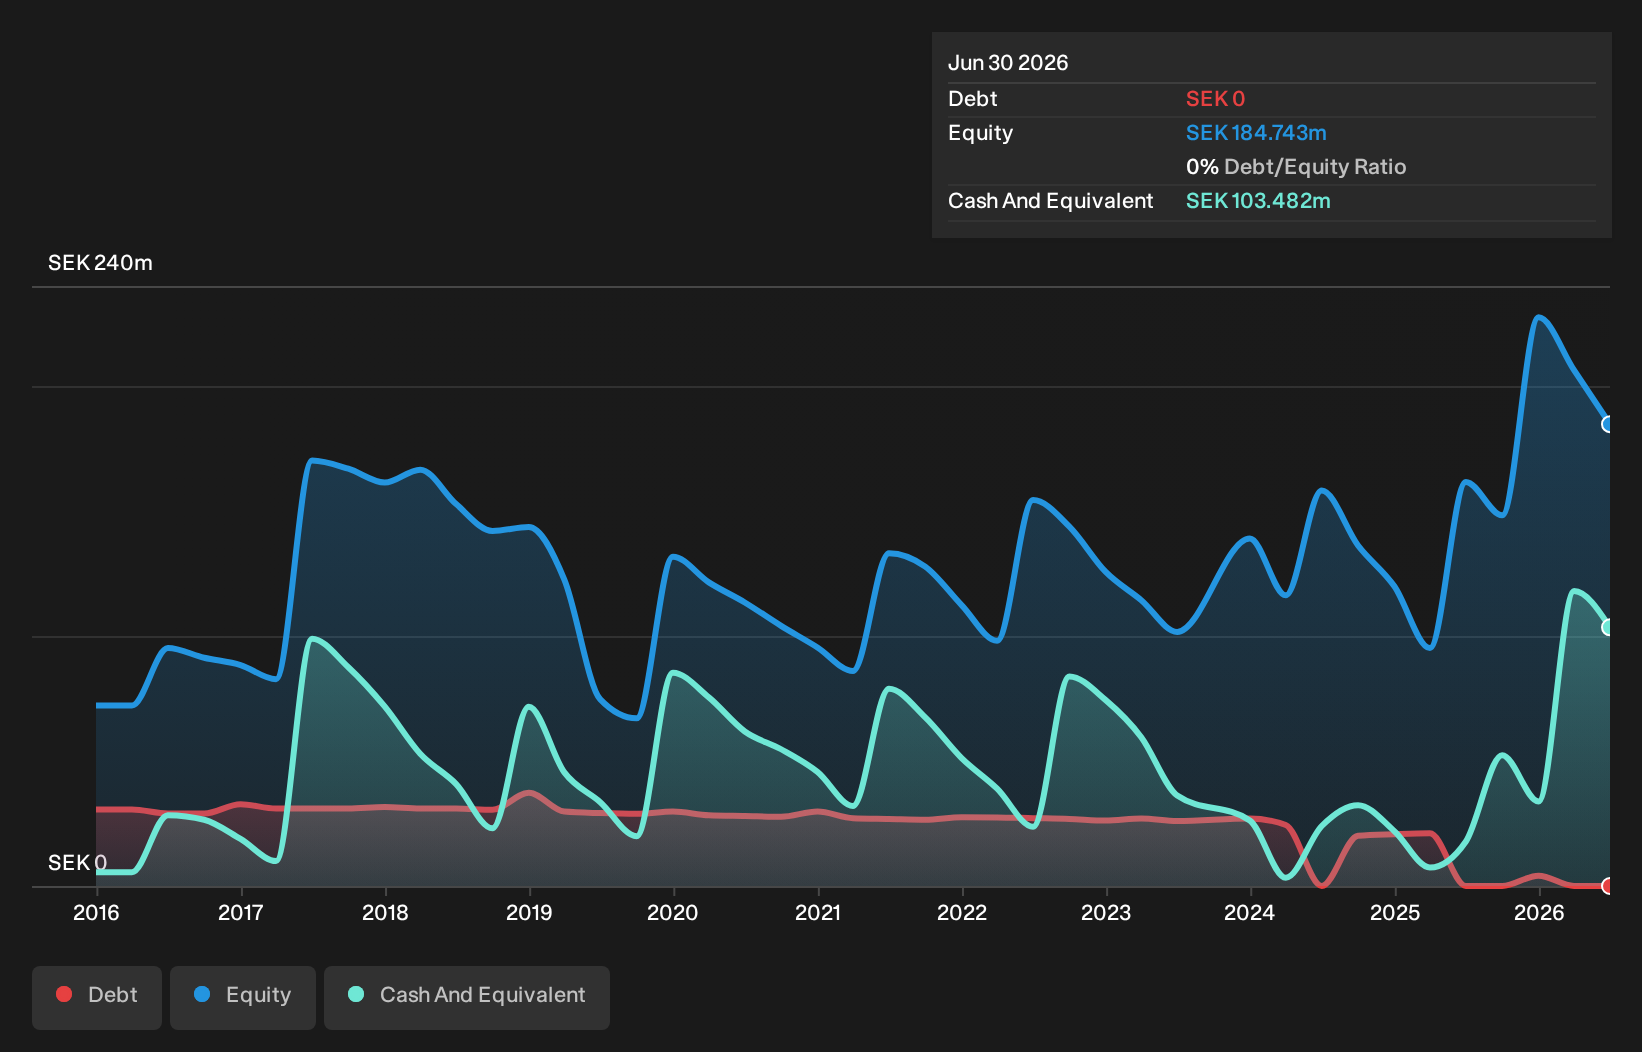
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. As at June 2026, SaltX Technology Holding had cash of kr103m and no debt. In the last year, its cash burn was kr72m. Therefore, from June 2026 it had roughly 17 months of cash runway. Importantly, the one analyst we see covering the stock thinks that SaltX Technology Holding will reach cashflow breakeven in 2 years. That means unless the company reduces its cash burn quickly, it may well look to raise more cash. The image below shows how its cash balance has been changing over the last few years.
Check out our latest analysis for SaltX Technology Holding
How Well Is SaltX Technology Holding Growing?
Notably, SaltX Technology Holding actually ramped up its cash burn very hard and fast in the last year, by 109%, signifying heavy investment in the business. As if that's not bad enough, the operating revenue also dropped by 8.9%, making us very wary indeed. Taken together, we think these growth metrics are a little worrying. While the past is always worth studying, it is the future that matters most of all. So you might want to take a peek at how much the company is expected to grow in the next few years.
How Easily Can SaltX Technology Holding Raise Cash?
Since SaltX Technology Holding can't yet boast improving growth metrics, the market will likely be considering how it can raise more cash if need be. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
Since it has a market capitalisation of kr911m, SaltX Technology Holding's kr72m in cash burn equates to about 7.9% of its market value. That's a low proportion, so we figure the company would be able to raise more cash to fund growth, with a little dilution, or even to simply borrow some money.
How Risky Is SaltX Technology Holding's Cash Burn Situation?
On this analysis of SaltX Technology Holding's cash burn, we think its cash burn relative to its market cap was reassuring, while its increasing cash burn has us a bit worried. One real positive is that at least one analyst is forecasting that the company will reach breakeven. While we're the kind of investors who are always a bit concerned about the risks involved with cash burning companies, the metrics we have discussed in this article leave us relatively comfortable about SaltX Technology Holding's situation. Taking a deeper dive, we've spotted 5 warning signs for SaltX Technology Holding you should be aware of, and 1 of them is concerning.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.