
Is Snap (SNAP) A Bargain Following Stronger Profitability And Snap Map Monetisation?
Snap (SNAP) is back in focus after Blue Duck Capital issued an open letter pressing the board to ring fence its Specs augmented reality glasses unit with outside funding, without diluting current investors.
For context, Snap’s recent 5.6% 1 day share price return to about US$6.44 caps a 42.2% 90 day share price return and a 10.5% 30 day move. Yet the stock is still down 20.8% year to date on a share price basis and the 5 year total shareholder return has declined 91.4%. This suggests that current momentum is building off a much weaker long term experience as investors weigh improved profitability metrics, fresh Snap Map monetisation data, and now the Blue Duck campaign on Specs.
Scan how other fast movers compare to Snap’s setup by running your eye over 33 high quality undervalued stocks while this activism story is still fresh.
Snap now appears more like a functioning business with growing profitability than the boom bust story implied by a 91.4% five year hit. After this latest rebound, is that improving engine still priced as a bargain or already fully recognised?
Most Popular Narrative: 12% Undervalued
Snap’s most followed narrative pegs fair value around $7.33, which sits above the recent $6.44 close and frames the current rebound as a partial catch up to that estimate rather than a full rerating.
Accelerating innovation in augmented reality (AR), including the upcoming public launch of Specs AR glasses in 2026 and continuous expansion of the AR developer ecosystem, positions Snap to benefit from both increased user engagement and the creation of premium advertising and subscription revenue streams, which can boost top-line revenue and improve gross margins over time.
See why 71 investors see Snap as 12% undervalued.
Result: Fair Value of $7.33 (UNDERVALUED)
Still, the bullish Snap narrative hits real pressure points if competition keeps squeezing ad budgets or if engagement softness persists, which could limit the upside from Specs and subscriptions.
Find out about the key risks to this Snap narrative.
Another View: Snap Through a Revenue Multiple Lens
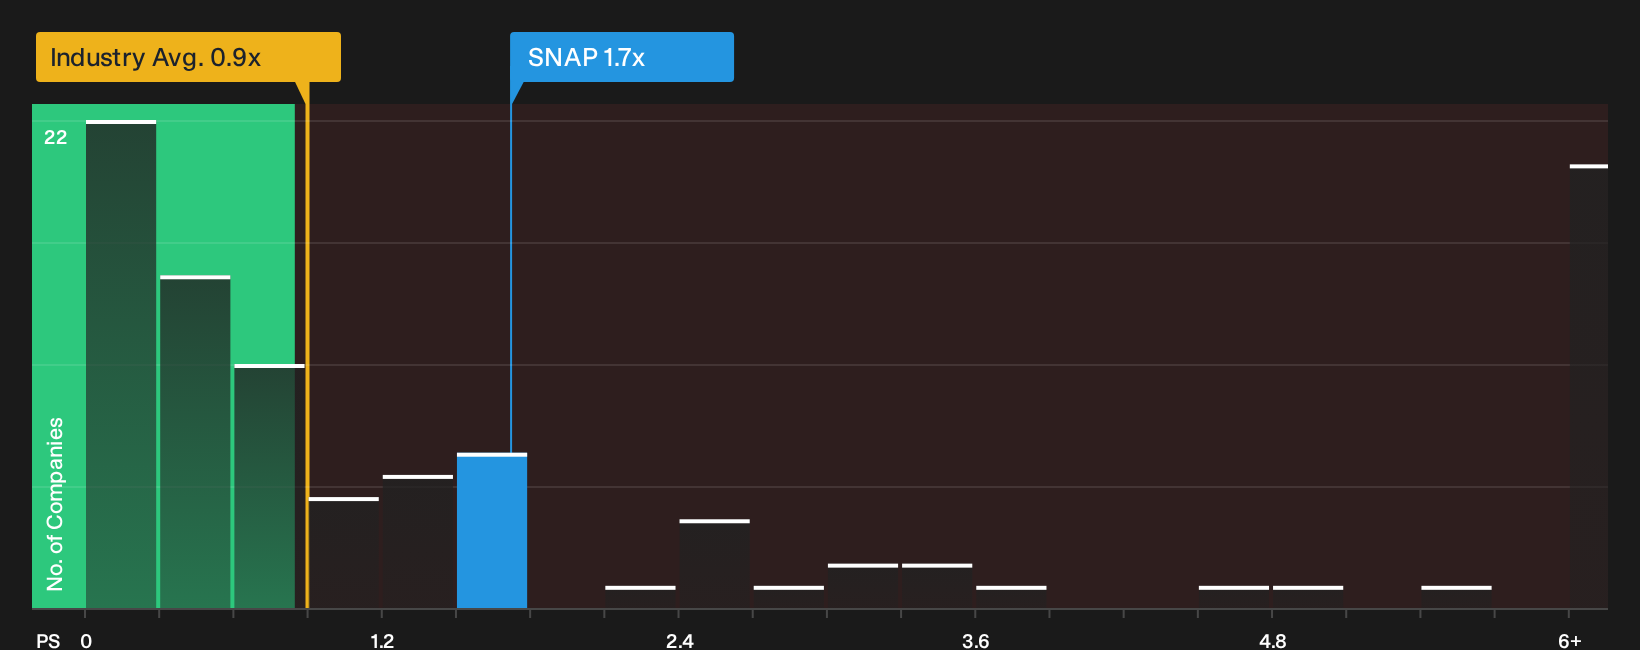
The first take leans on fair value models that point to upside for Snap. A simple P/S check tells a more cautious story. Snap trades at 1.7x sales against a 0.9x industry level, which prices the stock richer than many US Interactive Media and Services peers.
That premium looks different when set against a fair ratio of 2.2x sales, which suggests the market could move higher if sentiment improves, yet also flags real downside risk if sector valuations compress. With that kind of spread on both sides, which signal do you think deserves more weight right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Snap is clearly split, which is exactly why you should move fast, review the numbers yourself, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Snap?
If Snap has your attention right now, broaden your watchlist with a few focused stock ideas that line up with how you like to build a portfolio.
- Target resilient cash generators by scanning a 8 dividend fortresses that can help you keep income flowing even when sentiment turns choppy.
- Hunt for future standouts before they hit the headlines by filtering through 20 high quality undiscovered gems with strong fundamentals and room to grow into their story.
- Dial down portfolio stress and concentrate on durability by zeroing in on 32 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com