
Establishment Labs Stock Has The Bull Case Changed After FDA Implant Size Approval?
- Establishment Labs Holdings reported that the FDA has approved an expanded range of Motiva SmoothSilk Round and Ergonomix breast implant sizes for U.S. use, adding 28 new options across Mini, Demi and Full profiles, including volumes as small as 105 cc, with commercial availability planned before the end of 2026.
- The wider size matrix gives surgeons more precise combinations of base, projection and volume. This can support procedure customization, address a broader mix of patient anatomies and likely influence how frequently Motiva products are selected within U.S. aesthetic and reconstructive practices.
- We will now examine how Establishment Labs Holdings' investment narrative could be reshaped by this broader FDA cleared Motiva size portfolio.
Scan how Establishment Labs Holdings compares with other medical and aesthetic players by reviewing a curated set of list of solid balance sheet and fundamentals (25 results).
Establishment Labs Holdings Investment Narrative Recap
To own Establishment Labs Holdings, you need to believe its Motiva platform keeps gaining surgeon and patient traction across both aesthetic and reconstructive procedures, while the business moves from heavy investment to more disciplined cash use. The expanded Motiva size range can support that thesis if it deepens usage in existing U.S. accounts, although competitive pushback remains a live issue.
The near term swing factor still sits in execution, particularly U.S. commercial productivity and international ramp in places like China. The biggest risk remains high spending and working capital demands outpacing revenue, especially with refinancing needs ahead. The new approvals help the product story, but they do not remove funding or margin pressure.
The fresh FDA clearance for 28 additional Motiva SmoothSilk Round and Ergonomix sizes is directly tied to one of the clearest catalysts: expansion of the addressable patient base through new product sizes and indications. A broader catalog lets surgeons match implants to more body types, which can support higher utilization where accounts are already opened.
That same announcement also interacts with the key risk around product concentration. Establishment Labs Holdings still leans heavily on Motiva implants, so deeper reliance on this line increases exposure if surgeon preferences shift or a competitor moves quickly on price or features. Your focus probably needs to stay on how well management converts this richer portfolio into disciplined growth without overstretching the balance sheet.
Establishment Labs Holdings' current consensus framework points to revenues of US$461.7 million and earnings of US$36.1 million by 2029. This is based on analysts assuming 23.4% yearly revenue growth and earnings moving from a loss of US$38.9 million today to a profit of US$36.1 million, which is an earnings swing of about US$75 million.
Uncover why Establishment Labs Holdings' fair value indicates a 67% potential upside to its current price, a gap that may not last much longer.
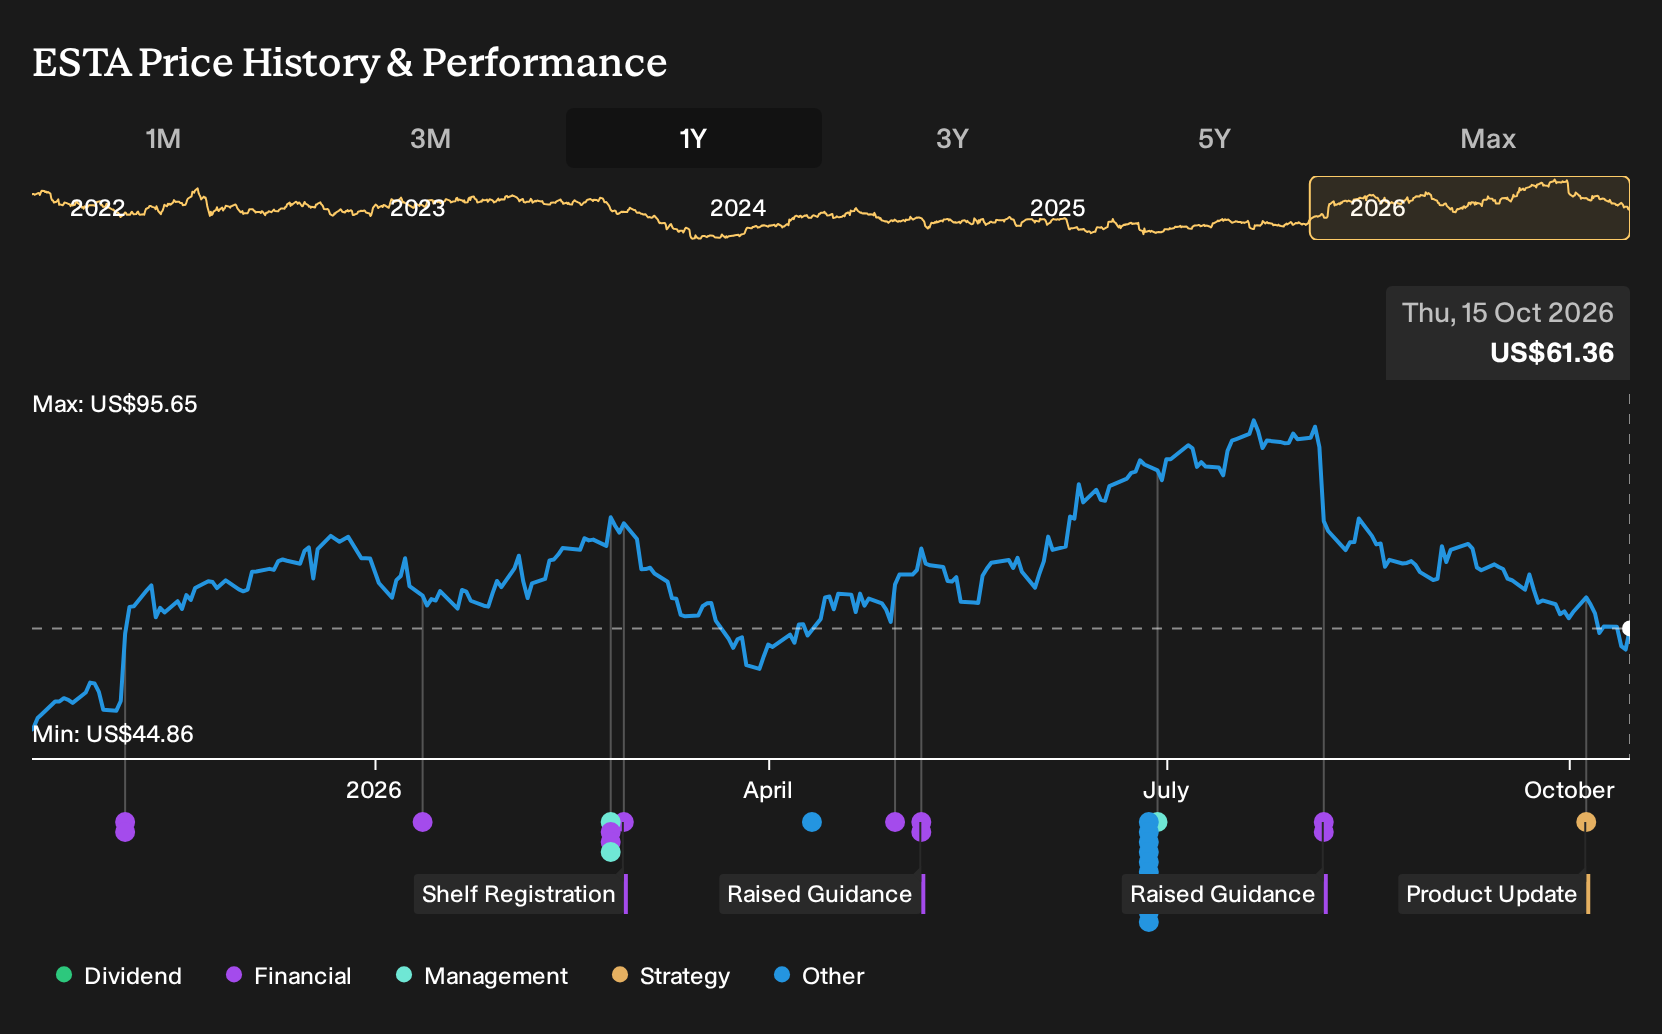
Exploring Other Perspectives
You can also look at a very different angle. The most optimistic analysts focus on Establishment Labs Holdings turning much more profitable, with revenue projections of US$499.8 million and earnings of US$95.2 million by 2029 before this FDA news. Those forecasts already assumed strong demand, so this latest approval could eventually push expectations even further apart.
Explore 2 other Establishment Labs Holdings fair value estimates, including one that suggests as much as 67% upside from the current price!
The Verdict Is Yours
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Establishment Labs Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Establishment Labs Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Establishment Labs Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Establishment Labs Holdings?
If the Establishment Labs Holdings story has sharpened your thinking, use that momentum to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors who want companies that already show strong financial footing, run your filters against a list of solid balance sheet and fundamentals (25 results) to see which businesses line up with your quality bias.
- If you are hunting for quality that the market might be overlooking, check out a curated set of 20 high quality undiscovered gems that pair fundamentals with quieter investor attention.
- For readers who put capital preservation high on the list, focus your search on 32 resilient stocks with low risk scores that score well on stability and resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com