
How Investors May Respond To AS ONE Stock Monthly Sales Update
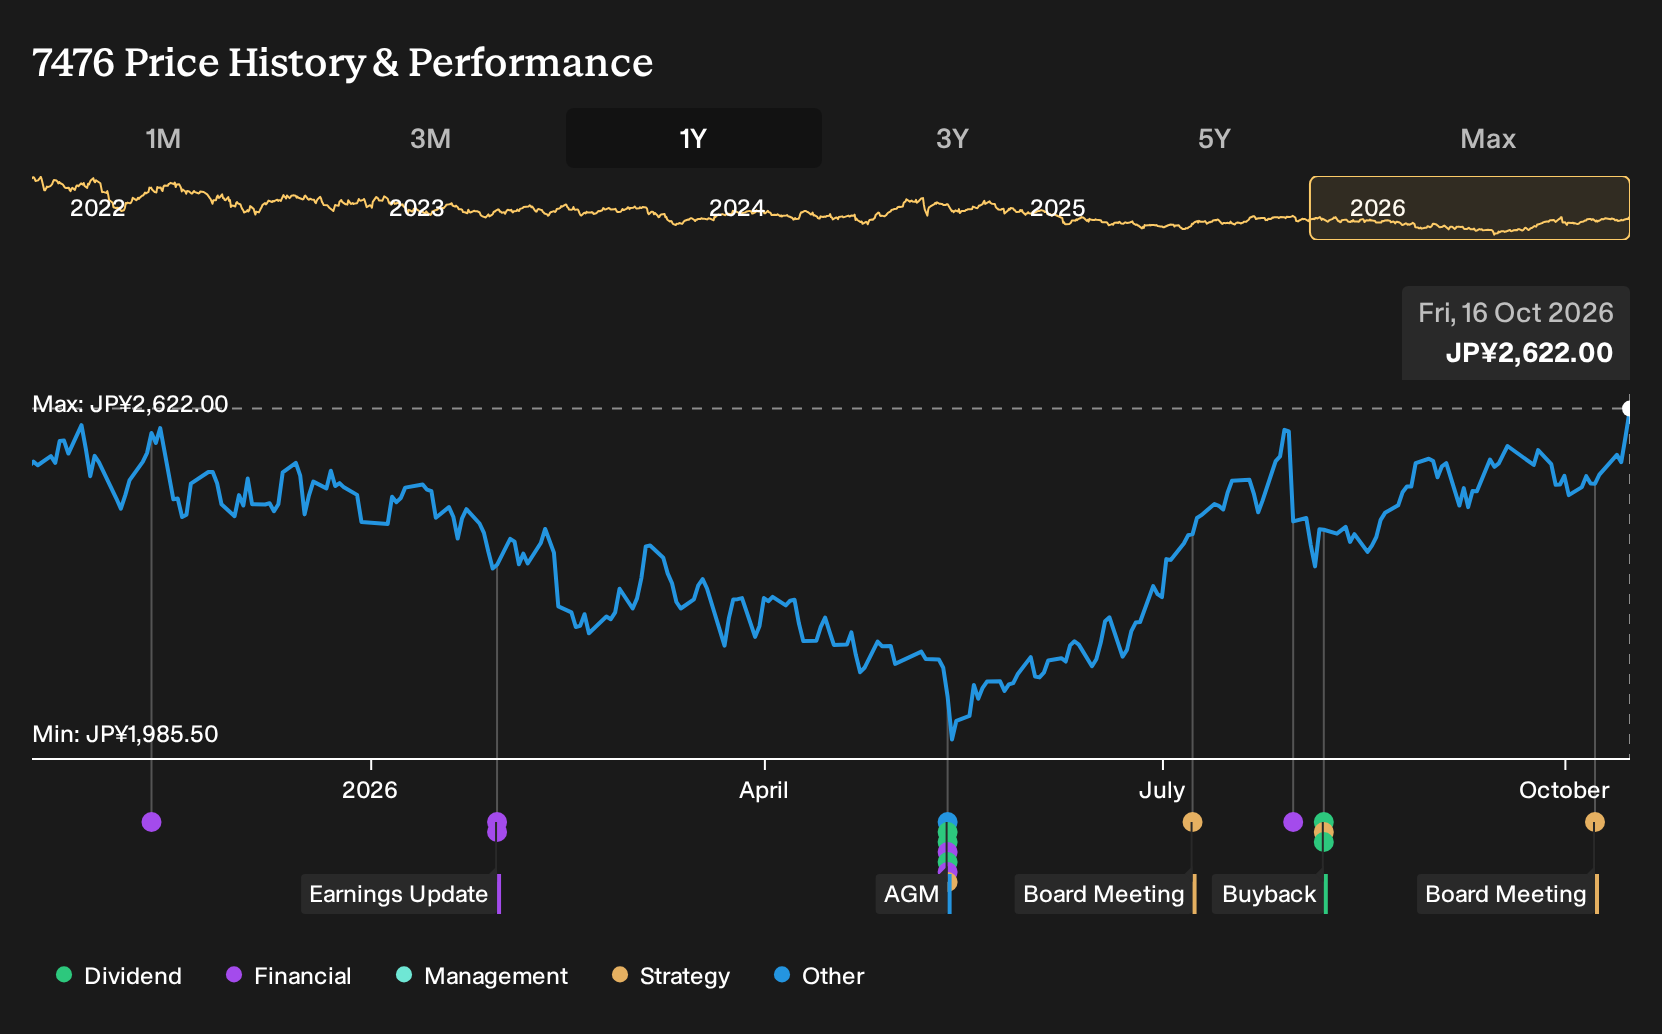
- AS ONE reported preliminary August 2026 net sales of JPY 8,777 million, compared with JPY 8,423 million in the same month a year earlier, and held a board meeting on 8 October 2026 to consider cancelling treasury shares under article 178 of the Companies Act.
- The mix of higher reported monthly sales and a potential reduction in treasury shares gives investors fresh information on both current trading momentum and how AS ONE might manage its capital structure.
- Next, the focus shifts to how AS ONE's treasury share cancellation plans might reshape the investment narrative and long term return drivers.
Compare AS ONE's latest trading update with a hand picked shortlist of companies showing steady momentum and disciplined balance sheets using the list of solid balance sheet and fundamentals (21 results).
What Is AS ONE's Investment Narrative?
To own AS ONE, you need to believe in a fairly straightforward story. This is a distributor style business in research, industrial and medical equipment, where the real edge comes from breadth of catalogue, reliable logistics and tight cost control rather than blockbuster products. Recent August 2026 net sales of ¥8,777 million, alongside steady earnings and revenue growth in recent years, point to a model that still depends on consistent order flow and disciplined execution more than aggressive expansion.
The near term swing factors are less about one month of trading and more about pricing power, working capital discipline and how management allocates cash. A potential cancellation of treasury shares hints at a more shareholder focused capital structure, while forecasts of earnings and revenue growth in the mid single digits keep expectations grounded. Dividend coverage by free cash flow remains a pressure point and sits alongside a P/E above both peer and industry averages as you weigh risk versus reward.
Even so, there is a less comfortable angle to the AS ONE story that starts with how those cash flows are...
There's only one way to know the right time to buy, sell or hold AS ONE. Head to Simply Wall St's company report for the latest analysis of AS ONE's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AS ONE research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AS ONE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AS ONE's overall financial health at a glance.
Looking For More Investment Ideas Beyond AS ONE?
Once you have a view on AS ONE, it can help to widen the lens and compare it with other companies that share similar qualities around balance sheet strength, income potential or valuation support.
- For investors who want income to do more of the heavy lifting, check out 31 dividend fortresses that concentrate on higher-yielding payers.
- If capital preservation sits near the top of your priority list, filter for steadier profiles through 21 resilient stocks with low risk scores and see which companies match your tolerance for downside risk.
- When you are hunting for quality that is not yet heavily followed, use 73 high quality undiscovered gems to surface lesser-known businesses with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com