
Earth Brands Investment Might Change The Case For Investing In Cimpress Stock (CMPR)
- Cimpress led a US$10 million funding round for Earth Brands, backing expansion of American made custom packaging, quicker turnaround times and sharper pricing for food service customers across the United States.
- The move connects Cimpress directly to a growing custom packaging supplier that can channel more volume onto its shared manufacturing and technology platforms.
- This article examines how Cimpress's investment narrative could evolve as Earth Brands expands its American made custom packaging capabilities.
Scan other packaging and manufacturing plays that are moving on similar themes of scale, efficiency and U.S. production strength with a curated list of list of solid balance sheet and fundamentals (25 results)
Cimpress Investment Narrative Recap
For Cimpress, the core belief is that higher value categories like packaging, apparel and signage can offset pressure in legacy print. The Earth Brands deal fits that story, but on its own it probably does not change the near term picture. The key near term catalyst is still whether cost savings from shared manufacturing and AI driven efficiency start to show up cleanly.
The biggest current risk remains execution on those efficiency projects and capital spending plans. Management expects US$70 million to US$80 million of cost savings from 2026 to 2028. If the production network and software investments underdeliver, free cash flow and net margins could sit below what many shareholders are hoping for.
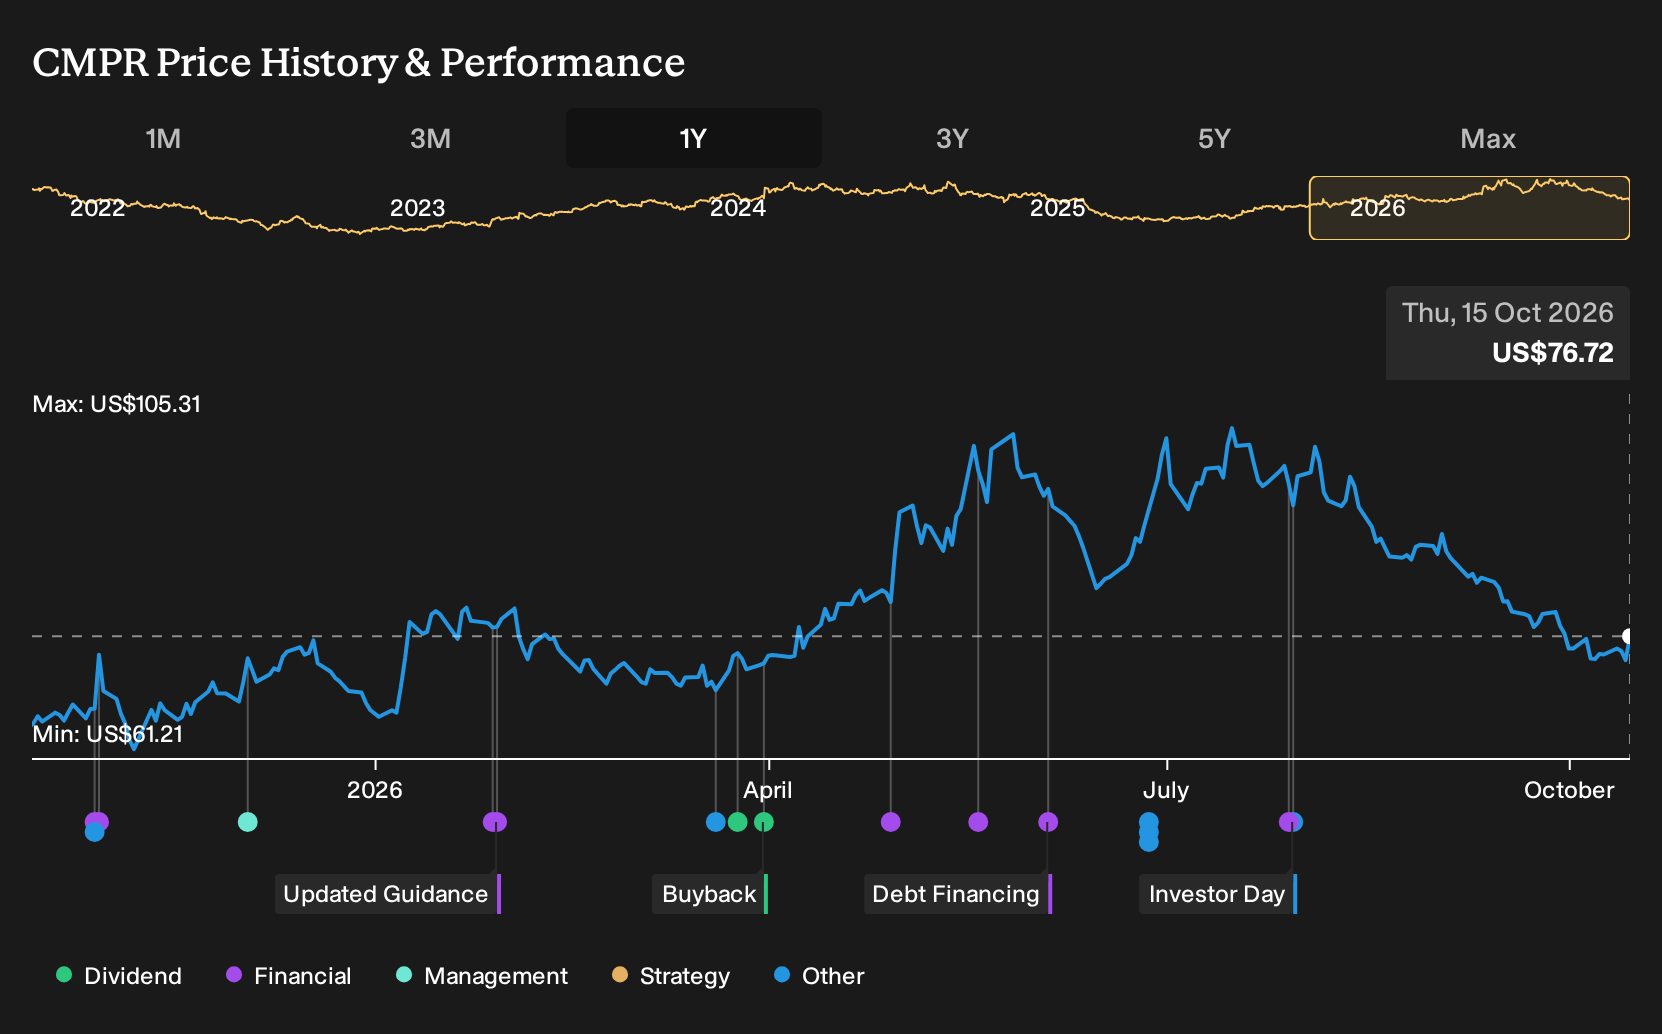
Among recent developments, the refinancing of Cimpress’s US$1.1b term loan and the extension of its revolver matter most next to the Earth Brands funding. That refinancing pushed out major maturities to 2033 and gives the group time to work through its production and technology build out while it leans into higher value product lines.
Debt still cuts both ways. Leverage around 2.9% to 3.0% of EBITDA and interest payments that are not well covered by earnings leave less room if profitability softens. For you as an investor, the real test is whether management can pair this balance sheet flexibility with consistent progress on EBITDA, cost savings and mix shift into categories such as packaging where partnerships like Earth Brands can add volume.
Cimpress Forecasts Behind The Earth Brands Bet
Cimpress' tie up with Earth Brands sits against a backdrop where analysts already model steady expansion in the wider group. Consensus assumes Cimpress can keep lifting revenue at 6.2% a year for the next three years, while profit margins move from 2.6% today to 5.5% by around 2029. That backdrop matters for Earth Brands because any extra custom packaging volume that runs through Cimpress production hubs feeds into these same revenue and earnings targets rather than a separate story.
Cimpress' narrative projects US$4.5b revenue and US$246.3 million earnings by 2029. This is built on 6.2% yearly revenue growth and an earnings increase of about US$150 million from US$95.9 million today.
Uncover why Cimpress' fair value indicates a 49% potential upside to its current price before that markdown gap closes.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$114.50 to US$256.44 per share, which is a wide gap for the same Cimpress story. With only a couple of community viewpoints so far, you are seeing early takes. Consider Earth Brands, execution risks and cost saving targets before settling on your own view.
Explore another Cimpress fair value estimate, including one that suggests it could be worth just $114.50!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cimpress research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cimpress. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cimpress' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cimpress?
Once you have formed a view on Cimpress, it can help to compare it with other businesses that share similar strengths in balance sheet quality, income potential or upside optionality.
- If you want ideas with smaller share prices but financials that still look robust, scan the 13 elite penny stocks with strong financials that have already cleared strict balance sheet and earnings filters.
- If your focus is on quality businesses trading below what their fundamentals might justify, work through a curated set of 33 high quality undervalued stocks that combine solid cash generation with measured risk.
- If portfolio income is a priority, shortlist potential payers using a hand picked group of 8 dividend fortresses that pair higher yields with more resilient financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com