
Should Leadership Changes Require Action From Beiersdorf (XTRA:BEI) Investors?
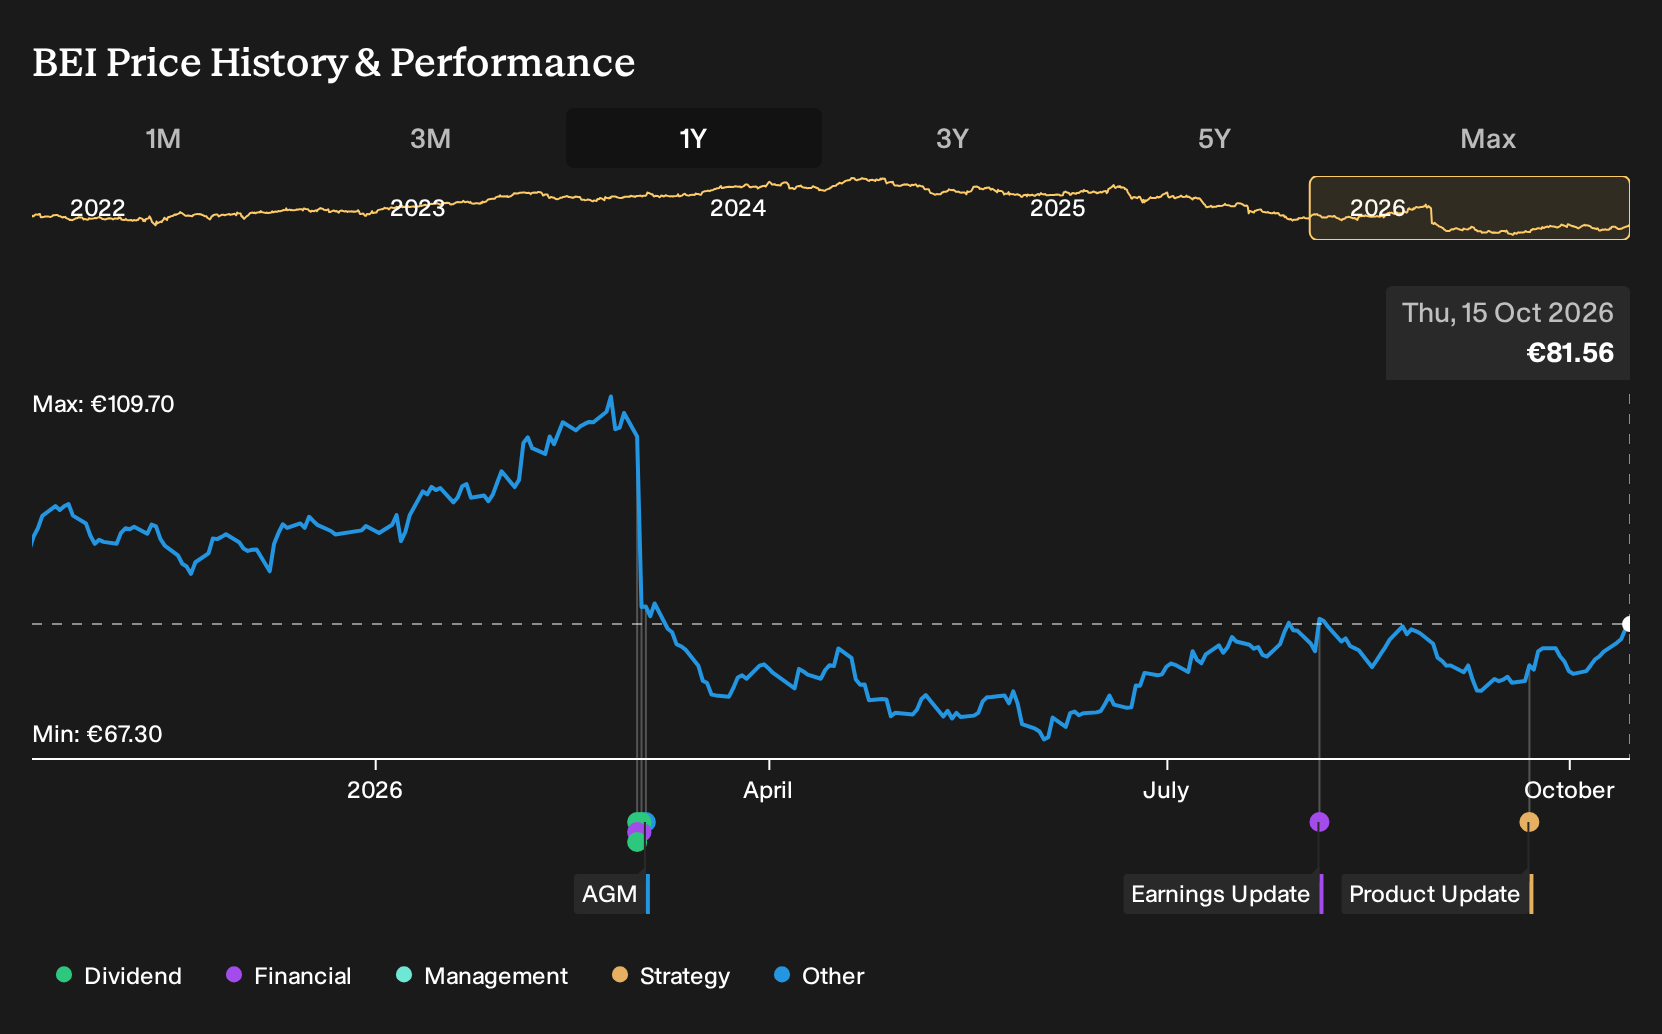
- Beiersdorf has reshaped its Southern Europe structure by promoting Sara Lupi to lead luxury brands La Prairie and Chantecaille and appointing Valerie Kruck as HR director, alongside reporting a 4.5% sales decline in the first half of 2026.
- The business also lifted recycled aluminium content in the classic Nivea Creme tin from 80% to 95%, linking the brand’s heritage with lower carbon packaging and circular economy goals.
- This article now explores how Beiersdorf's leadership reshuffle in Southern Europe could influence the existing investment narrative around its brands.
Scan how Beiersdorf's restructuring and sustainability push compares with other consumer stocks under pressure on our curated 197 high quality undervalued stocks list.
Beiersdorf Investment Narrative Recap
To own Beiersdorf, you have to trust that the pressure in mass skincare, especially Nivea, can be managed while the Derma and premium portfolios keep doing more of the heavy lifting. The short term swing factor is still whether the extra €100m in 2026 consumer marketing eventually stabilises Nivea volumes and mix after the recent 4.5% sales decline.
The biggest risk right now is that competition from local brands and private labels forces more discounting just as Consumer EBIT margin is guided to step down by about 250 bps. The Southern Europe leadership reshuffle looks operational rather than transformational, so on its own it does not materially change that near term risk reward balance.
The most relevant announcement for this story is the organisational revamp in Southern Europe, with Sara Lupi taking charge of La Prairie and Chantecaille and Valerie Kruck stepping in as HR director. For you, the key question is whether stronger regional execution can support the planned La Prairie Swiss Pristine launches and selective luxury retail roll out.
If those high ticket offerings gain traction with younger consumers, they could help offset softer Nivea trends and support mix, particularly as Derma brands like Eucerin and Aquaphor already contribute more to gross margin quality. The risk is that any misstep in rollout, staffing or HR led transformation in this region delays that premium uplift just when Beiersdorf is absorbing higher marketing and digital investment across the group.
Analysts currently frame Beiersdorf's story around projected revenues of €10.3b and earnings of €940.7m by 2029, which corresponds to 2.5% yearly revenue growth and an earnings increase of about €2.7m from €938.0m today.
Uncover why Beiersdorf's fair value is essentially in line with its current price.
Exploring Other Perspectives
One alternate view focuses less on Nivea and more on the risk that premium and Derma momentum cools. The most cautious analysts were pencilling in only 1.7% annual revenue growth and earnings of €876.0m by 2029, versus today’s €938.0m. Those forecasts came before this Beiersdorf leadership and packaging news, so opinions may shift.
Explore 4 other Beiersdorf fair value estimates, including one that suggests it could be worth just €80.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Beiersdorf research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Beiersdorf. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Beiersdorf's overall financial health at a glance.
Looking For More Ideas Beyond Beiersdorf?
If the Beiersdorf story has you thinking about portfolio balance, it can help to widen the lens and compare it with other businesses that share similar characteristics or offer a different mix of risk and potential reward.
The Simply Wall St Screener lets you quickly filter the market using fundamentals so you can stress test your thesis on Beiersdorf against other opportunities that meet the same standards.
- For investors hunting for stability first and returns second, a curated 226 resilient stocks with low risk scores can highlight companies where business risk scores are already screened for you.
- If you care most about financial resilience, use the list of solid balance sheet and fundamentals (202 results) to focus on companies that pair cleaner balance sheets with underlying fundamentals you can interrogate in more detail.
- When you want something less widely followed but still grounded in quality metrics, the 614 high quality undiscovered gems can surface under-the-radar stocks that might deserve a place on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com