
Campbell's (CPB) Stock Looks Fairly Priced Relative To Its Earnings
Campbell's has seen its share price under pressure in recent years, and with the stock last closing at US$19.84, investors are increasingly asking whether that quote still lines up with the earnings the business produces. The key issue is how much of the recent share price weakness already reflects what the company is currently earning.
- Over the past 3 years the share price has fallen 42.7%, which puts the spotlight firmly on whether the earnings multiple now attached to Campbell's makes sense.
- The group relies heavily on steady cash generation from established food brands, which can shape how much investors are willing to pay for each dollar of profit if margins or volumes shift over time.
- The analysts covering Campbell's have run their own numbers. See what analysts think Campbell's's shares could be worth.
The stock's next move may depend on whether the current price is reasonable given Campbell's earnings power today.
If you are weighing Campbell's after a 42.7% share price decline over three years, a focused stock screen can be a useful second lens. You can start with 33 high quality undervalued stocks.
Does Campbell's Look Undervalued on Earnings?
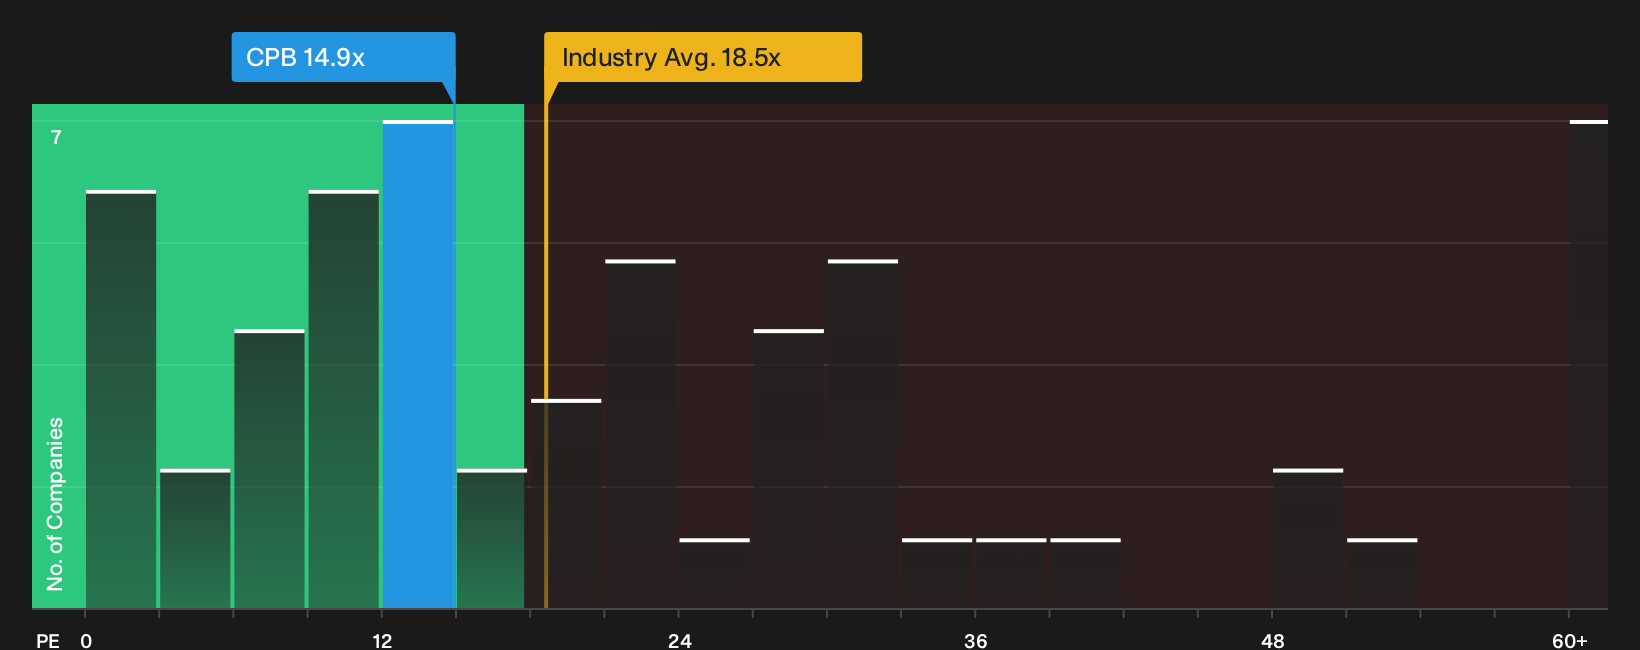
A P/E lens fits Campbell's because earnings still anchor most of the investment debate for a mature food producer. On this measure, the stock trades at about 14.9x earnings, slightly above the peer group average of roughly 13.7x, yet below the broader Food sector on about 18.5x. That places the share price in a middle ground where investors are paying a modest premium to close comparables but not a sector level price tag.
The Fair Ratio here reflects what a more tailored model suggests could be appropriate for Campbell's, given its profitability profile, sector, size and risk characteristics. The current P/E sits below that reference point, which indicates the market is assigning a lower multiple than this framework would imply. For anyone weighing the recent share price slide against what the business currently earns, the gap between the live P/E and the Fair Ratio is the key tension to explore further. Explore the numbers behind Campbell's's P/E valuation.
The Campbell's Narrative: What Would Justify Today's Price?
Narratives for Campbell's pick up where that P/E puzzle leaves off, by spelling out which growth paths, margin levels and earnings profiles would need to play out for the stock to look meaningfully cheaper or more expensive than today’s quote. Rather than one headline multiple or model output, each framework sets out the assumptions behind its own view of fair value so you can compare those inputs with the results Campbell's actually delivers on Simply Wall St's Community page.
One of the top community narratives on Campbell's: roughly fairly valued
"The main factor that needs to go right is that Campbell's delivers the planned US$500 million cost saving program and productivity gains…"
Discover why this Narrative puts Campbell's at roughly fairly valued.
Before you decide on Campbell's, one more question matters
Valuation only tells part of the story for Campbell's, and the research here has also surfaced specific risk checks that could change how you weigh everything you have just read. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com