
Seraku (TSE:6199) Q4 Earnings Strengthen Its Case As A Cheap Stock
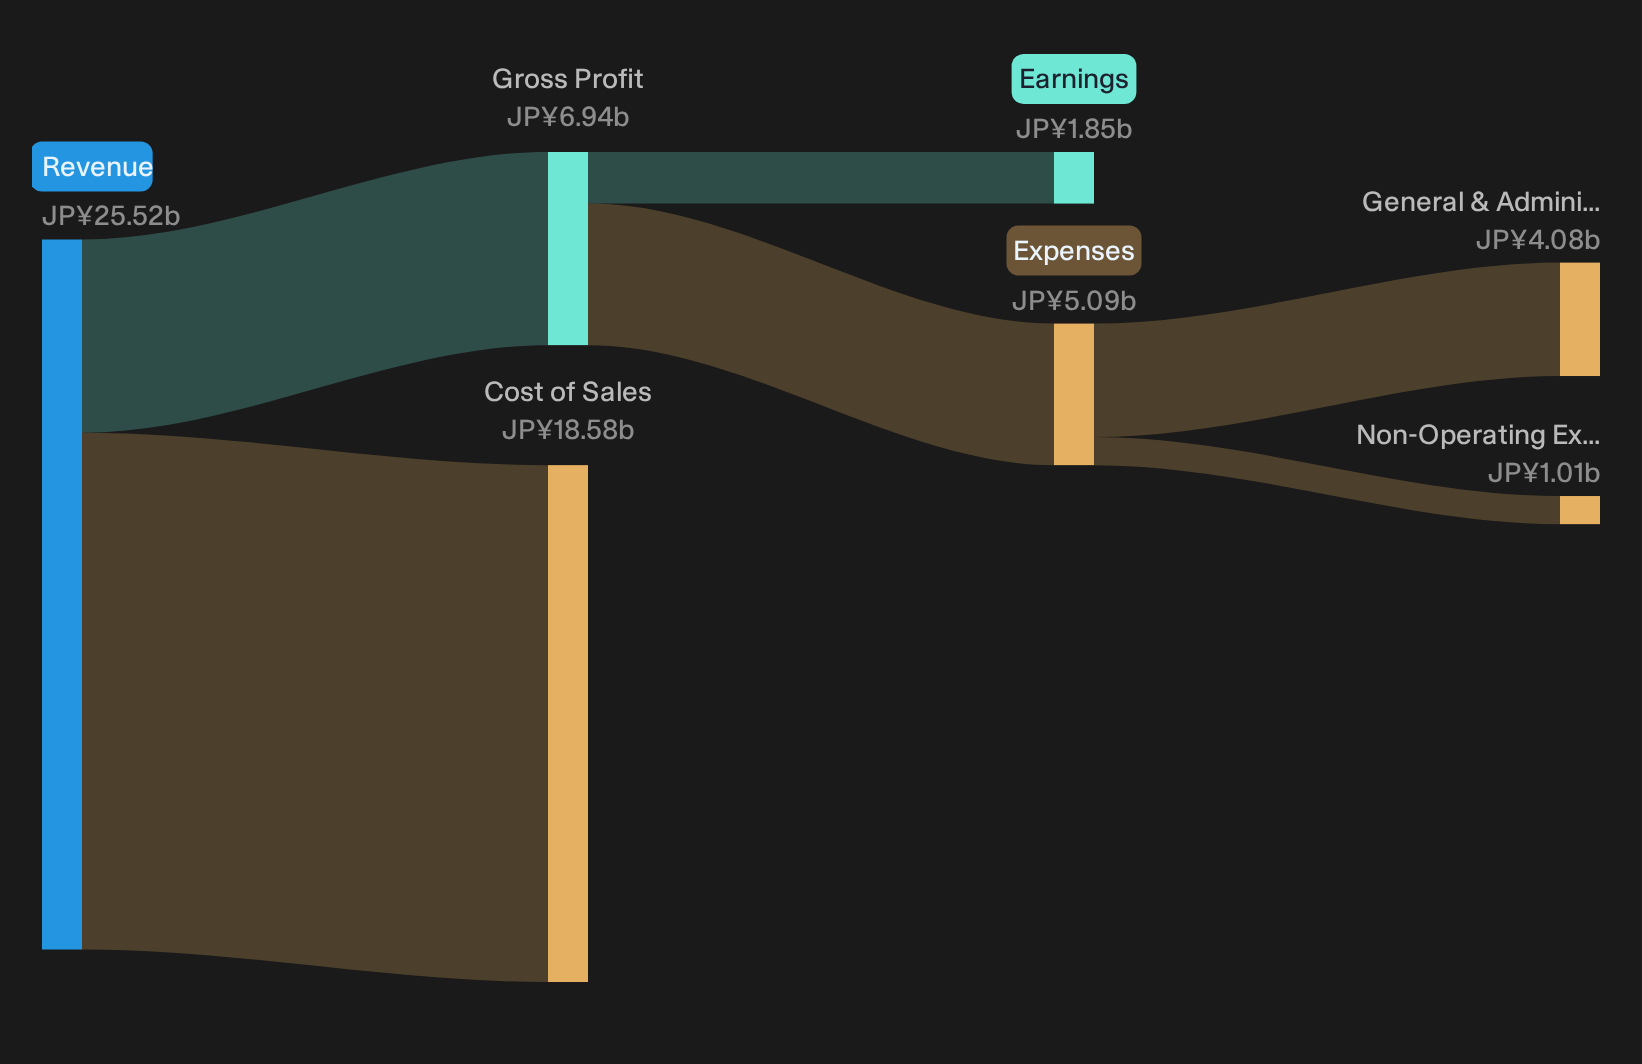
Seraku entered this Q4 2026 earnings print with a reputation as a steady, higher quality Japanese IT services stock trading on a discounted 10.9x P/E. The fresh numbers now require investors to test that thesis against the reported data. Basic earnings per share for the quarter were ¥46.36 on revenue of ¥6,606.24 million, while trailing net margin for the year was 7.3%. With the share price closing at ¥1,542 on 16 October, the market reaction still appears modest relative to the valuation gap and the profit profile reported.
If you appreciate the earnings power at Seraku but prefer a broader selection of solid operators at reasonable valuations, explore our 14 high quality undervalued stocks to compare this Q4 result with other high quality discounted stocks.
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs. Q4 2025): ¥6,606.24m vs. ¥6,230.49m (up about 6.0%)
- Net Income (Excl. Extra Items, Q4 2026 vs. Q4 2025): ¥606.34m vs. ¥393.84m (up about 54.0%)
- Basic EPS (Q4 2026 vs. Q4 2025): ¥46.36 vs. ¥29.48 (up about 57.0%)
- Trailing Net Profit Margin (FY 2026 vs. FY 2025): 7.3% vs. 6.9% (margin level higher year on year)
Ask Charlie what makes SERAKU’s earnings forecast turn negative.
Seraku’s DX Story Backed By Earnings Trajectory
For investors leaning into Seraku as a dependable digital transformation and cloud integrator, this set of figures broadly supports that story. Revenue of ¥6,606.24m and net income of ¥606.34m were ahead of the prior year’s Q4, and basic EPS climbed to ¥46.36. A trailing net margin of 7.3%, slightly higher than last year, fits the idea of a solid IT services provider slowly improving profitability while executing across DX, cloud, and cybersecurity themes.
Where The Seraku Caution Flags Still Flicker
Bears who worry about wage pressure or project work eating into profitability will not find fresh confirmation here. Margin edged up from 6.9% to 7.3%, so near term pressure looks contained rather than escalating. The stock’s 90 day gain of about 24.8% indicates that investors have been rewarding execution. This makes any future slips in utilization, engineer supply, or DX project timing more important to track if you are concerned about the staffing heavy parts of Seraku’s model.
After a 90 day gain of about 24.8% and firmer margins, any stumble in Seraku’s DX execution or staffing model could matter more than usual. Review the independent risk analysis for SERAKU which shows 1 important warning sign to see whether this quarter’s clean snapshot masks deeper structural pressure points or emerging earnings fragility.Hunt For Mispriced Earners
SERAKU’s latest quarter shows that earnings and share moves can leave important questions open. The real opportunity sits in finding companies that could be undervalued before the market fully absorbs their business momentum.
- Company 1 - 35% below our estimate - builds and maintains infrastructure for local authorities as assets age and environmental standards tighten. The real opportunity sits in stocks that could be undervalued before attention shifts to this work.
- Company 2 - 34% below our estimate - sells workflow tools to teams once manual processes break under heavy project loads and remote collaboration. The real opportunity sits in stocks that could be undervalued before adoption and usage trends become clearer.
- Company 3 - 37% below our estimate - manages virtual creators whose fan bases support recurring digital events, merchandise, and branded content. The real opportunity sits in stocks that could be undervalued before demand for these communities is fully recognised.
Those are three of them. See all 14 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com