
TWOSTONE&Sons (TSE:7352) Can Q4 Earnings Sustain Its Profit Rebound?
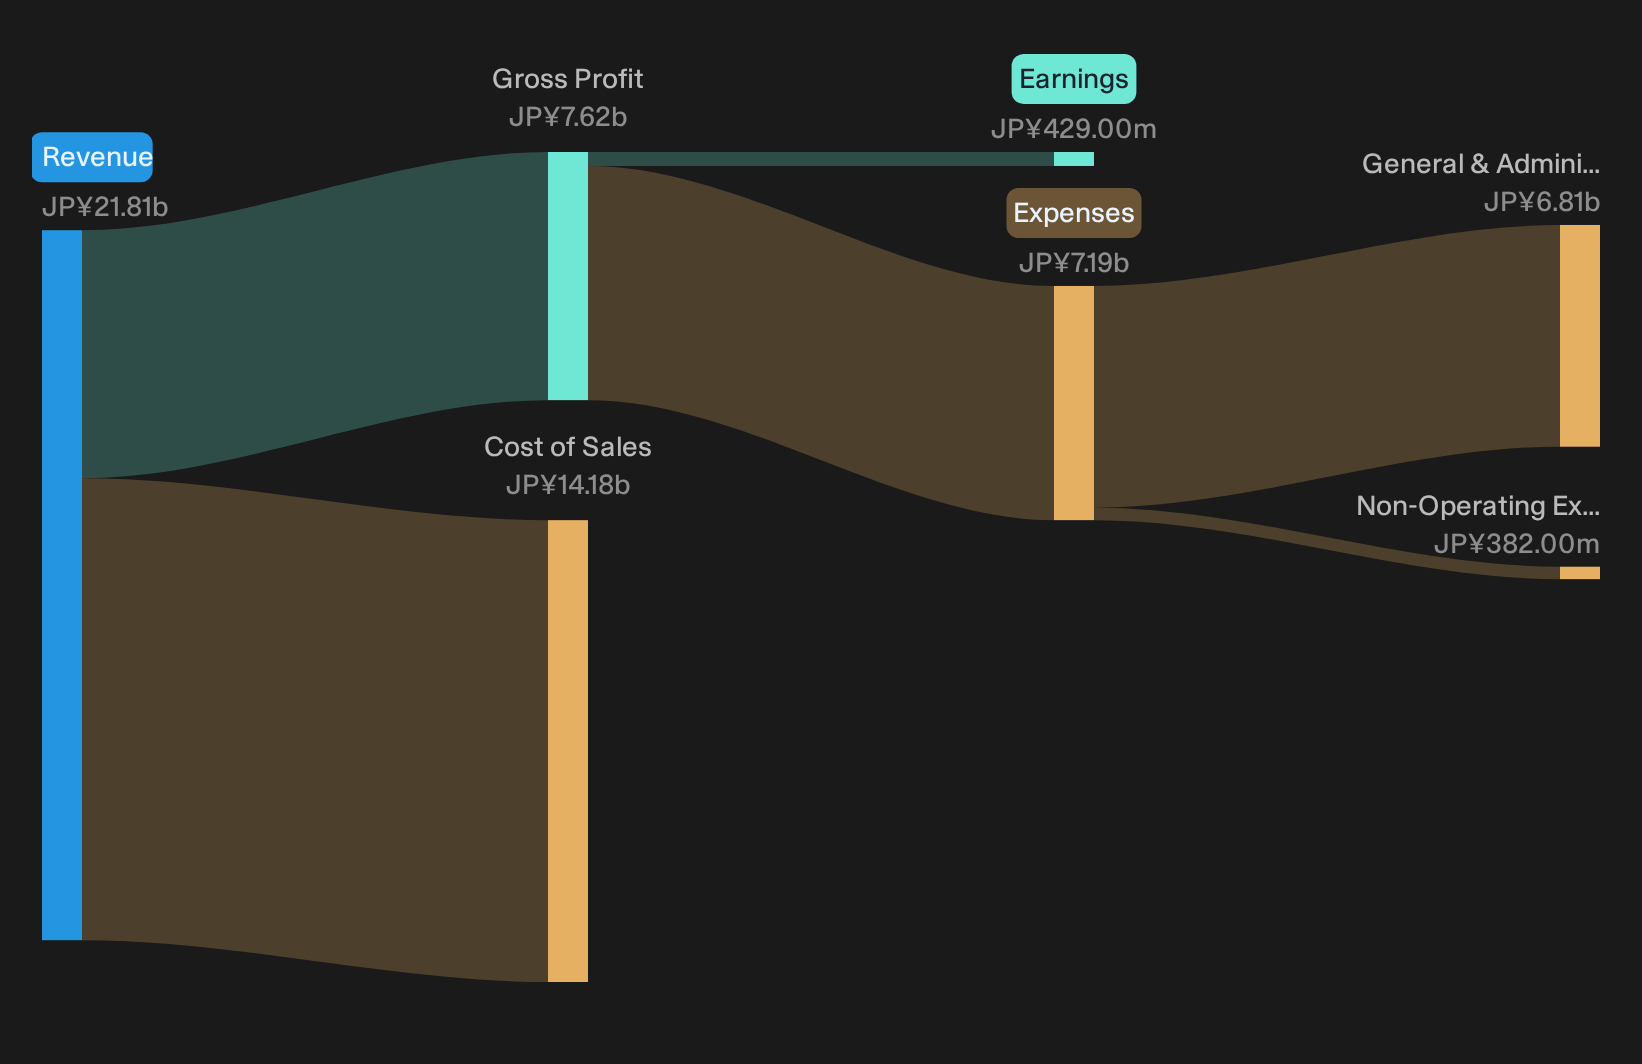
TWOSTONE&Sons just printed its Q4 2026 scorecard and the headline is clear. The stock came into today riding strong short term momentum, with double digit gains over 7, 30 and 90 days, yet the fresh numbers point to a very different question for holders. Earnings power is improving on paper, anchored by basic EPS of ¥2.26 on quarterly revenue of ¥5,926 million. However, that sits against a rich 52x trailing P/E and a price already above one discounted cash flow estimate.
Like the earnings profile at TWOSTONE&Sons but uneasy about paying a rich 52x trailing P/E on a single stock story? Consider shifting some attention to a screener of companies that pair solid balance sheets with stronger valuation support using our list of solid balance sheet and fundamentals stocks (21 results).
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs Q4 2025): ¥5,926 million vs. ¥4,675 million (up about 26.8%)
- Net Income (Excl. Extra Items, Q4 2026 vs Q4 2025): ¥101 million vs. a loss of ¥78 million (moved back into profit)
- Basic EPS (Q4 2026 vs Q4 2025): ¥2.26 per share vs. a loss of ¥1.79 per share (returned to positive earnings per share)
- Trailing 12 Month Net Income (Excl. Extra Items, Q4 2026 vs Q4 2025): ¥429 million vs. ¥494 million (down about 13.2%)
Ask Charlie what TWOSTONE&Sons’ premium price is betting on.
TWOSTONE&Sons earnings tilt the story bullish
For a bullish narrative around TWOSTONE&Sons as an IT talent and DX, digital transformation, platform play, this quarter gives some support. Revenue of ¥5,926 million versus ¥4,675 million a year ago points to healthier client demand across recruitment and services. Profitability also looks better. The move from a quarterly loss to ¥101 million in earnings and positive EPS of ¥2.26 suggests the model can generate cash when volumes cooperate. For investors focused on business direction rather than labels, that mix of higher sales and restored profit will feel constructive.
Bear signals linger around earnings quality
The bear case does not disappear. Trailing 12 month net income excluding extra items slipped from ¥494 million to ¥429 million, so the full year picture is softer than the single quarter headline. That gap can worry anyone who fears margins in crowded IT staffing and consulting markets. Short term share price strength, with strong 7, 30 and 90 day returns, also raises the question of how much good news is already reflected. TWOSTONE&Sons now has to show that recent profit is repeatable, not just a one quarter rebound.
After a swing from losses to profit and a share price that moved sharply over the past quarter, it is fair to ask whether TWOSTONE&Sons has just smoothed over deeper fragilities or if there are structural red flags around earnings quality, client exposure or execution risk that are easier to miss. Review the full risk analysis for TWOSTONE&Sons which shows 1 important warning signHunt For Quieter Earnings Power
TWOSTONE&Sons just reminded investors how quickly a narrative can shift when a single quarter reframes the income statement. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 26% below our estimate - supplies specialized photomasks and molds that chipmakers rely on as device geometries keep tightening.
- Company 2 - 36% below our estimate - designs complex air and heat systems that building owners upgrade when data centers and hospitals raise reliability demands.
- Company 3 - 24% below our estimate - sells optical and electronic materials that device makers adopt as screens, sensors and communication hardware become more demanding.
Three companies from the same screener. Open every one of the 14 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com