
How Investors Are Reacting To Aramark (ARMK) Earnings Estimate Upgrades
- Aramark recently attracted attention after analysts highlighted a strong Growth Score, a top Zacks Rank, and earnings per share expectations that compare favorably with its industry this year.
- The more interesting angle is that upward earnings estimate revisions point to analyst confidence in Aramark’s current operating model and near term execution, rather than a single contract win or one off catalyst.
- We will now look at how Aramark’s investment narrative could be influenced by these upward earnings estimate revisions and growth signals.
Scan the analyst-backed growth story at Aramark against other potential movers by running the curated list of 33 high quality undervalued stocks as a comparison set.
Aramark Investment Narrative Recap
To own Aramark, you need to be comfortable with a contract driven services model that depends on steady wins, very high retention, and tight execution on food and labor costs across thousands of sites. The recent improvement in earnings expectations supports that this operating playbook is working today, so the near term catalyst is continued delivery on existing contracts rather than a new story.
The biggest operational swing factor right now is free cash flow and leverage. Interest costs are not yet comfortably covered by earnings, and net profit margins sit around 1.9%. If stronger earnings do not translate into better cash conversion and balance sheet breathing room, the scope to fund technology, AI data center hospitality, and shareholder returns at the same time looks tighter.
In that context, the most relevant operational thread is Aramark’s push into higher margin, lower capital intensity areas such as Nexus, its AI data center hospitality platform. Management sees three Nexus sites reaching an annualized US$400m to US$500m revenue contribution in fiscal 2027 and 2028, with margins above the group average and relatively modest capital needs.
For you as an investor, this matters because it directly ties into the main catalysts behind the current earnings narrative. Higher margin segments like Nexus, together with international growth and strong education contracts, could help ease pressure from low free cash flow margins and interest coverage risk if execution stays tight. The recent upward shift in earnings estimates lines up with that operational story but does not remove the need to watch cash generation and reputational risks closely.
Aramark Through The Numbers
For Aramark, the current analyst story is built on a specific math set, not just a general sense that things look better. The forecasts link revenue growth, margin expansion, and the earnings outlook into one tighter frame that you can test against your own expectations.
Analysts are currently assuming that Aramark can lift revenue by 8.0% each year over the next few periods while shifting net profit margins from 1.9% today to 3.5% in three years. On those assumptions, earnings are projected to move from US$382.9 million today to US$867.8 million by 2029, which is a rise of about US$485 million in absolute profit. That forecast level also aligns with a consensus view of earnings per share at US$3.44 around October 2029.
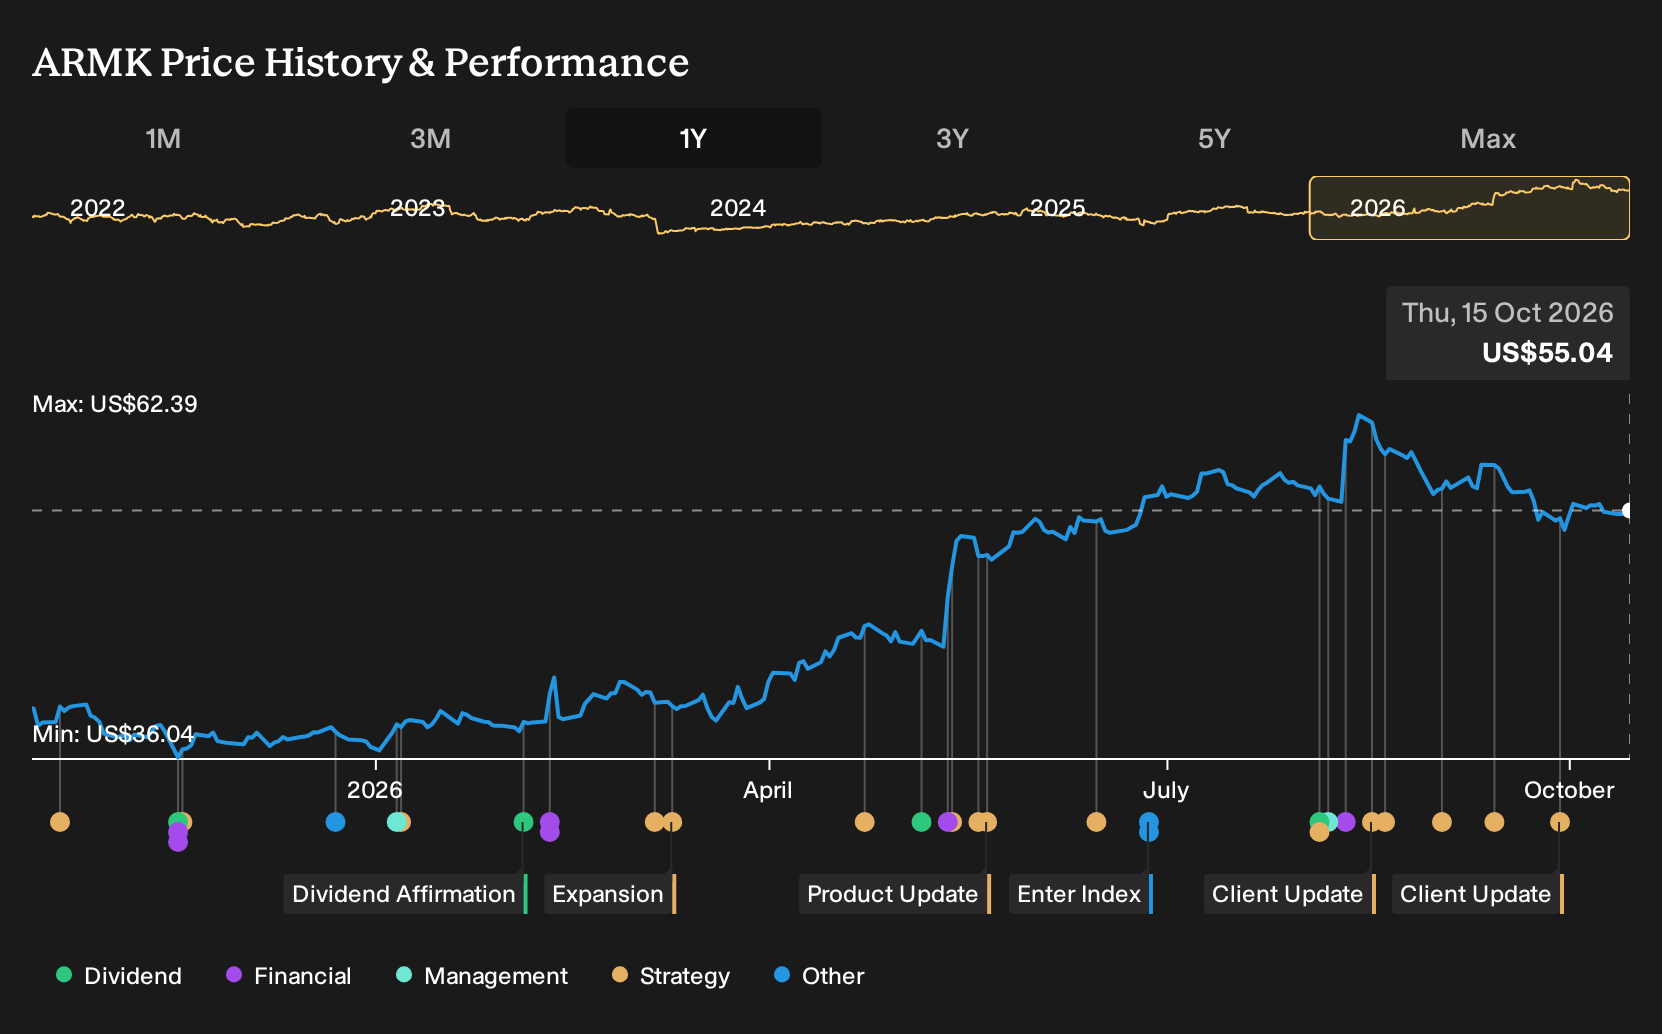
Valuation work in the consensus set then plugs those operating estimates into a price framework. For investors to line up with the analyst targets, the scenario implies revenues of US$25.0b and earnings of US$867.8 million in 2029, with the stock trading on a P/E of 27.5x using a discount rate close to 9.5%. That compares with a current multiple of 37.6x on today’s earnings and an industry P/E reference point of 19.0x for US hospitality peers.
Analysts also build in a modest lift in the share count, with total shares on issue projected to rise by 0.26% per year over the next three years. That assumption matters because even if total earnings track the US$867.8 million number, incremental issuance can dilute earnings per share, which is what the market usually prices most directly.
Aramark's narrative projects US$25.0b revenue and US$867.8 million earnings by 2029. This rests on 8.0% yearly revenue growth and an earnings increase of roughly US$485 million from US$382.9 million today.
Uncover why Aramark's fair value indicates a 24% potential upside to its current price before the discount closes.
Exploring Other Perspectives
One angle you might test against the upbeat Zacks signal on Aramark is the more cautious take on Nexus and data center hospitality. The lowest analysts were already penciling in about US$24.7b of revenue and US$878.8 million of earnings by 2029 before this news, yet still arrived at a muted price outlook. That gap shows how widely opinions can differ, so it can be worth comparing several narratives before deciding how this update might change your own view.
Explore 2 other Aramark fair value estimates, including one that suggests as much as 35% downside from the current price.
Form Your Own Verdict
Don’t just follow the ticker. Dig into the data and build a conviction that’s truly your own.
- A great starting point for your Aramark research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aramark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aramark’s overall financial health at a glance.
Looking For More Investment Ideas Beyond Aramark?
If the Aramark story has sharpened your thinking about earnings quality, balance sheet pressure, and where growth might be priced in, it can help to test that framework on a wider set of listed businesses using the Simply Wall St Screener.
- For investors who prioritize financial resilience, scan a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without relying heavily on fresh capital.
- If you prefer opportunities where quality and price work together, compare Aramark against a 33 high quality undervalued stocks that combine stronger fundamentals with more conservative expectations baked into the share price.
- Income seekers can broaden their watchlist by reviewing 8 dividend fortresses that pair higher yields with a focus on sustainability and payout support from underlying cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com