
3 Canadian Growth Stocks To Own In October 2026
World Bank plans to multiply financing for critical minerals projects over the next few years, and that puts future focused Canadian businesses in the spotlight. Stronger backing for resources and related technologies can feed into healthier balance sheets and faster profit growth. This article walks through a group of financially solid Canadian high growth prospects and highlights three stocks that analysts expect to deliver especially strong earnings momentum.
The three stocks highlighted here offer a compelling starting point if you want exposure to healthy high growth potential businesses that still keep an eye on financial discipline. However, if you want the absolute best, these 19 best high growth potential stocks are the cream of the crop.
Hemlo Mining (TSX:HMMC)
Overview: Hemlo Mining is a Toronto based gold producer focused on its 100% owned Hemlo gold mine in northwestern Ontario.
Market Cap: CA$1.45b
Hemlo Mining plugs neatly into the Healthy high growth potential theme because analysts see earnings rising 42.92% a year for three years, backed by forecast revenue growth of about 25% and a recently profitable operation at the Hemlo mine. That kind of forecast depends heavily on how one unseen pressure shapes future drilling returns and capital efficiency.
That hidden pressure point is exactly what the DCF valuation analysis for Hemlo Mining weighs up, so you can see how the drilling story lines up with the cash flow math.
LunR Royalties (TSX:LUNR)
Overview: LunR Royalties is a Vancouver based royalty and streaming business giving investors indirect exposure to copper, gold, and silver production.
Market Cap: CA$1.95b
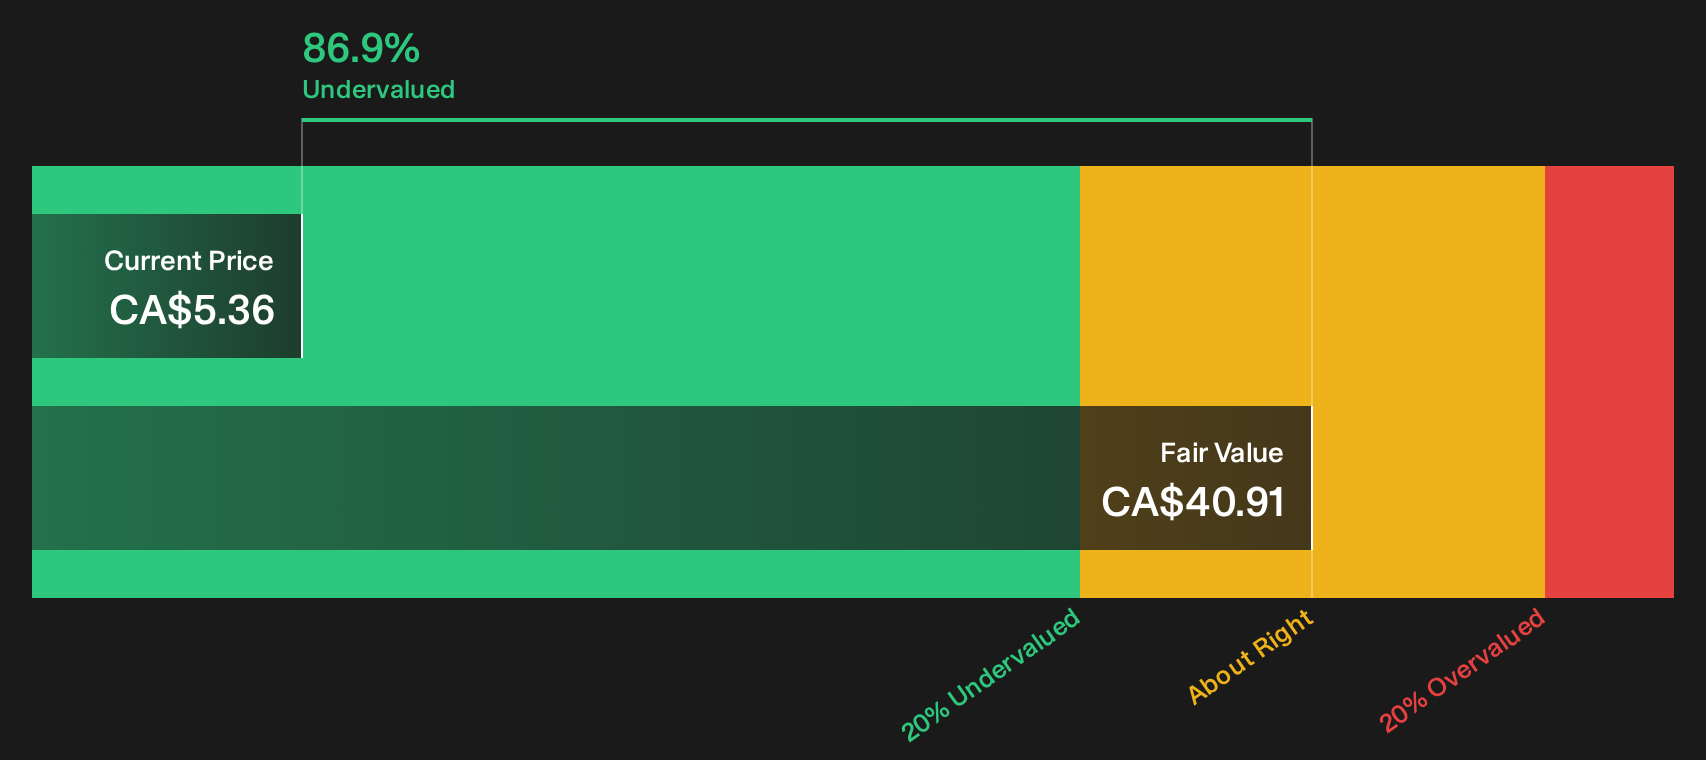
Earnings for LunR Royalties are forecast to grow about 66.9% a year, with revenue expected to rise 39.5% annually as copper and gold royalties ramp. That growth outlook fits the Healthy high growth potential theme. However, current losses, a rich valuation, and reliance on third party mine progress mean outcomes will hinge on how one pressure point around future royalty delivery plays out.
That hinge point is exactly what the 2 key rewards and 1 important major warning sign reveals, so you can see how LunR Royalties’ upside and pressure points line up before conditions shift again.

Toromont Industries (TSX:TIH)
Overview: Toromont Industries supplies and rents Caterpillar-based power systems, heavy equipment, and CIMCO refrigeration solutions, with recurring service support.
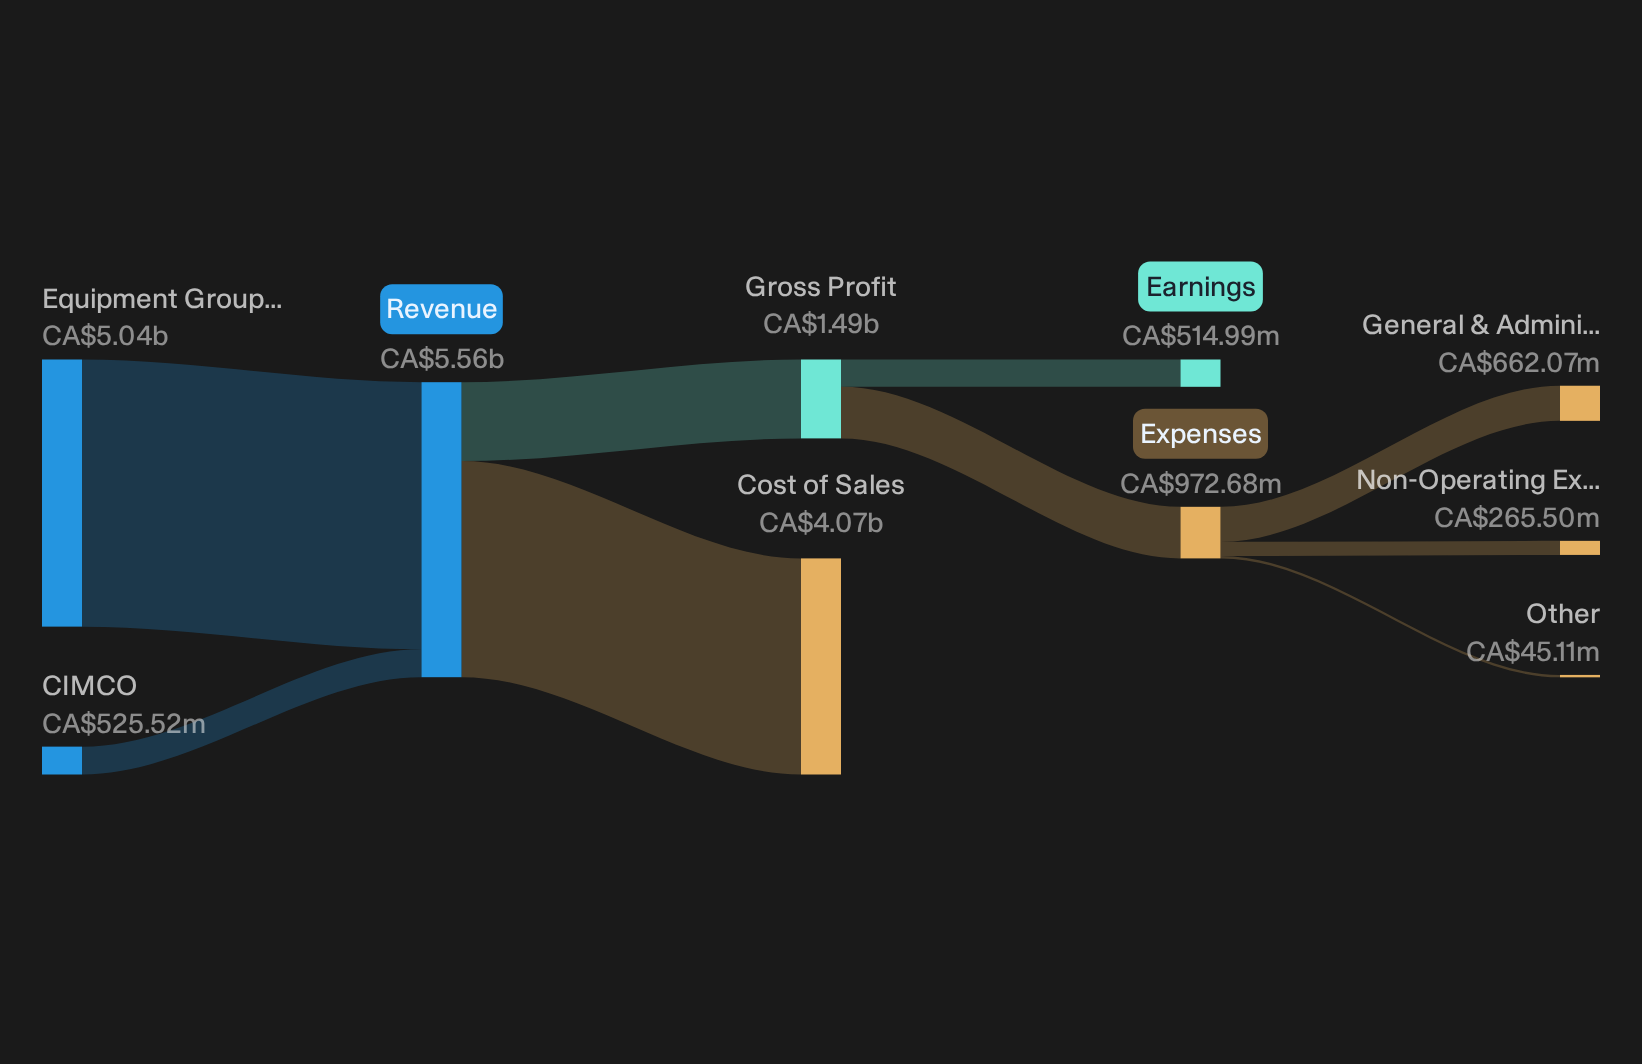
Operations: Toromont generates about CA$5.0b in revenue from its Equipment Group and CA$526 million from CIMCO refrigeration operations.
Market Cap: CA$17.36b
Toromont Industries fits the Healthy high growth potential theme through its power systems and distributed generation work. Equipment sales link tightly with recurring rentals and service that can compound earnings over several years.
"The rapid ramp-up of AVL's production capacity, ongoing integration, and accelerated facility expansion in the U.S. positions Toromont Industries to capitalize on growing North American data center power demand."
The real swing factor for Toromont Industries is how one cost and execution pressure shapes future margins on that growing installed base.
That margin swing is exactly what the Toromont Industries story turns on, and the full narrative for Toromont Industries maps how execution risk and data center power demand could reshape earnings quality.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every investor notices a breakout, early entry points may already be dropping away. Scan these under the radar lists now and get in early.
- Spot cash rich compounders before momentum headlines catch them by using the list of solid balance sheet and fundamentals (8 results) built to surface resilient balance sheets while that edge still matters.
- Track early income workhorses while yields remain elevated by scanning the 3 dividend fortresses so you see which payers could hold up when others start cutting.
- Target the power shift into uranium, grid build outs, and plant upgrades by reviewing the 16 nuclear energy infrastructure stocks that focuses on nuclear infrastructure while it stays under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com