
How Investors May Respond To NESR Stock Saudi Expansion And Aramco Lithium Deal
- National Energy Services Reunited, through its NEDA segment, has agreed to execute Aramco’s 2027 Lithium Demonstration Project in Saudi Arabia. This is a turnkey LiThara platform contract with potential value of about US$200 million over up to five years, targeting 2,000 tpa of battery grade lithium carbonate from late 2027.
- The planned US$1b equipment spend over five years to support Saudi projects, including the Jafurah unconventional gas field, signals a heavier capital load and deeper exposure to Saudi energy and battery materials development for National Energy Services Reunited.
- We will now look at how National Energy Services Reunited’s investment narrative could shift as it commits US$1b to Saudi expansion.
Scan 16 nuclear energy infrastructure stocks to find other energy infrastructure stocks that, like National Energy Services Reunited, are tying oilfield know-how to the next wave of power and battery materials projects.
National Energy Services Reunited Investment Narrative Recap
To own National Energy Services Reunited, you need to believe its Middle East focus and long contracts with national oil companies can keep activity high, even as energy systems evolve. The Aramco lithium project and the US$1b Saudi equipment plan reinforce that thesis by tying the business even more tightly to Saudi spending and unconventional gas work.
The key near term swing factor remains execution and cash generation on large Saudi projects, especially Jafurah, alongside rising capital and working capital needs. The lithium demonstration is meaningful for the NEDA segment but looks secondary to the risk that heavy upfront spend and any contract delays could pressure liquidity and delay returns.
The Aramco 2027 Lithium Demonstration Project is the clearest operational bridge between NESR’s core oilfield toolkit and newer decarbonization themes. It formalizes the LiThara platform into a revenue backed contract, sized at up to US$200 million over as long as five years, and ties commissioning to late 2027.
For you as a shareholder, the lithium plant matters because it tests whether NEDA can become a material third leg alongside Production Services and Drilling and Evaluation. It also sharpens execution risk. Direct lithium extraction, pre treatment and carbonation introduce new technical and project delivery variables on top of NESR’s already heavy Saudi capital program.
National Energy Services Reunited's current analyst narrative points to revenues of US$3.4b and earnings of US$456.7m by 2029. That path assumes revenue growth of 27.5% per year and an earnings increase of about US$363m from US$93.4m today.
Uncover how National Energy Services Reunited's fair value indicates a 119% potential upside to its current price before other investors close that difference.
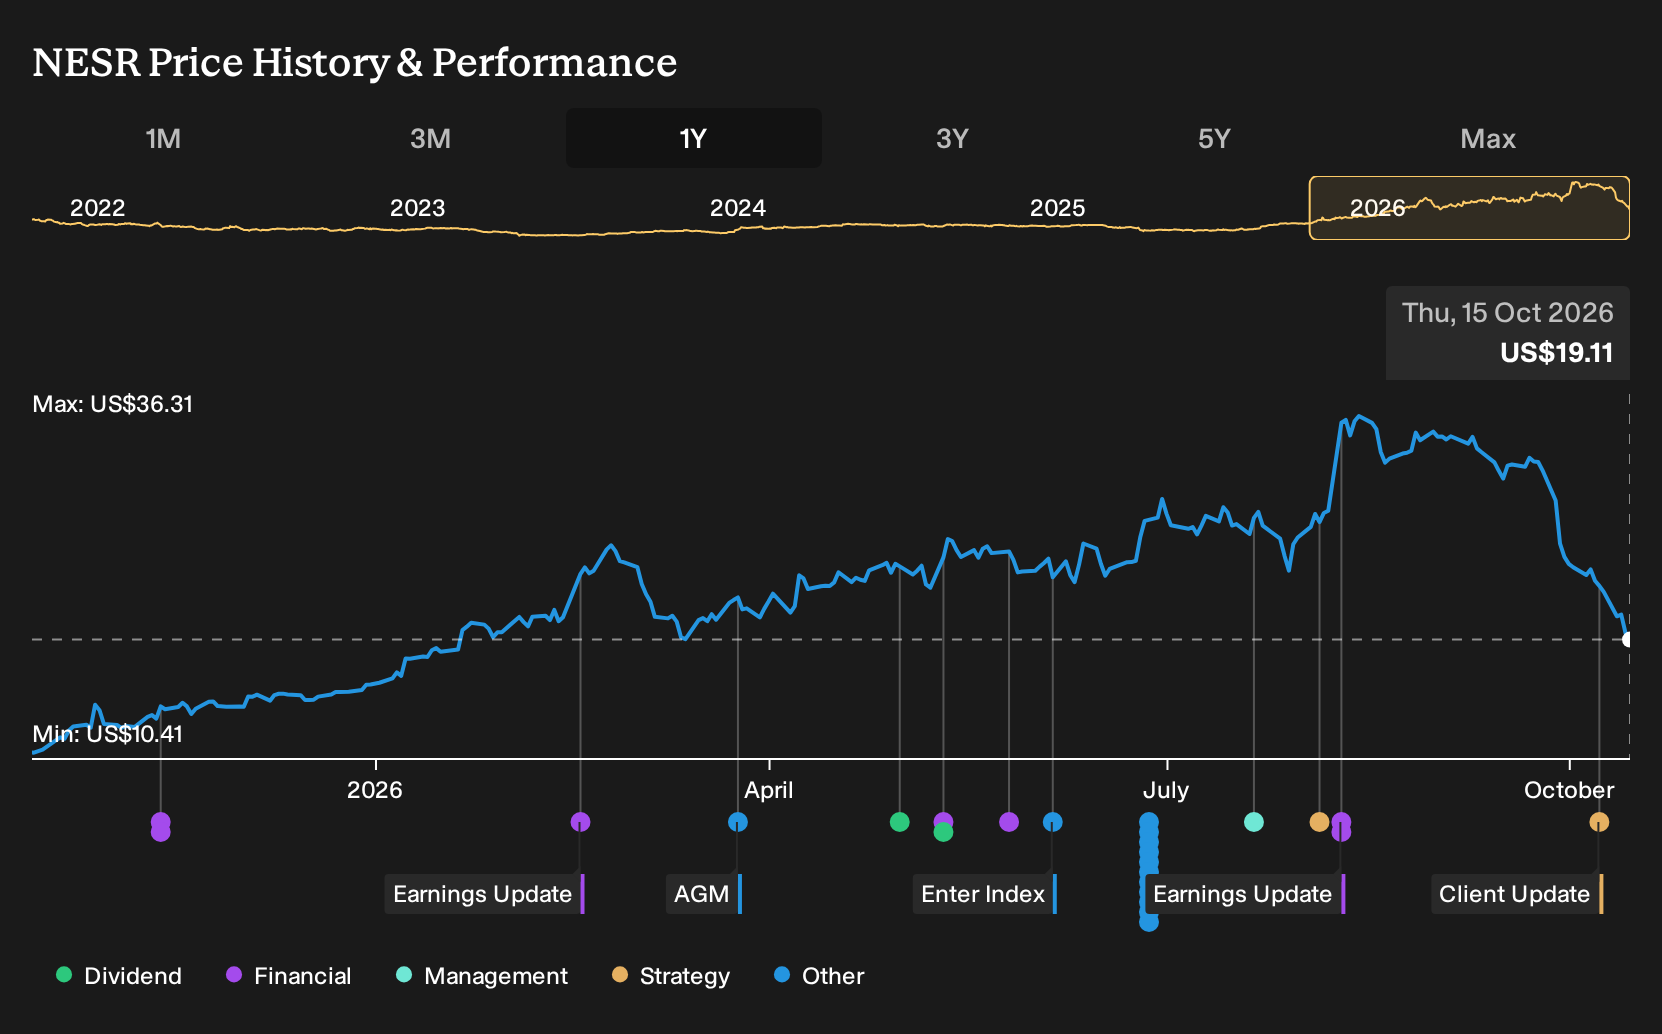
Exploring Other Perspectives
One alternate view on National Energy Services Reunited leans hard into the risk that heavy NEDA and digital spending keeps profitability lower for longer. Those more cautious analysts were penciling in about US$3.2b of 2029 revenue and earnings near US$380.1m before this lithium news, so their narrative may shift quite differently from consensus. Readers like you can use that spread in expectations to explore how sharply opinions on the same set of projects can diverge.
Explore 4 other National Energy Services Reunited fair value estimates, including one that suggests it could be worth just $35.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your National Energy Services Reunited research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for National Energy Services Reunited. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Energy Services Reunited's overall financial health at a glance.
Looking for more investment ideas beyond National Energy Services Reunited?
Fresh ideas matter as much as a single strong thesis on National Energy Services Reunited. If you want to broaden your watchlist, the Simply Wall St Screener can help you quickly filter for other stocks that fit different risk and return profiles without trawling through endless tickers on your own.
- If capital preservation comes first for you, start with a group of 32 resilient stocks with low risk scores that score well on resilience and lower volatility.
- If quality at a reasonable entry point is the priority, scan our 33 high quality undervalued stocks that pair stronger balance sheets with more appealing valuations.
- If you enjoy getting in early on quieter stories, the 20 high quality undiscovered gems can surface lesser known companies with healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com