
How Publix Renewal Will Impact Western Union (WU) Stock
- The Western Union Company and Publix Super Markets recently renewed their long running agreement, keeping money transfers, money orders, and bill payment services available across Publix stores in the Southeast as the grocer extends into new states including Kentucky.
- This extension keeps Western Union embedded in everyday grocery traffic, which can matter for sustaining retail transaction volumes while the business builds out digital channels and consumer services.
- The focus now shifts to how Western Union's investment narrative aligns with this extended Publix access to essential financial services.
Scan how Western Union's renewed Publix reach compares to other financial services stocks tapping everyday consumer traffic through our curated list of solid balance sheet and fundamentals (25 results) for potential long-term resilience.
Western Union Investment Narrative Recap
To own Western Union, you need to be comfortable with a story that blends a shrinking higher margin cash footprint with a push into lower margin digital channels and broader consumer services. The renewed Publix deal keeps the retail side visible inside everyday grocery trips, but on its own it is unlikely to shift the near term earnings picture in a big way.
The more immediate swing factor remains whether cost cuts, product mix and Consumer Services growth can offset pressure from lower revenue per digital transaction. The sharp margin compression from 21.8% to 9.8% keeps profitability risk front of mind, while regulatory issues and remittance corridor weakness add another layer that the Publix renewal does not really change.
The most relevant context for this Publix renewal is Western Union’s push to diversify through its Consumer Services segment, which includes bill pay and travel money. That unit produced US$575.9m of revenue out of the group’s US$4.0b, with strong recent growth rates of 33% in Q1 2026 and 12% in Q2 2026 according to prior disclosures.
Retail access at Publix plugs directly into that Consumer Services story, because customers can handle remittances and bills alongside weekly shopping. For you as an investor, the key question is whether this type of embedded distribution, together with cost savings from the Beyond Efficiency program and digital wallet rollouts, can gradually offset pressure from regulation, corridor weakness and lower margin online flows.
Western Union's current analyst script points to revenues of US$4.6b and earnings of US$445.9m by 2029, based on an assumed 4.2% yearly revenue growth rate and an earnings increase of about US$50.5m from US$395.4m today.
Uncover why Western Union's fair value indicates a 10% potential upside to its current price before the discount narrows.
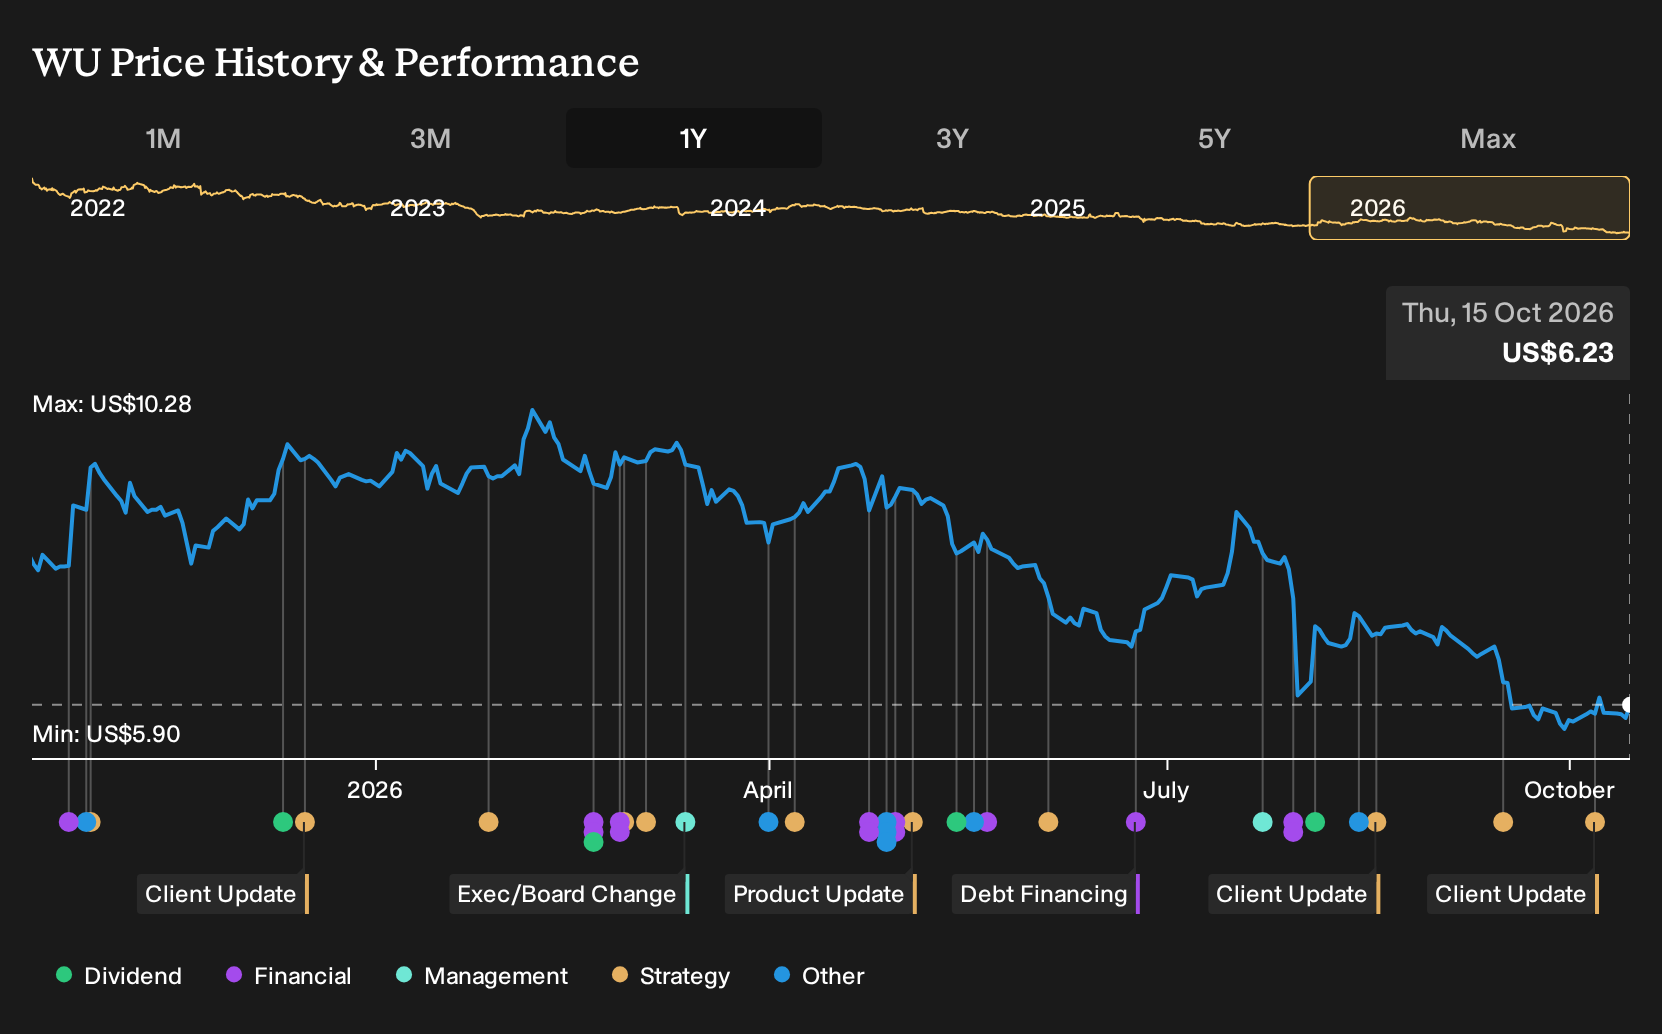
Exploring Other Perspectives
One alternate angle around Western Union focuses less on digital expansion and more on the risk that newer services still do not fully cover softness in core money transfer. The most cautious analysts were working off revenue expectations of about US$4.2b and earnings near US$428.1m by 2029 before this Publix renewal, so their story is clearly more pessimistic. You can treat this fresh agreement as a chance to reassess those weaker assumptions and compare several viewpoints before deciding what makes sense for you.
Explore 5 other Western Union fair value estimates, including one that suggests it could be worth just $6.66.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Western Union research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Western Union. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Western Union's overall financial health at a glance.
Looking For More Investment Ideas Beyond Western Union?
Once you have a view on Western Union, it can help to set that opinion against a wider watchlist of companies with different risk and return profiles. The Simply Wall St Screener gives you a quick way to line up alternatives that match the kind of balance sheet strength, income profile, or upside potential you want to focus on next.
- If capital preservation ranks high for you, start with a 32 resilient stocks with low risk scores that filters for businesses with more resilient characteristics.
- For investors who care most about long term durability, compare Western Union with a list of solid balance sheet and fundamentals (25 results) and see which companies better fit your comfort zone.
- If you are hunting for ideas that the market may not fully be paying attention to yet, scan through a 20 high quality undiscovered gems that surfaces under-the-radar opportunities with strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com