
3 Oil And Gas Stocks Retail Investors Are Watching For Margin Upside
Oil prices are swinging on headlines, the IEA is releasing emergency reserves, and shipping routes near the Middle East are under threat. That mix is reshaping how integrated oil and gas producers are priced and perceived, creating potential openings as well as traps. This article walks through three Global Integrated Oil & Gas Producers from our screener that appear positively exposed to these shocks so you can judge whether they deserve a closer look.
The three stocks covered next are just a sample from this theme, and the full screen surfaced 8 more large integrated producers with equally compelling narratives that are not discussed in the article. To identify and analyze the highest-conviction ideas for your watchlist, head straight to the Global Integrated Oil & Gas Producers screener.
Rabigh Refining and Petrochemical (SASE:2380)
Rabigh Refining and Petrochemical runs an integrated refining and petrochemicals complex in Saudi Arabia, tying it closely to the Global Integrated Oil & Gas Producers theme and regional crude pricing. It generated about SAR11.2b from petrochemicals and SAR43.9b from refined products, with a market value near SAR37.8b.
Rabigh Refining and Petrochemical provides exposure to a large integrated Middle Eastern complex that turns crude into fuels and plastics, in a region where geopolitical risk and supply headlines are closely watched. Its recent profitability and scale may make it a company to monitor, depending on how future conditions affect margins.
That margin risk is exactly why you may want to review the 3 key rewards and 3 important warning signs (2 are major!) before conditions reset expectations around this integrated complex.

Viva Energy Group (ASX:VEA)
Viva Energy Group is one of the clearest plays on the Global Integrated Oil & Gas Producers theme in Australia, combining a large fuel retail network with a significant refining and supply platform that can be sensitive to swings in crude and product margins.
Viva Energy Group operates a broad fuel and convenience network across brands like Shell and OTR. It supplies commercial customers through its A$12.8b Convenience & Mobility and A$17.2b Commercial & Industrial segments, while its Geelong refinery anchors the A$7.6b Energy & Infrastructure arm, underpinned by a market value of about A$5.2b.
For investors watching how integrated downstream businesses might convert margin volatility into earnings power, Viva Energy Group puts a clear number on the prize.
"Integration of acquisitions, operational efficiency improvements, and technology upgrades are on track to deliver approximately $90 million of run-rate earnings uplift by end-2026, directly supporting margin expansion and EBITDA growth."
What really moves the needle from here is how one less visible pressure shapes the durability of those margins investors care most about.
That durability question is where the story gets interesting, and the full narrative for Viva Energy Group explains how Viva Energy Group’s earnings engine could accelerate or stall as those pressures shift.

Imperial Oil (TSX:IMO)
Imperial Oil is one of the purest fits for the Global Integrated Oil & Gas Producers theme, tying large scale Canadian upstream output directly into refining and chemicals. This matters when oil prices swing around headlines and investors want cash flow that runs through the full chain.
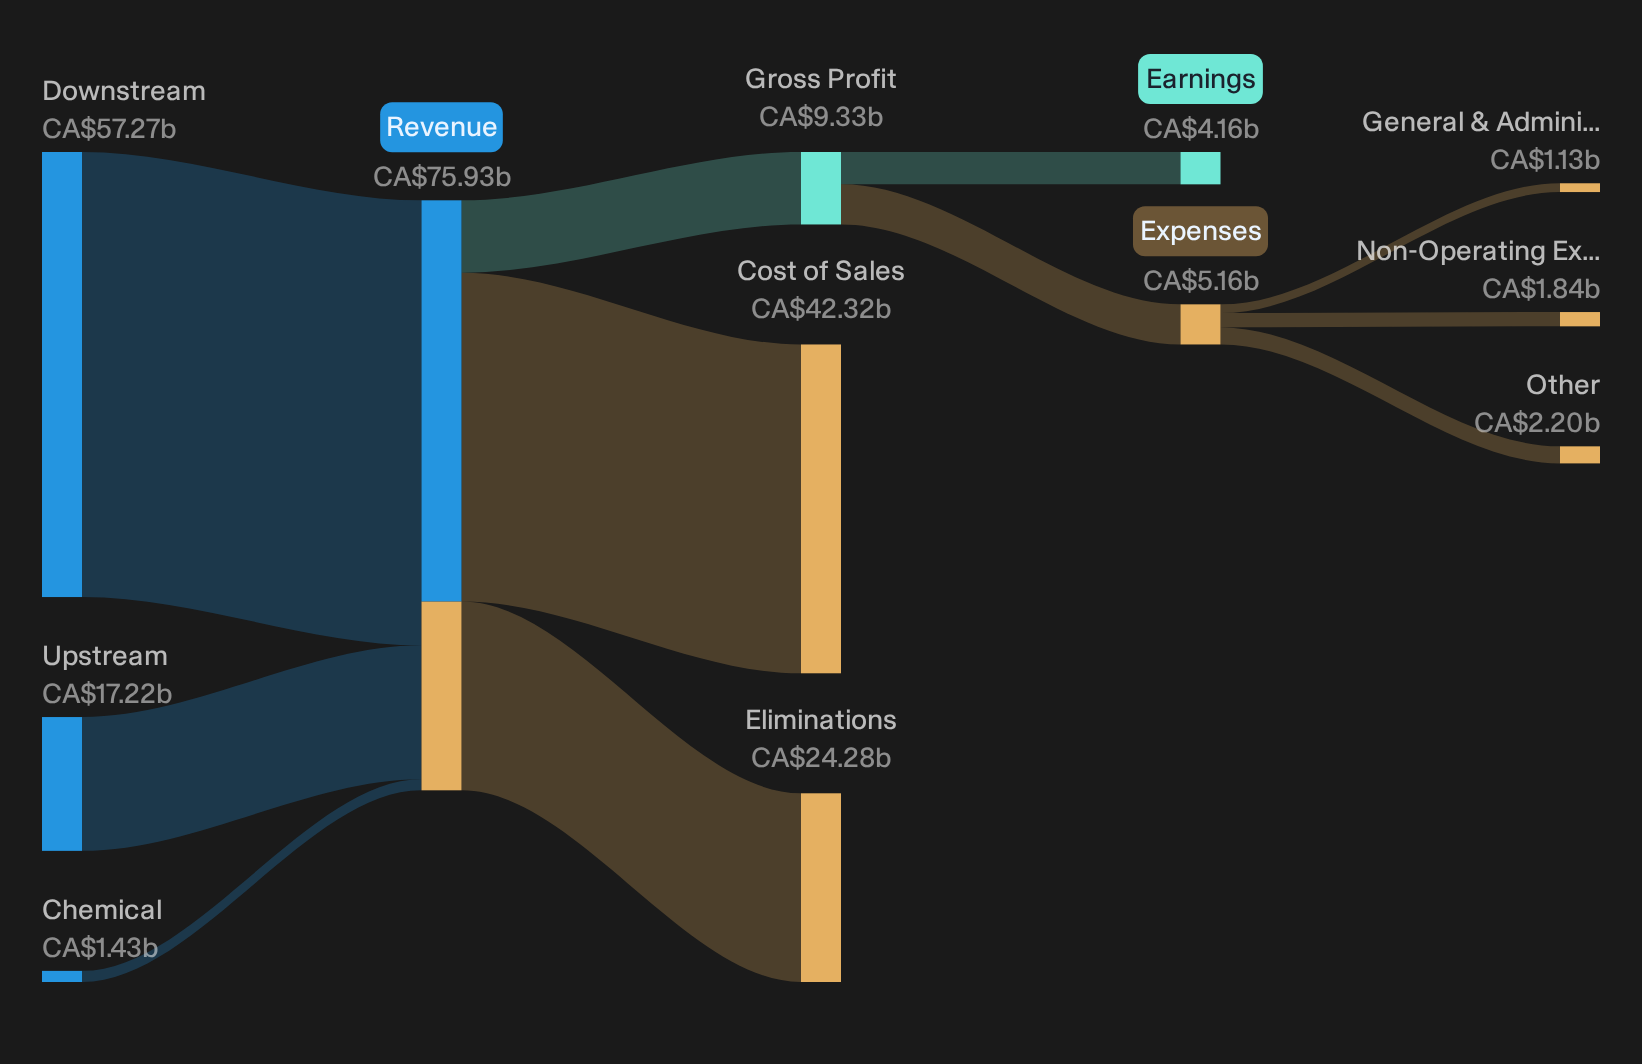
Imperial Oil runs a fully integrated model across Canada, earning about CA$57.3b from Downstream, CA$17.2b from Upstream and CA$1.4b from Chemical operations, and carries a market value near CA$89.4b.
"Major efficiency improvements at Kearl, including delivery of unit cash costs below US$20 per barrel in 2025 and a stated target of US$18 per barrel with 300,000 bpd by 2027, together with 4 year turnaround intervals now in place, support the view that Imperial Oil can keep lifting upstream net margins and earnings power."
What really determines how resilient Imperial Oil’s earnings stay is how one unresolved cost pressure interacts with that integrated oil sands and refining system.
If that cost pressure has your attention, the full narrative for Imperial Oil explains how it could affect Imperial Oil’s cash generation, capital returns, and any overlooked upside or downside.
Seeking Alternatives Before The Crowd
Fresh themes are breaking out while others lose momentum, and the strongest ideas rarely stay under the radar for long. Scan the next wave of potential leaders and act now.
- Spot cash generative compounding stories early by running the list of solid balance sheet and fundamentals (202 results) before the rest of the market notices what is happening on these balance sheets.
- Ride structural demand shifts by tracking the 41 power grid technology and infrastructure stocks as energy infrastructure spending moves, so you are not caught chasing stocks that are already moving.
- Position ahead of institutional interest by scanning 615 high quality undiscovered gems while these ideas are still appearing on the market radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com