
Hershey (HSY) Climbed, But What Is Drawing Fresh Attention?
Hershey (HSY) is back in focus after the share price gained 2.7%, outpacing the S&P 500 as traders position ahead of the October 29 earnings release and evaluate potential EPS performance.
The latest move fits into a mixed picture for Hershey. The stock’s 7-day share price return of 3.8% suggests short term momentum is building, although the year to date share price return is down 7.5% and the 1-year total shareholder return has declined 7.0%.
Capitalize on the renewed interest in Hershey by scanning a hand picked 33 high quality undervalued stocks that also show solid balance sheets and consistent cash generation.The recent jump in Hershey may signal confidence in its earnings power, or it may just reflect short term enthusiasm ahead of results. The valuation will show which story carries more weight.
Most Popular Narrative: 113% Overvalued
On Esteban's numbers, Hershey's last close at $168.68 sits far above a narrative fair value of $79.25, which frames today's rally as rich rather than cheap.
A fortress brand and scale position in U.S. confectionery (Reese’s, Hershey’s, Kisses) generates ~23% through-cycle ROIC and exceptionally durable free cash flow that fell only ~13% even in the worst input-cost year on record. The 2025 cocoa shock, a ~60% GAAP EPS collapse driven largely by non-cash hedge mark-to-market, obscured an underlying cash engine that remained intact.
See why 7 investors see Hershey as 113% overvalued.
Result: Fair Value of $79.25 (OVERVALUED)
Still, that fortress Hershey story could crack if cocoa costs stay elevated longer than expected, or if GLP-1 driven appetite changes hit confectionery demand harder.
Find out about the key risks to this Hershey narrative.
Another View: Hershey Through The DCF Lens
Esteban’s narrative flags Hershey as rich against a $79.25 fair value, yet the SWS DCF model points in the opposite direction. On that cash flow view, Hershey at $168.68 trades around 43% below an estimated value of $296.07, which frames today’s price as a potential discount rather than excess. Which story do you trust more: the earnings narrative or the cash engine?
Look into how the Look into how the SWS DCF model arrives at its fair value.
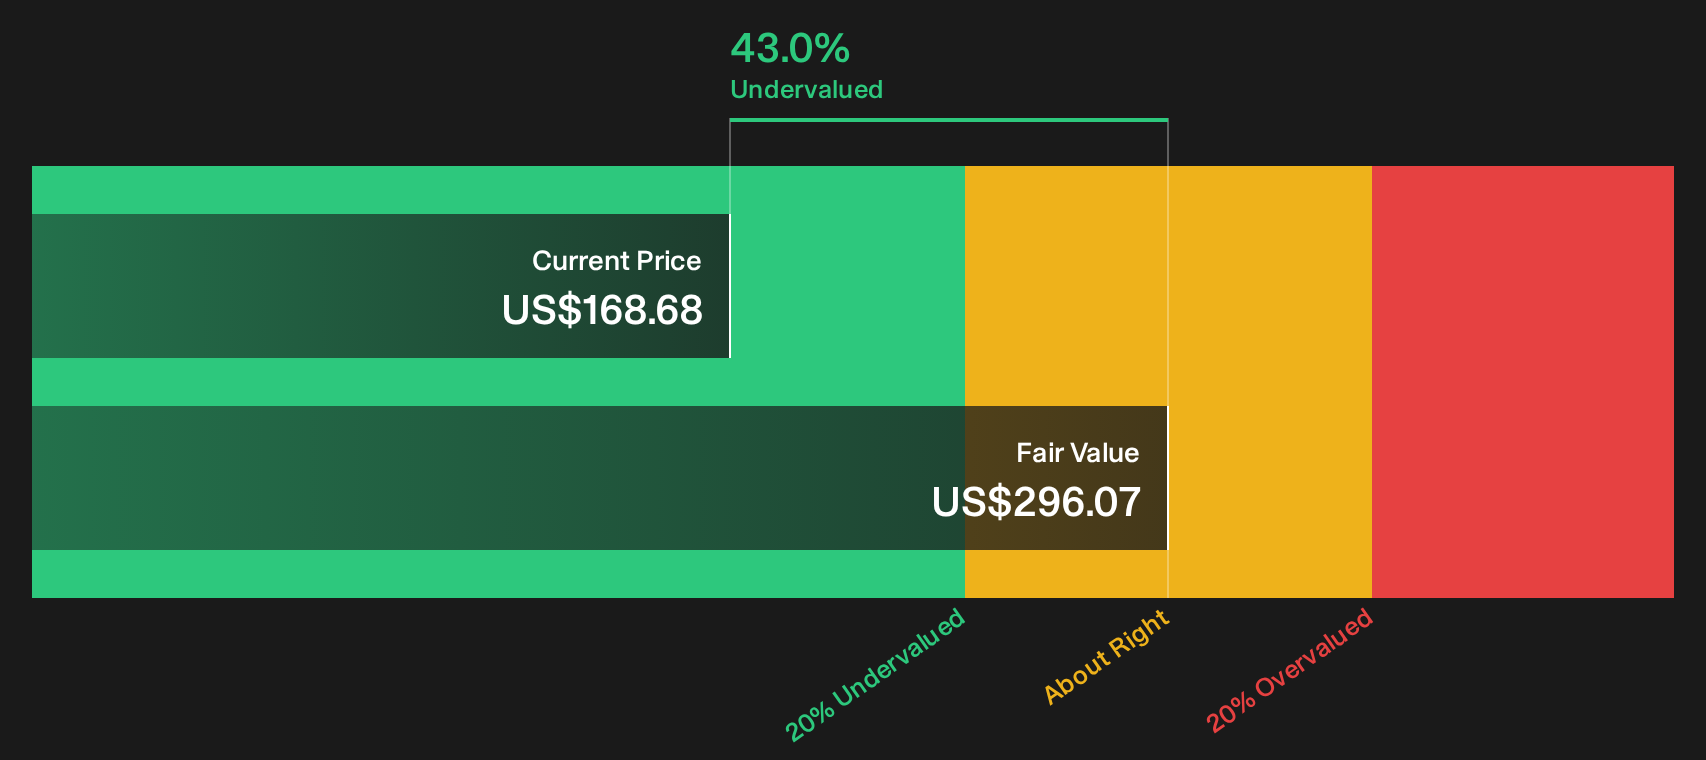
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hershey for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Hershey is clearly divided, with both concern and optimism in the mix. Review the numbers quickly and form your own stance with 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Hershey?
If Hershey has you thinking harder about price versus value, do not stop here. Broader opportunity often shows up first in the wider watchlist, not a single ticker.
- Target potential upside by scanning a hand picked 20 high quality undiscovered gems with strong fundamentals that many investors may still be overlooking.
- Prioritize resilience and sleep better at night by checking a focused 32 resilient stocks with low risk scores built around companies with more stable risk profiles.
- Hunt for quality at a discount by reviewing a curated list of solid balance sheet and fundamentals (25 results) that combines financial strength with cleaner balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com