
Will Lower Gold Guidance Change Buenaventura Stock's Narrative
- Compañía de Minas Buenaventura reported third quarter 2026 production figures and updated full year guidance across gold, silver, lead, zinc and copper, including a revised gold outlook linked to San Gabriel's processing constraints and ramp up schedule.
- The revised 2026 gold production guidance highlights how temporary limitations at San Gabriel's tailings filtration system can influence Buenaventura's broader multi metal production mix and operating plans.
- We will look at how Compañía de Minas Buenaventura's investment narrative is shaped by revised 2026 gold guidance linked to San Gabriel.
Compañía de Minas BuenaventuraA Investment Narrative Recap
To own Compañía de Minas BuenaventuraA, you need to believe the multi metal portfolio can offset project hiccups and still convert its asset base into consistent cash generation. The updated 2026 guidance keeps silver, lead, zinc and copper in defined ranges, which helps frame expectations, while the trimmed gold outlook reflects a practical response to San Gabriel’s processing constraints.
The key near term swing factor remains execution at San Gabriel, where tailings filtration limits and a revised ramp up schedule now cap how quickly gold volumes can build. The biggest operational risk is that high capex and rising cost pressures across the portfolio dilute the benefit of those volumes if project timing or spending drifts.
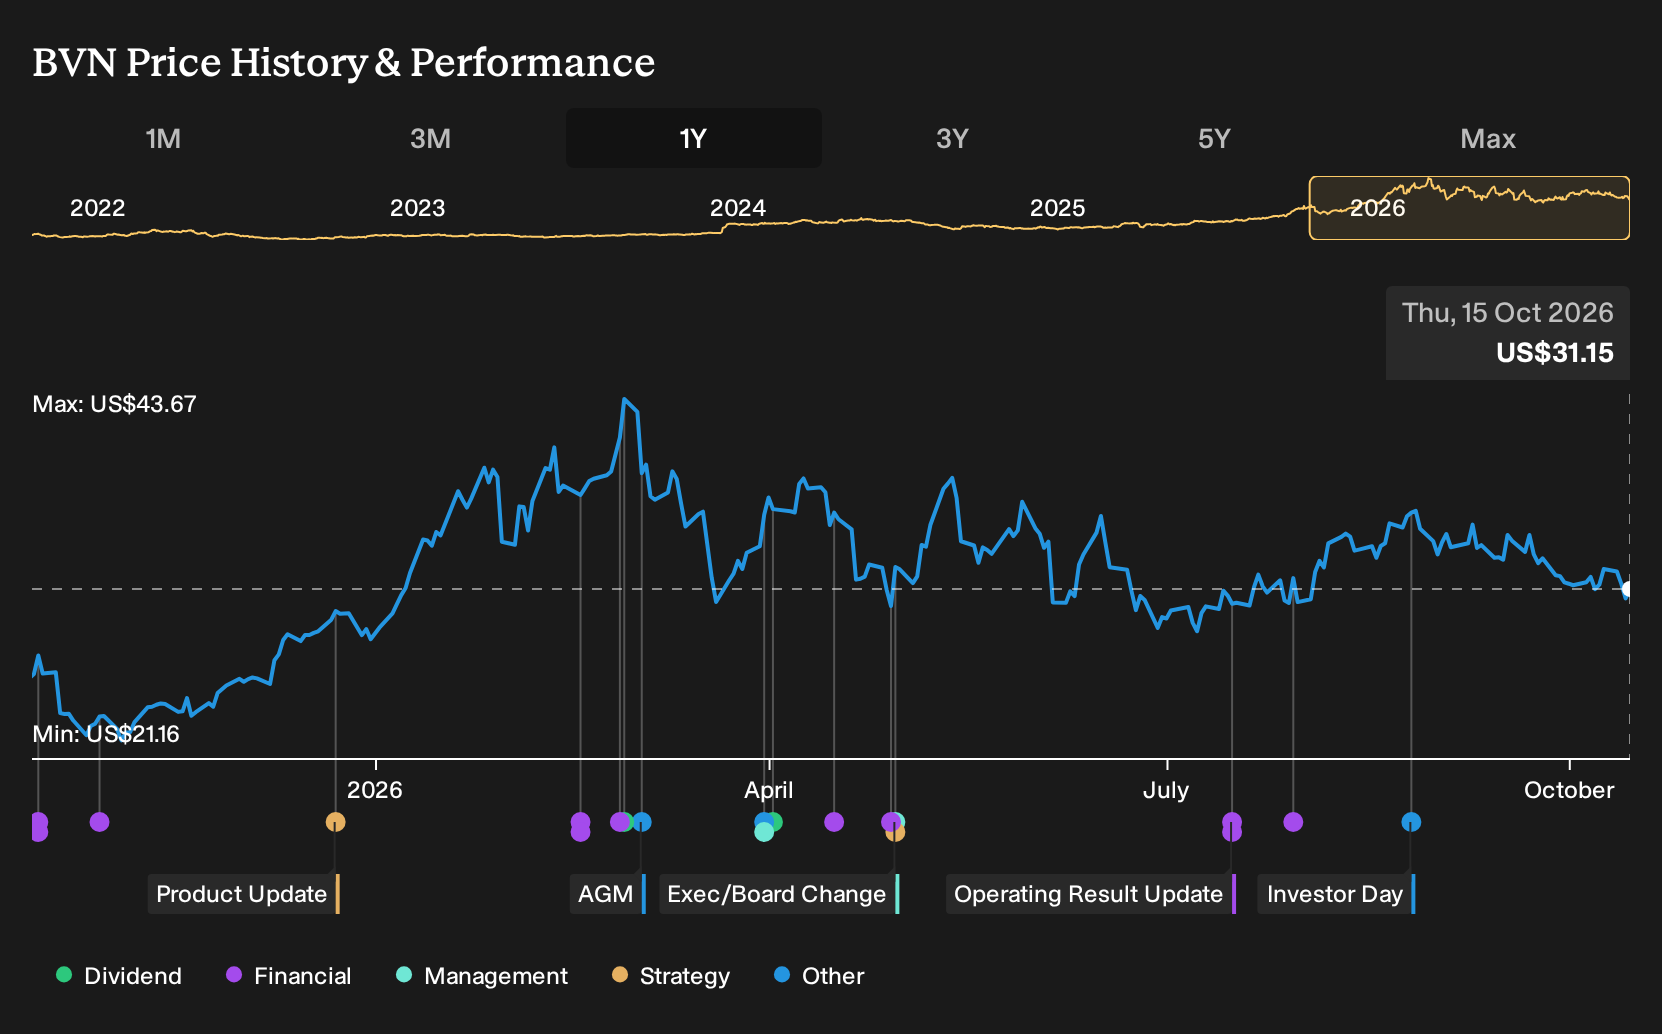
The new 2026 production guidance announced on 15 October sits at the center of this story. Management now expects total gold output of 142,300 to 164,500 ounces and has laid out similarly tight ranges for silver, base metals and copper, giving you a clearer frame for what the current asset base is set up to deliver.
Quarter to date production numbers show 112,437 ounces of gold and 10.5 million ounces of silver for the first nine months of 2026, which anchors how much room remains in the guidance bands. For a catalyst focused view, the guidance reset turns San Gabriel’s ramp and the company’s ability to contain inflation driven costs into the main things to watch through the next few quarters.
What The Current Forecasts Assume For Compañía de Minas BuenaventuraA
Analysts sketch a relatively modest path for Compañía de Minas BuenaventuraA, with revenue expected to grow at 1.7% a year and earnings projected to move from US$1.1b today to US$993.2m by 2029. That change implies an earnings decline of about US$106.8m against the current base, even as forecasts point to 2029 revenue of US$2.3b and a P/E multiple of 13.2x on those projected profits.
Compañía de Minas BuenaventuraA's narrative projects US$2.3b revenue and US$993.2m earnings by 2029. This requires 1.7% yearly revenue growth and about US$106.8m earnings decrease from US$1.1b today.
Uncover why Compañía de Minas BuenaventuraA's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest analysts focus on San Gabriel’s commissioning risk rather than its potential. They worry that any further holdup in energization or filtered tailings ramp could keep earnings closer to about US$1.0b on roughly US$2.2b revenue by 2029. Those views pre date this guidance reset, so you may want to compare several opinions and decide which story feels more reasonable to you.
Explore 2 other Compañía de Minas BuenaventuraA fair value estimates, including one that suggests as much as 43% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Compañía de Minas BuenaventuraA research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Compañía de Minas BuenaventuraA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Compañía de Minas BuenaventuraA's overall financial health at a glance.
Looking For More Investment Ideas Beyond Compañía de Minas BuenaventuraA?
If Compañía de Minas BuenaventuraA's guidance reset has you thinking about position sizing and diversification, it can help to line it up against other potential holdings that fit different roles in your portfolio.
- For investors hunting for overlooked opportunities with room to prove themselves, consider scanning a 20 high quality undiscovered gems that pair strong fundamentals with limited current attention.
- If capital preservation and steadier profiles matter more to you than rapid swings, filter for 32 resilient stocks with low risk scores that score well on resilience metrics and risk checks.
- Those who care most about financial strength and flexibility can review a list of solid balance sheet and fundamentals (25 results) to find businesses with cleaner leverage and supportive fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com