
Castle Biosciences (CSTL) Could Be 23% Below Fair Value As TissueCypher Data Draws Focus
Castle Biosciences (CSTL) is back in focus after the company highlighted new TissueCypher Barrett's esophagus data and conference presentations ahead of its upcoming third quarter 2026 results webcast on November 5.
The share price at US$33.80 reflects a mixed year, with a 39.9% 90 day share price return but a share price return that is down 12.3% year to date. The 1 year total shareholder return of 50% points to momentum building over a longer horizon as TissueCypher data and the upcoming November earnings webcast keep Castle Biosciences in the spotlight.
Spot emerging momentum stories around Castle Biosciences by scanning a curated set of healthcare-focused opportunities using our 34 healthcare AI stocks.The recent jump in Castle Biosciences appears tied to fresh TissueCypher data and conference visibility, rather than only to changing sentiment. How fully does the current share price already reflect that story?
Most Popular Narrative: 23% Undervalued
Based on the most followed narrative, Castle Biosciences is framed with a fair value of $44.00 against the latest close at $33.80, putting the TissueCypher progress and broader test portfolio at the center of the investment case.
Castle's rapid expansion of its test menu, especially into high-growth, underpenetrated indications like gastrointestinal diagnostics (TissueCypher) and new pipeline areas such as atopic dermatitis, positions the company to tap into substantially larger patient populations and diversify revenue streams, directly supporting long-term revenue growth.
The ongoing shift toward precision and individualized medicine across healthcare systems, combined with Castle's robust real-world evidence (for example, the NCI SEER study showing a 32% reduction in melanoma mortality), sets the stage for broader clinical adoption and increased commercial and payer demand, likely boosting test volumes and supporting higher revenues.
See why 4 investors see Castle Biosciences as 23% undervalued.
Result: Fair Value of $44.00 (UNDERVALUED)
Still, if the DecisionDx-SCC reimbursement reconsideration remains unfavorable or payer coverage stalls for key Castle Biosciences assays, that bullish 23% undervaluation narrative could quickly lose traction.
Find out about the key risks to this Castle Biosciences narrative.
Another View: Castle Biosciences Looks Expensive On Sales
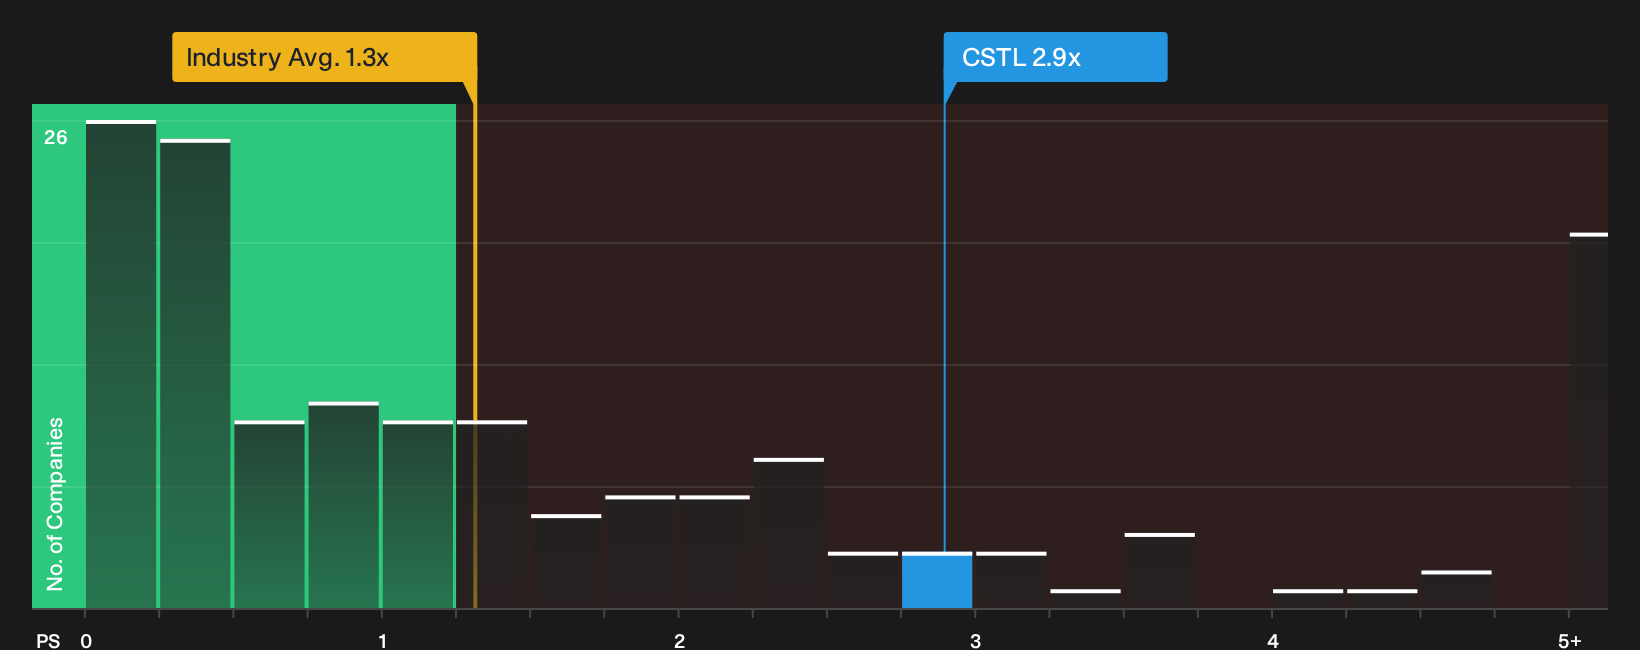
The SWS DCF model paints Castle Biosciences as undervalued at $33.80, yet the simple sales multiple sends a different signal. CSTL trades on a P/S of 2.9x, compared with 1.3x for the wider US Healthcare group and 1x for peers, while the fair ratio sits at 3.1x. That gap hints at a higher bar for execution. Which story do you trust more when earnings are still in the red?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Castle Biosciences do not have to leave you on the fence. Step into the data, weigh both sides, and then act on the full picture using our 3 key rewards and 1 important warning sign.
Looking for more Castle Biosciences investment ideas?
Do not stop with one ticker. Use the Simply Wall Street Screener to uncover fresh angles on quality, risk and income before the market moves past you.
- Target resilient cash generators that still trade at low expectations by scanning our 33 high quality undervalued stocks.
- Protect your downside first by filtering for businesses with strong finances using the list of solid balance sheet and fundamentals (25 results).
- Stack potential income streams on top of growth stories by zeroing in on 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com