
Baycurrent (TSE:6532) Stock Can Q2 Earnings Sustain Premium Growth
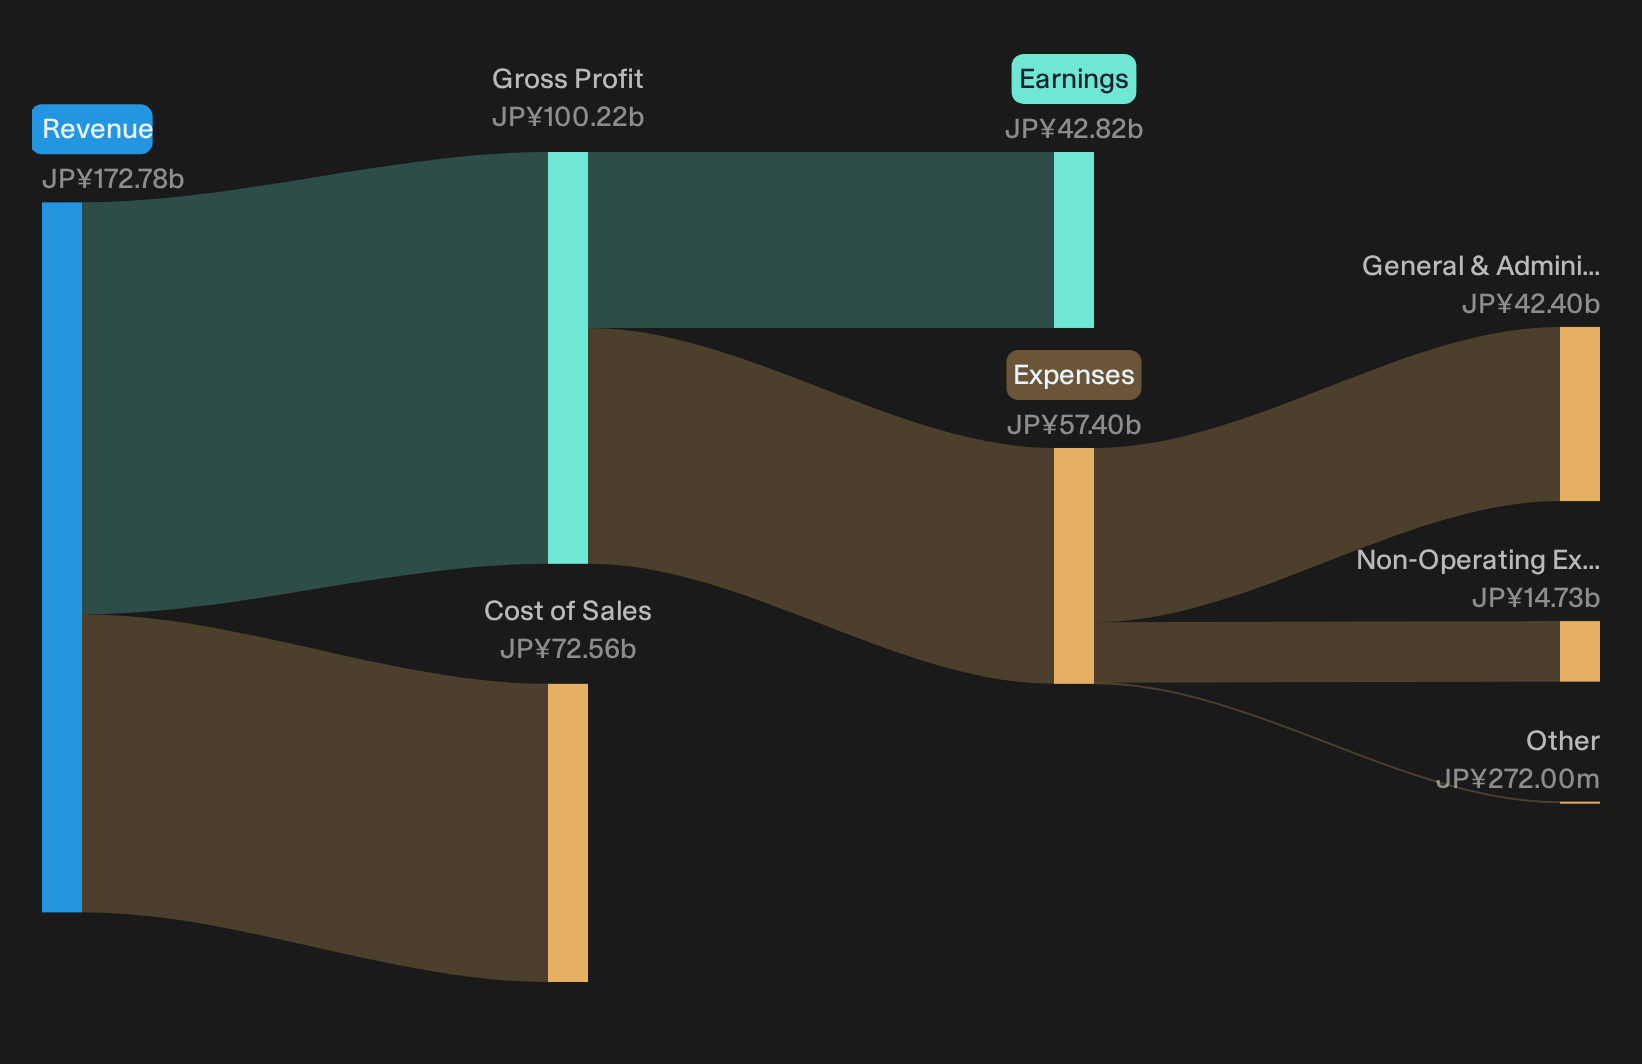
Baycurrent walked into this Q2 2027 print with its stock at ¥10,195 and a reputation for fast growth, a rich 35.2x P/E and punchy expectations already baked in. The fresh quarter delivered higher revenue at ¥48,337m and basic earnings per share of ¥77.71, reinforcing a solid profitability story even as the trailing net margin of 24.8% sits below last year’s 26.5%. The short term price reaction now hinges on whether traders focus on that premium valuation or on a business still producing hefty earnings power.
Love Baycurrent's rich earnings profile but questioning whether that 35.2x P/E leaves enough cushion? Compare it with stocks screened for solid fundamentals and stronger balance sheets in our list of solid balance sheet and fundamentals stocks (21 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥48,337m vs. ¥34,155m (up about 41.5%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥11,476m vs. ¥8,213m (up about 39.7%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥77.71 vs. ¥54.12 (up about 43.6%)
- Trailing Net Margin (latest vs. prior year): 24.8% vs. 26.5% (margin has softened year on year)
Ask Charlie what Baycurrent’s rich P/E multiple really signals.
Baycurrent’s growth story still has real backing
For anyone leaning positive on Baycurrent, the revenue and earnings line both move in the right direction. Top line expanded sharply year on year while net income and basic EPS tracked a similar path, which suggests consulting demand and project mix are still working in the company’s favour. Profitability has eased a little, with the latest trailing net margin at 24.8% compared with 26.5%, yet the absolute level remains high. That combination of strong sales momentum and still healthy returns supports a constructive view on the underlying business model.
Profit pressure keeps the cautious case alive
There is still a bear story to tell around Baycurrent. The slip in trailing net margin from 26.5% to 24.8% hints at rising costs or pricing pressure in a people heavy consulting model. If wage inflation, hiring competition or more complex delivery work are behind that move, earnings quality could matter more than headline growth. Rapid revenue expansion can strain staffing and project control, which raises questions about how repeatable this quarter’s strength is without further margin erosion. Short term traders who worry about execution risk will not dismiss that shift lightly.
After a margin wobble like this, the real question is whether execution strain or pricing pressure is just starting to show. Review the full risk analysis for Baycurrent which shows 1 important warning signHunt For Mispriced Earnings Power
Baycurrent just reminded you that execution and market expectations can diverge meaningfully. The real opportunity is stocks that could be undervalued before attention converges on their underlying earnings power.
- Company 1 - 18% below our estimate - helps enterprises standardize form design as usage deepens in cloud-focused document workflows.
- Company 2 - 34% below our estimate - sells low-code groupware that keeps rapidly expanding team workflows aligned when scattered tools fall short.
- Company 3 - 35% below our estimate - handles complex public infrastructure and property projects as mandates shift toward recurring maintenance and management.
Three companies from the same screener. Open every one of the 14 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com