
Thales (ENXTPA:HO) Following Singapore Leadership Change, Is The Valuation Story Still Intact?
Thales (ENXTPA:HO) just refreshed its leadership bench in Asia by appointing Derek Cheng as Country Director for Thales Singapore. This move highlights how investors might think about its regional operations.
Recent trading has been choppy. Thales shares have climbed 5.56% over the past week but are still down 5.09% on a 1 month share price return and 3.11% on a year to date share price return. The 1 year total shareholder return is down 8.67% yet remains supported by very large 3 year and 5 year total shareholder returns, indicating that momentum has cooled in the short term even as the longer record stays intact.
Scan for other companies that combine defence, aerospace and digital identity exposure by checking the hand picked 195 high quality undervalued stocks, which may appeal if Thales is already on your radar.
Short term momentum around Thales and the fresh Singapore leadership raise a practical question for investors. Is it worth paying today’s price, or does the math suggest patience for a better entry point ahead?
Most Popular Narrative: 23% Undervalued
On the most followed view of Thales, a fair value of about €295 sits above the latest close at €227.70. This frames today’s discussion around whether the current discount lines up with the longer term earnings story behind the stock.
Heightened innovation and R&D in next-generation technologies (AI, secure communications, space tech, digitization), along with cross-business synergies from acquisitions, position Thales to remain a market leader amid secular shifts toward digital transformation in security, favorably impacting long-term revenue growth and margin resilience.
See why 103 investors see Thales as 23% undervalued.
The fair value in that narrative, at about €295 per share, is built using a discount rate of 7.63% applied to analysts’ long term cash flow and earnings assumptions. That figure compares to the current share price of €227.70, which implies a discount of roughly 23% to the narrative’s estimate of worth.
Analysts contributing to this framework expect revenue growth of around 8.8% per year and an eventual profit margin near 8.8%. Those inputs flow into a future earnings profile that is then discounted back at 7.63% to arrive at the present value, effectively asking what investors are willing to pay today for that projected earnings stream.
This approach ties closely to how Thales is positioned across defence, aerospace and cyber security. Forecasts assume that higher earnings growth than the wider French market, and a return on equity projected at 21.1% in three years, can support that fair value without stretching the narrative’s required rate of return.
At the same time, the thesis is not one sided. The popular narrative explicitly factors in execution risks in Cyber & Digital, the one off €613.7m loss that affected the last twelve months, exposure to government defence budgets and restructuring in Space. The 7.63% discount rate aims to compensate for those uncertainties rather than ignoring them.
For readers, the key cross check is simple. If the assumptions around 8% revenue growth, mid to high single digit margins and the risk profile captured by that 7.63% discount rate feel reasonable, then the gap between €227.70 and about €295 reflects the room that narrative sees for sentiment or fundamentals to catch up.
Result: Fair Value of €295 (UNDERVALUED)
Still, the storyline can crack if cyber execution remains patchy, or if reliance on large European defence budgets leads to delayed orders and more volatile earnings.
Find out about the key risks to this Thales narrative.
Another View: Thales Through The P/E Lens
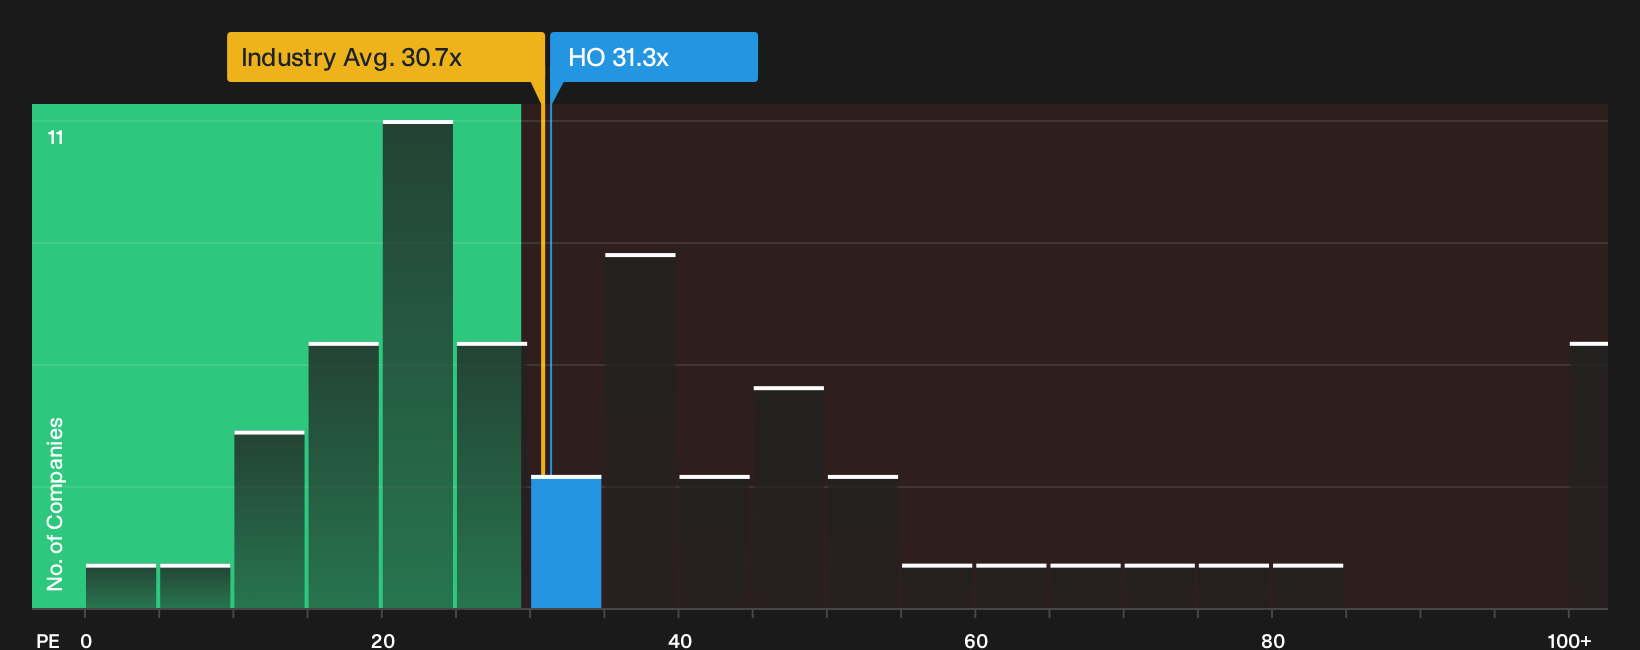
That 23% discount to a roughly €295 fair value tells one story. The P/E picture for Thales tells something different. The current multiple of about 31.3x sits slightly above the European Aerospace & Defense average at 30.7x and well above the fair ratio of 27.8x that the model suggests the market could lean toward over time.
For you, that means the share price already reflects a premium to both the sector and the fair ratio, even as the DCF style narrative points to undervaluation. The gap is not huge but it does narrow the margin of safety. If sentiment cools, does the P/E drift closer to that 27.8x fair ratio before the earnings story catches up?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Thales can be useful if you treat them as a prompt rather than a verdict, so move quickly, interrogate the forecast assumptions yourself, then weigh the balance of 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Thales?
If Thales has your attention, broaden your opportunity set with a few focused tools that surface different types of potential candidates for your watchlist.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (203 results) that combine financial strength with room for a more patient holding period.
- Hunt for mispriced opportunities by reviewing the 617 high quality undiscovered gems that pair quality fundamentals with quieter market attention.
- Prioritise lower volatility by filtering for the 228 resilient stocks with low risk scores that score well on risk metrics while still offering meaningful exposure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com