
What Costain Group Holders Bought Into
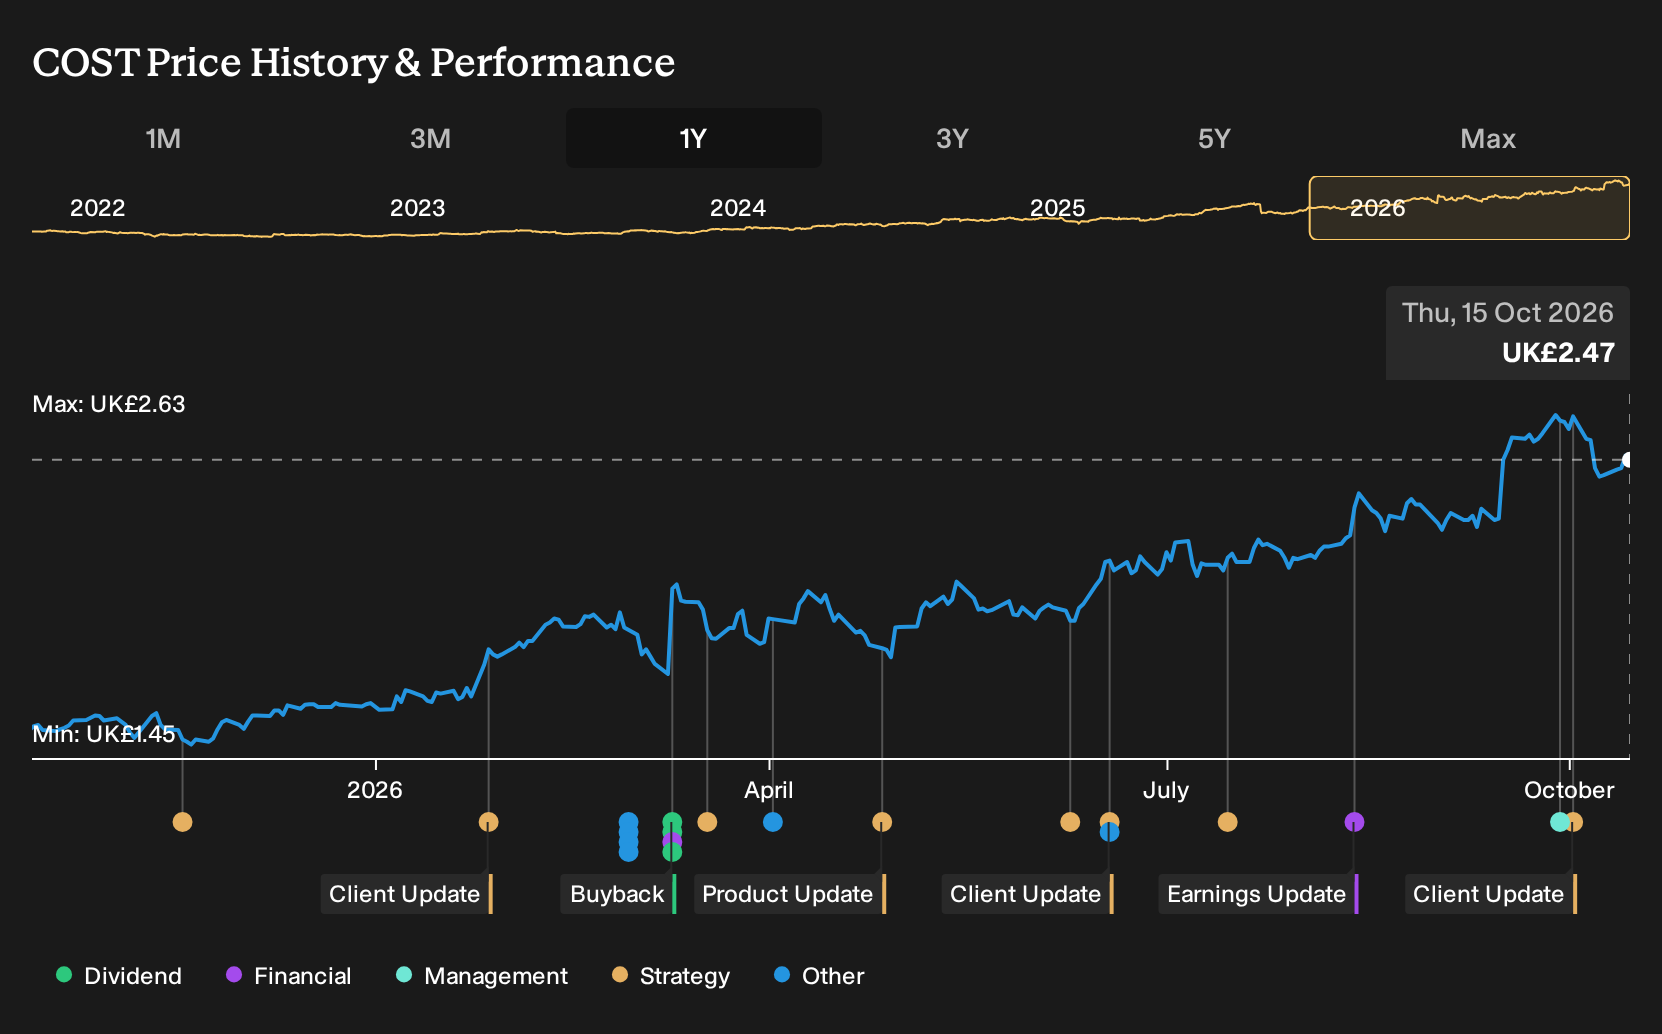
If you only glanced at Costain Group’s latest half year figures, with revenue of £543.1m and net income of £14.9m, the headline might not sound explosive. Holding Costain Group over the past year would have returned 66.5%, including dividends. If you had been weighing up that decision back on 15 October 2025, knowing only the clashing analyst views and contract risks, what would you have focused on?
If the move has made Costain Group harder to judge, start where the gap is still open and scan 9 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Costain Group
The shares cost £1.51 at the start of the period, and Costain Group sat between two very different stories about what might come next.
On the upbeat side, one narrative pointed to heavy UK infrastructure and decarbonisation spending, with a Fair Value of £1.82 that reflected assumptions of 8.1% annual revenue growth and profit margins rising to 3.3%.
The cautious view centred on rising regulatory and labour costs, plus fixed price contracts, with a Fair Value of £1.15 built on slower 3.3% revenue growth and a future P/E assumption of 8.1x.
What The Results Changed For Costain Group
The half year to H1 2026 gave Costain Group slightly higher revenue of £543.1m against £525.4m in H1 2025 and a small lift in net income to £14.9m from £14.2m. Net margin stayed at 2.7%. That combination supported the cautious case on profitability, since the hoped for step up in earnings quality was not yet visible in the numbers.
The key issue here was margin expansion. When you see a story built on higher quality work and better pricing, check whether net margin is actually moving rather than relying only on revenue or order book headlines.
What Costain Group's Run Up Already Assumes
With Costain Group now trading at £2.46, the selected Narrative’s Fair Value sits below the current price and treats the recent 66.5% gain over the past year as front loaded optimism about what comes next.
On that view, a buyer today is effectively backing multi year delivery at around or above 4% operating margins. The key question is how the execution and cost risk across those long contracts might affect that assumption.
"The main thing that has to go right is that Costain Group turns its record £7b forward work and growing positions in water, energy, nuclear and aviation into delivery at or above the guided 4% operating margin while keeping contract risk tightly controlled."
One Narrative disagrees with today's price. → See where this Narrative says Costain Group should trade
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 17% below our estimate - targets everyday supplement use as gyms and wellness habits become more routine.
- Company 2 - 28% below our estimate - scales a single tech platform so rising investment flows spread over largely fixed costs.
- Company 3 - 24% below our estimate - attracts senior lawyers leaving partnerships for a higher share of client fees.
Those are three of them. See all 9 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com