
Will Heavy Crude Advantage Change Valero Stock Narrative
- Valero Energy is benefiting from tight global refining capacity, resilient fuel demand and access to discounted heavy sour crude that supports refinery economics and operating flexibility across its 14 plant network.
- Recent commentary around improved renewable diesel and ethanol profitability, along with very low net debt and active buybacks, highlights a business model that leans heavily on efficient capital use and diversified fuel earnings streams.
- The focus is now on how Valero Energy’s heavy crude sourcing advantage could reshape the existing investment narrative around refining strength.
Scan beyond Valero Energy to see how other refiners and energy players compare on heavy-crude economics, balance sheets and earnings momentum with our curated list of solid balance sheet and fundamentals (25 results)
Valero Energy Investment Narrative Recap
To own Valero Energy you need to be comfortable with a refining heavy story that leans on tight global capacity, strong crack spreads and access to discounted heavy sour barrels. The key near term swing factor is how well refinery margins hold up as product inventories evolve. The recent analyst target upgrades do not change that core operating equation.
The biggest near term risk sits in execution and mix. A setback in renewable diesel or ethanol profitability, or a jump in unplanned maintenance costs, could pull earnings away from what tight refining markets imply. In contrast, the upcoming October 22 earnings report is the clearest near term test of how those pieces are actually tracking.
The most relevant datapoint right now is the expectation for higher year on year earnings and revenue in the September 2026 quarter. That puts hard numbers around the story of healthy refining conditions, better renewable diesel economics and more efficient use of heavy sour crude in Valero Energy’s system.
If that earnings release lands close to those expectations, it would reinforce the idea that tight capacity, renewable diesel improvement and ethanol tax credits are flowing through the income statement. A weaker print or softer guidance would push investors to focus more on risks like forecast earnings declines, potential asset impairments and higher sustaining capital needs at refineries such as Port Arthur.
Valero Energy’s current analyst framework points to revenues of US$116.1b and earnings of US$7.0b by 2029. This outlook is built on a forecast yearly revenue decline of 4.3% and an earnings decrease of US$0.2b from today’s US$7.2b profit base.
Uncover why Valero Energy's fair value indicates a 10% potential downside to its current price, a premium that may not hold.
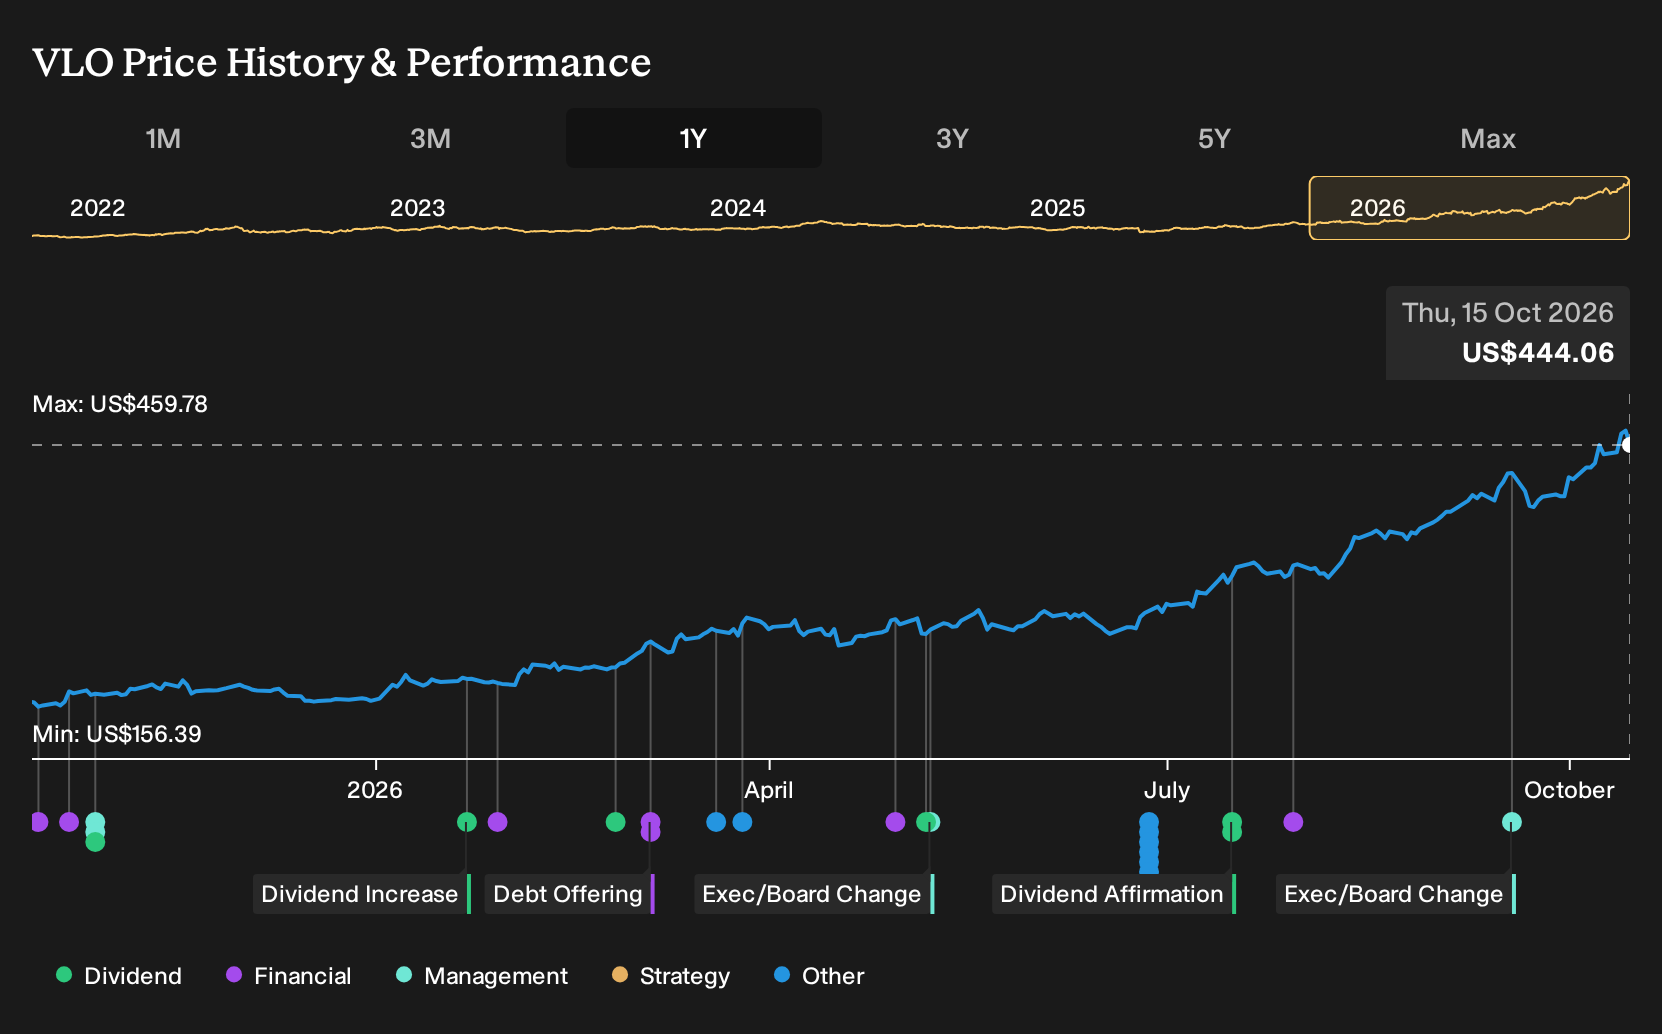
Exploring Other Perspectives
One alternate take on Valero Energy leans hard into the heavy crude catalyst. The most optimistic analysts were pencilling in flat revenue near US$134.6b and earnings of US$10.4b by 2029 before this week’s price target jump. That is far above consensus, and the latest news could pull those narratives in very different directions.
Explore 3 other Valero Energy fair value estimates, including one that suggests up to 5% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Valero Energy research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Valero Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Valero Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Valero Energy?
Once you have a view on Valero Energy, it can help to line it up against a wider watchlist so you can see which opportunities best match your risk tolerance and income goals.
- If you want potential growth with a higher risk profile, check out 13 elite penny stocks with strong financials that already clear basic financial quality hurdles.
- For investors who care most about paying a fair price for strong fundamentals, consider the 33 high quality undervalued stocks that pair healthier balance sheets with solid cash generation.
- If capital preservation ranks high on your checklist, focus on 32 resilient stocks with low risk scores that score well on stability metrics and business resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com