
Fermi Stock Just Got a Major AMD Catalyst. How to Play FRMI Here.
Fermi (FRMI) is giving investors a fresh reason to revisit its AI infrastructure story after signing a credit support agreement and strategic partnership with Advanced Micro Devices (AMD). The Oct. 13 agreement supports a lease covering 222 megawatts (MW) of gross power capacity for the first phase of Fermi’s Project Matador in Texas and establishes a framework for expanding the partnership to as much as 650 MW.
The deal is significant because AMD’s involvement could help Fermi overcome one of the biggest hurdles facing its ambitious artificial intelligence (AI) data center buildout: securing project financing. Project Matador is designed to provide large-scale, reliable power for AI computing, with Fermi targeting an eventual 17 gigawatts (GW) of capacity. The company has already invested more than $1.5 billion in the project, while its first 222-MW customer lease with TensorWave is expected to generate about $6.5 billion in revenue over 15 years, subject to closing conditions.
Moreover, the AMD partnership strengthens Fermi’s credibility as an emerging AI power play, while the stock remains highly speculative given the financing, construction, and lease-closing risks still ahead. Nevertheless, FRMI shares jumped as much as 14% on Oct. 13 following the announcement. So, is this the catalyst that can put Fermi stock back on investors’ radar, and how should investors play FRMI from here?
About Fermi Stock
Fermi is an energy and AI infrastructure company developing large-scale private electric grids designed to provide reliable, gigawatt-scale power for artificial intelligence and advanced computing. Headquartered in Amarillo, Texas, Fermi is developing Project Matador, a planned AI campus that combines natural-gas generation, nuclear power, utility electricity, solar, and battery storage to support hyperscale data centers. Fermi has a market cap of around $2.2 billion.
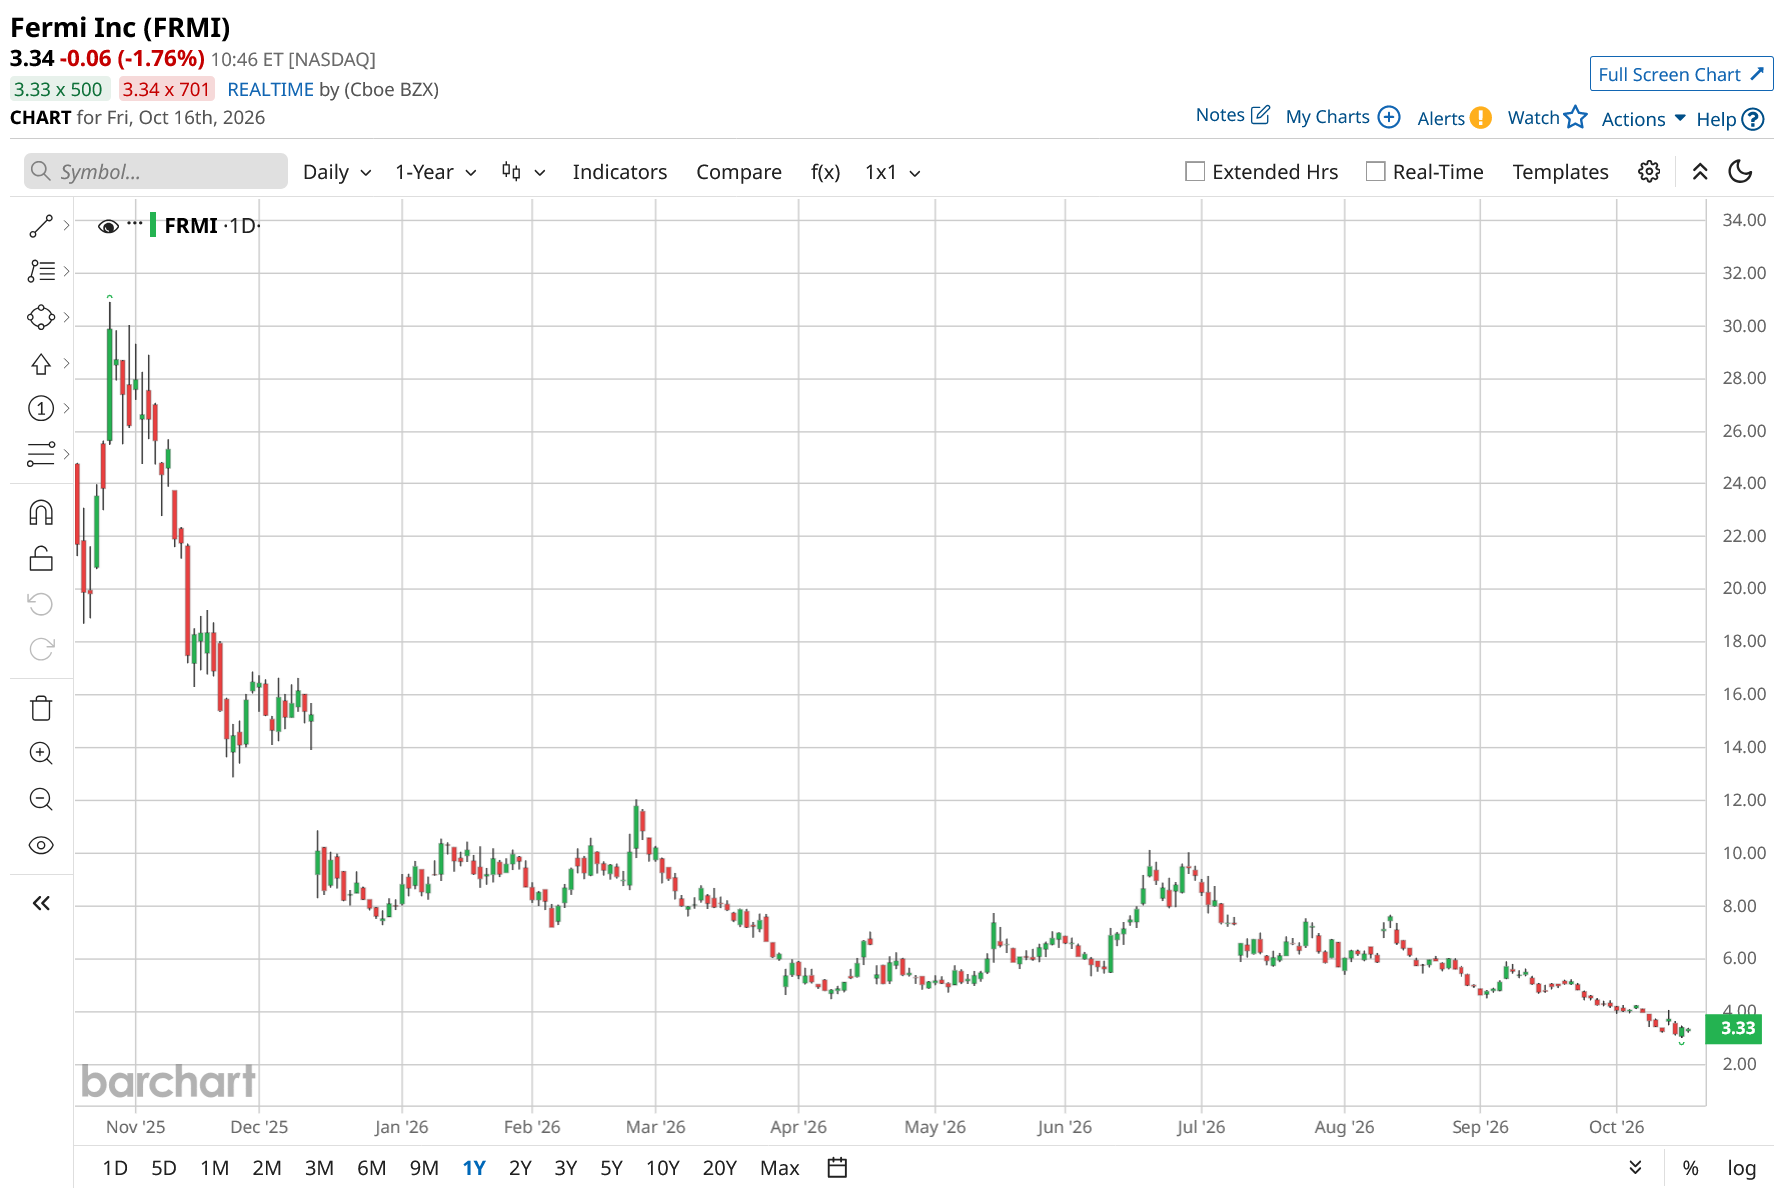
Fermi has been one of the market’s sharpest decliners since going public, with shares down 89% over the past year and 58% year-to-date (YTD). FRMI stock is also still down 2% over the past five trading days despite the recent recovery, underscoring the intense volatility surrounding the AI infrastructure developer.
Fermi completed its IPO in October 2025, selling 32.5 million shares at $21 per share. However, since then, investors have struggled to gain confidence in the company’s ambitious Project Matador buildout, which requires substantial upfront capital and carries significant financing, construction, and execution risks. The stock’s decline has been particularly severe as the market reassessed the valuation attached to Fermi’s long-term AI data center ambitions before the company had secured sufficient project financing or generated meaningful operating revenue.
The latest volatility came following the AMD deal. Fermi shares jumped 14.5% on Oct. 13 after AMD agreed to provide credit support for the first 222-MW phase of Project Matador and established a framework to expand the project to as much as 650 MW. However, FRMI stock gave back much of that gain the following session, falling 15.1% to $3.16 on Oct. 14 and again rising 7.4% on Oct. 15.
The stock is currently trading at a price-to-book of 2.01x, which is a premium compared to industry peers.
Fermi’s Bottom Line in the Red
Fermi reported its second-quarter 2026 results on Aug. 13, for the quarter ended June 30. Because Fermi is still in the development stage and pre-revenue, the quarter was driven more by project execution and capital deployment than by traditional operating growth.
Fermi reported a net loss of $25.8 million, or $0.04 per share, compared with a $6.3 million net loss, or $0.02 per share, in the comparable 2025 period. That represents a roughly 310% increase in the quarterly net loss, while the per-share loss doubled year-over-year (YoY). General and administrative expenses rose sharply to $26.8 million from $5.6 million, reflecting the company’s significant expansion as it advances Project Matador.
The deterioration was even more pronounced on a six-month basis. Fermi’s net loss reached $214.5 million in the first six months of 2026, compared with just $6.4 million in the period from inception through June 30, 2025. Its loss from operations totaled $193 million, versus $5.7 million a year earlier. The company also consumed $56 million in operating cash flow during the first six months, compared with $2.6 million in the prior-year period, while net cash used in investing activities surged to $626.2 million from $40.3 million as Fermi accelerated construction and infrastructure spending.
Meanwhile, analysts project a loss per share of $0.33 for fiscal 2026 but an improvement of 193.9% to an EPS of $0.31 in fiscal 2027.
What Do Analysts Expect for FRMI Stock?
On Oct. 13, Texas Capital Securities maintained a “Buy” rating on FRMI stock while setting a $20 price target, citing AMD’s credit support agreement as an important step toward de-risking Project Matador and improving Fermi’s prospects for securing project financing.
Furthermore, Macquarie maintained an “Outperform” rating on Fermi and kept its $15 price target unchanged.
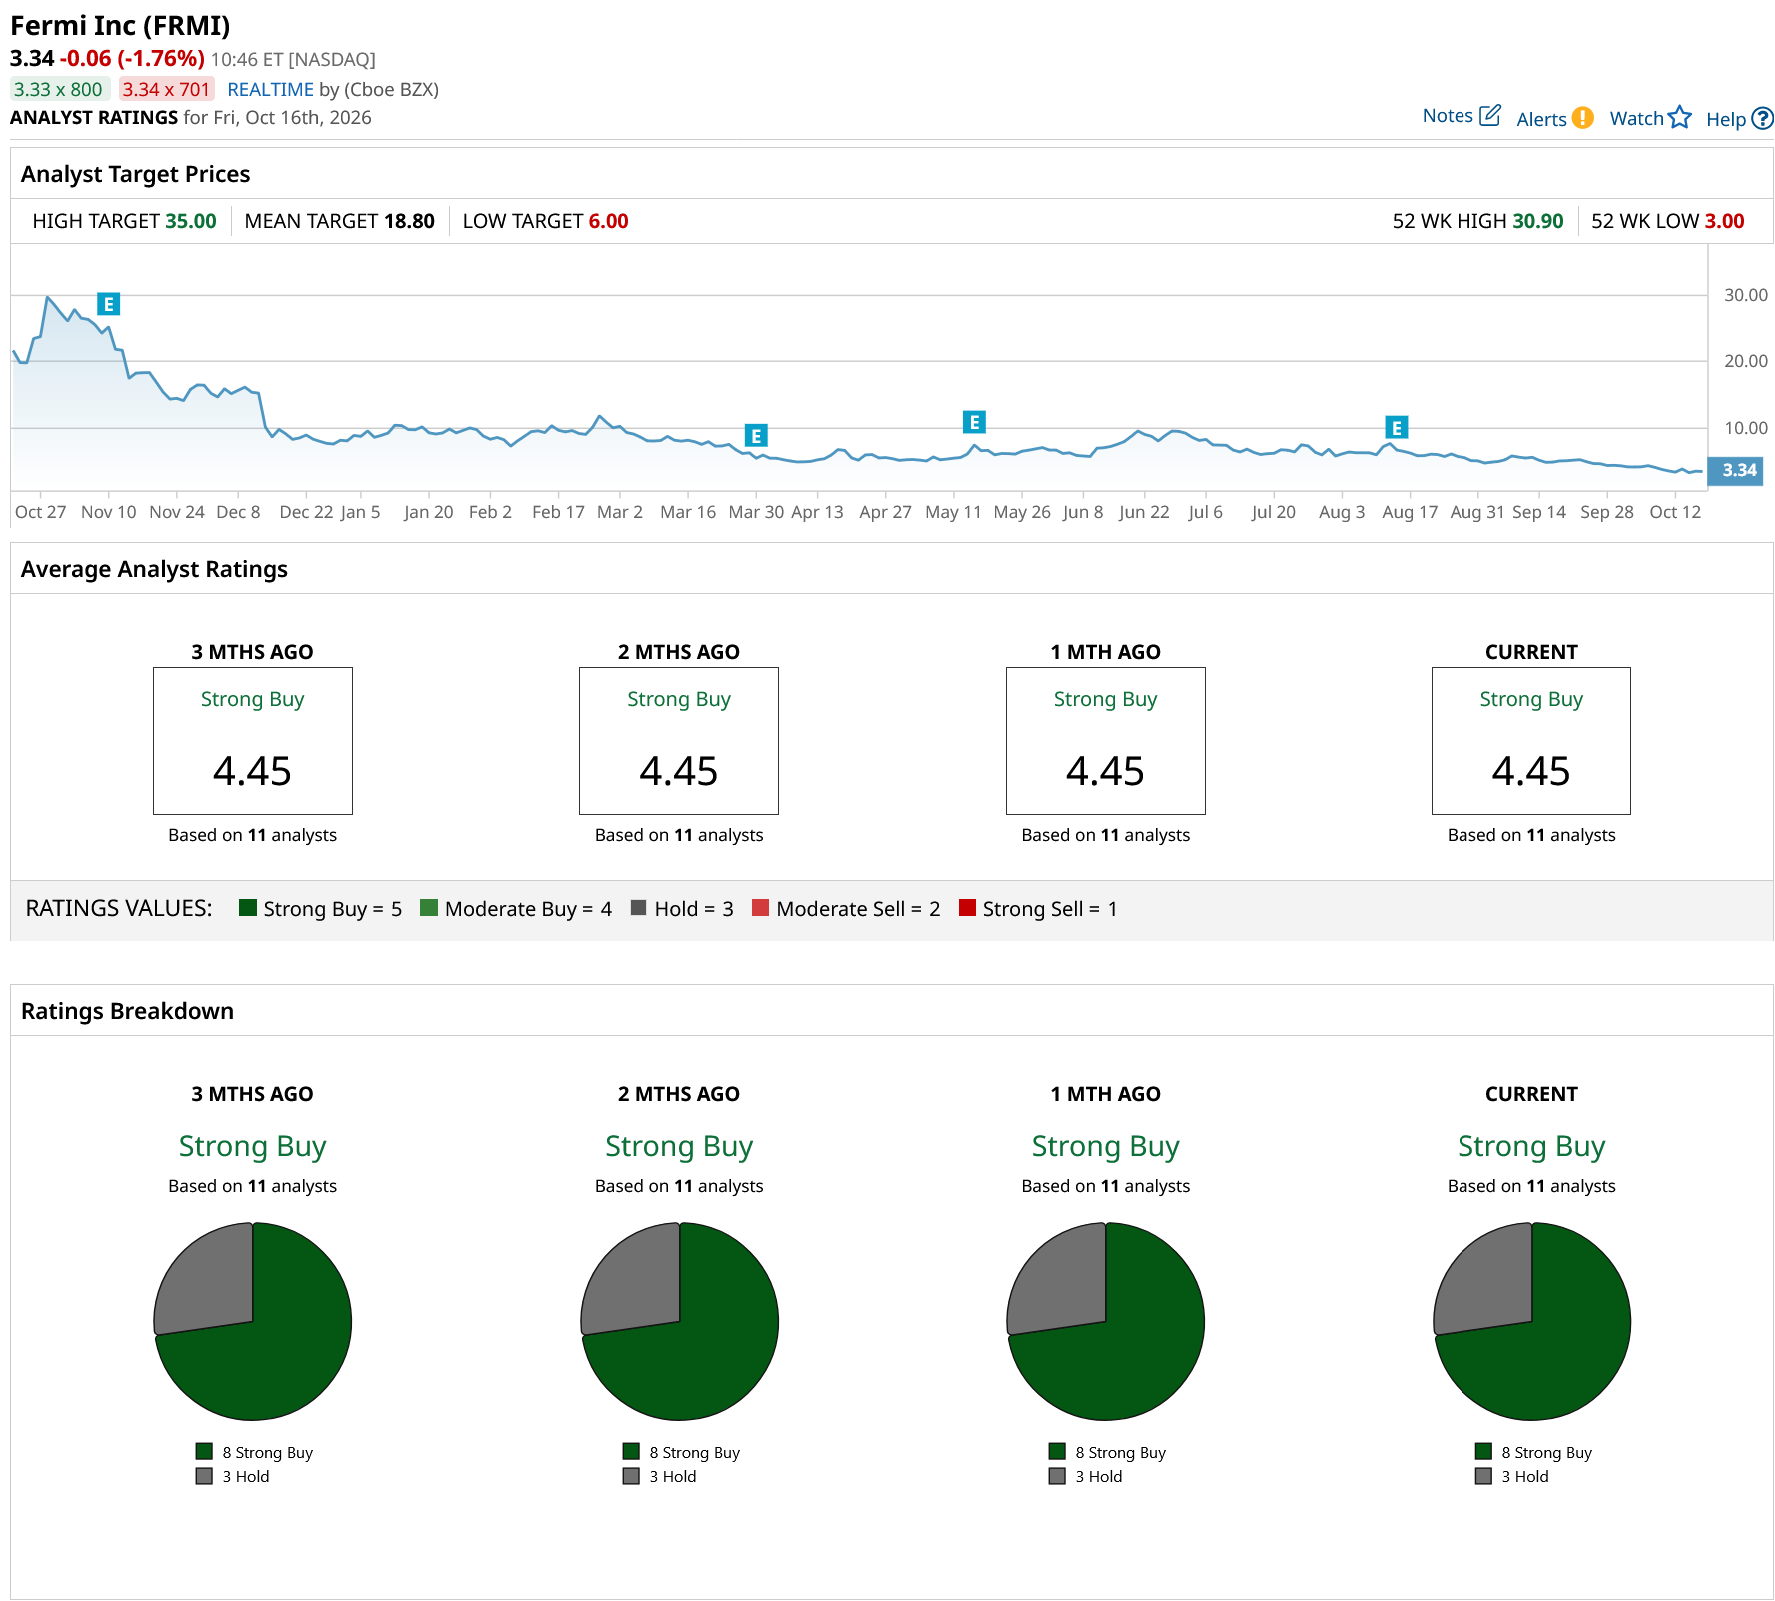
Overall, FRMI has a consensus “Strong Buy” rating. Of the 11 analysts covering the stock, eight advise a “Strong Buy,” and three analysts recommend a “Hold” rating.
The average analyst price target for FRMI stock is $18.80, indicating a potential upside of 463%. The Street-high target price of $35 suggests that the stock could rally as much as 948%.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.