
Lumentum Is Sold Out Through 2029. Wedbush Thinks That Could Be Bullish for GlobalFoundries. Is It?
The broader photonics market is expanding. Fortune Business Insights estimates its value at approximately $1.1 trillion in 2026 and projects a value of $1.9 trillion by 2034, a 6.7% compound annual growth rate (CAGR). Those figures cover applications ranging from displays to healthcare, rather than artificial intelligence (AI) optical connectivity alone.
Within that broader market, Lumentum (LITE) offers a signal of demand. CEO Michael Hurlston recently said that the company's components were sold out through 2029. Hurlston added that Lumentum cannot meet roughly 70% of demand for some products through 2027 and 30% for others through 2028.
Wedbush analyst Matt Bryson called the comments bullish for suppliers and foundries. He named GlobalFoundries (GFS) among the potential beneficiaries in foundry services and silicon photonics.
Could Lumentum’s supply squeeze deliver meaningful earnings growth for GlobalFoundries, or is the opportunity too uncertain to justify buying the stock? Let’s dig in.
The Financials Behind GlobalFoundries
Valued at a market capitalization of $26.8 billion, GlobalFoundries manufactures semiconductors used in electronic devices and communications infrastructure. The company is headquartered in Malta, New York, and serves customers developing technologies for automotive, industrial, mobile, and data-center applications worldwide.
Shares of GFS stock closed at $48.76 on Oct. 15. The stock is up by roughly 40% year-to-date (YTD) and 39% over the past 52 weeks.
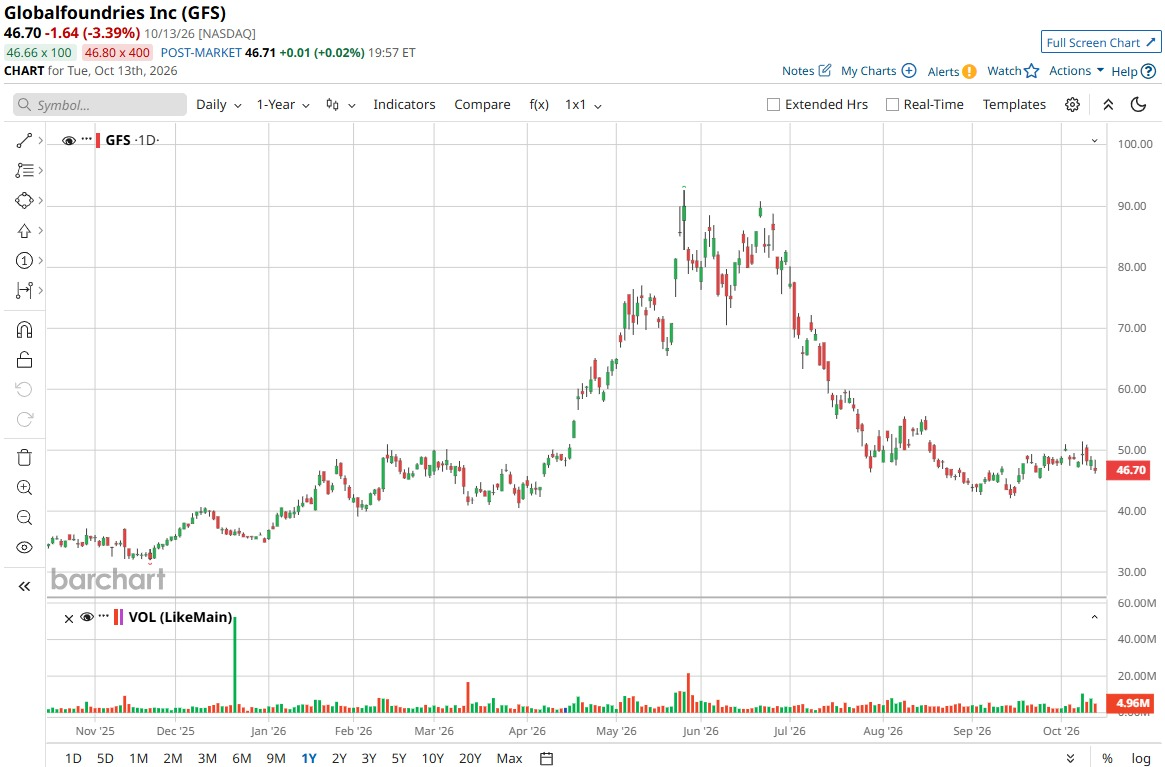
GlobalFoundries released results for the second quarter on Aug. 5. The company generated $1.786 billion in revenue, with a gross margin of 28.3% and an adjusted gross margin of 29.9%. Both revenue and adjusted gross margin exceeded the upper end of management’s guidance, according to CEO Tim Breen.
Operating margin reached 9.7%, or 16.7% after adjustments. Net income totaled $167 million, equivalent to $0.30 per diluted share.
Breen highlighted accelerating customer demand across strategic growth businesses, including optical networking within AI data centers. Wafer shipments increased 8% sequentially to 625,000 on a 300-millimeter equivalent basis, although this companywide figure does not isolate optical demand.
Cash generation was less encouraging. Operating cash flow declined 25% sequentially to $405 million from $542 million, while adjusted free cash flow was -$3 million. Nevertheless, GlobalFoundries ended the quarter with $3.3 billion in cash, cash equivalents, and marketable securities. Alongside that liquidity, the $0.48 annual dividend offers shareholders a modest income component, yielding approximately 1.03%.
GlobalFoundries Expands AI Manufacturing Reach
GlobalFoundries’ expanded Marvell (MRVL) agreement provides concrete support for the optical demand thesis behind Wedbush’s optimism. Announced on Sept. 17, the multiyear deal increases silicon germanium manufacturing capacity at its facility in Burlington, Vermont, building on more than a decade of collaboration.
Its current technology supports 200G per lane, with a roadmap targeting faster generations as bandwidth requirements increase. This agreement is direct evidence of GlobalFoundries’ optical opportunity.
GlobalFoundries also announced an agreement with Taiwan Semiconductor (TSM) on Oct. 8 to manufacture silicon interposers for its advanced packaging ecosystem. The company will add fabrication capacity in Malta, New York, supporting high-performance computing (HPC) and AI systems. The agreement establishes a foundation for further expansion as customer demand grows.
In 2028, GlobalFoundries plans to begin manufacturing its FDX Fusion fully depleted silicon-on-insulator (FD-SOI) platform in Dresden, Germany. The first generation targets 7-nanometer-class digital performance and more than twice the density of first-generation FDX technology.
These developments support Wedbush’s view, particularly the Marvell agreement, which directly expands capacity for optical connectivity. Lumentum’s constraints reinforce the demand signal, but they do not establish additional GlobalFoundries orders. That makes the news encouraging for the business, although the size and timing of any earnings benefit remain uncertain.
Analyst Optimism for GFS Stock
GlobalFoundries’ next earnings release is scheduled for Nov. 4 before the market opens, covering the quarter ended September 2026. Analysts expect earnings of $0.39 per share, compared with $0.34 a year earlier, representing projected growth of 15%.
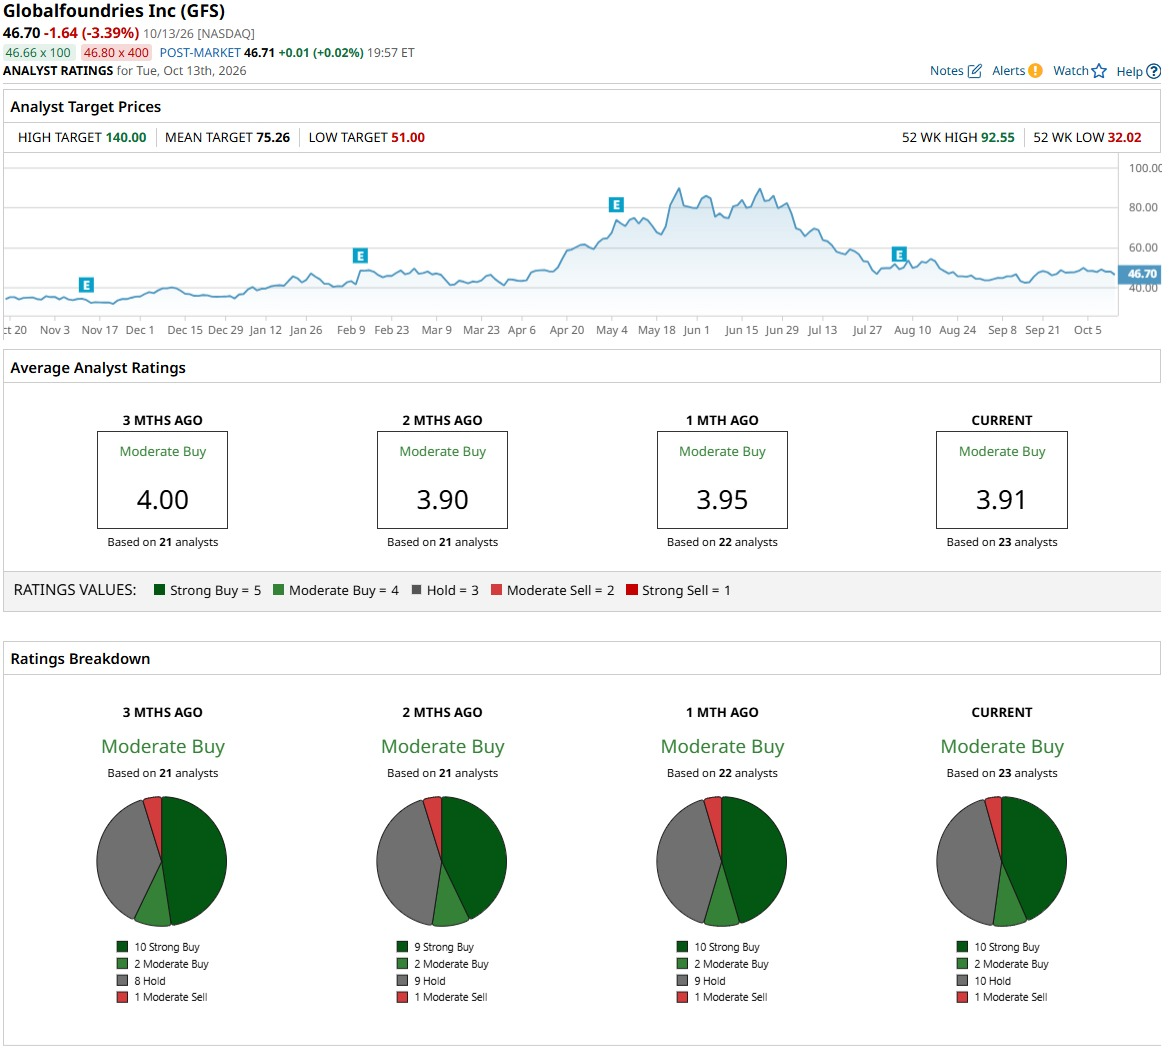
Beyond that quarterly outlook, the consensus among 23 surveyed analysts is a “Moderate Buy” rating for GFS stock. The average price target of $75.26 implies approximately 54% potential upside from current levels.
Conclusion
Lumentum’s capacity squeeze looks bullish for GlobalFoundries, and the Marvell agreement gives that optimism a concrete foundation. Strong optical demand is more likely to support growth than fade quickly, though additional orders and their earnings contribution remain uncertain. GlobalFoundries appears positioned to benefit, but the opportunity still needs to show up in profits and cash flow. The business outlook is encouraging, while the stock’s appeal depends on execution. Wedbush’s argument makes sense without making GFS stock an automatic buy right now.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.