
Easterly Government Properties (DEA) Fell Back, But Is The Development Story A Bargain?
Easterly Government Properties (DEA) has drawn investor attention after recent trading left the stock about 7% lower over the past month and roughly 14% lower over the past 3 months.
Set against a 1-year total shareholder return of 8.1% and a 3-year total shareholder return of 5.7%, the recent 7-day share price decline of 5.3% and 90-day share price fall of 14% suggest that momentum for Easterly Government Properties has been fading rather than building at the current US$21.99 level.
Scan how Easterly Government Properties compares across the wider REIT universe by running the same lens over a curated set of 32 resilient stocks with low risk scores.
Bulls see Easterly Government Properties as a steady government landlord on sale after the pullback, while bears see a value trap. Which case lines up better with the current valuation setup?
Most Popular Narrative: 13% Undervalued
Against the last close of $21.99, the most followed narrative pegs Easterly Government Properties at a fair value of $25.36, with that gap hinging on how well the business turns its pipeline and lending program into durable cash flow.
The active development pipeline that includes the FDLE lab in Fort Myers and the U.S. courthouses in Flagstaff and Medford, with management citing expected yields above 11% and lump sum reimbursement features, provides a path for Easterly Government Properties to add higher margin income and naturally reduce leverage. This development activity would influence both earnings and net interest expense.
See why 11 investors see Easterly Government Properties as 13% undervalued.
Result: Fair Value of $25.36 (UNDERVALUED)
Still, the elevated leverage and high dividend payout leave Easterly Government Properties exposed if funding costs remain challenging or vacancies emerge as agencies reshape their footprints.
Find out about the key risks to this Easterly Government Properties narrative.
Another View On Easterly Government Properties: Multiples Signal A Richer Price
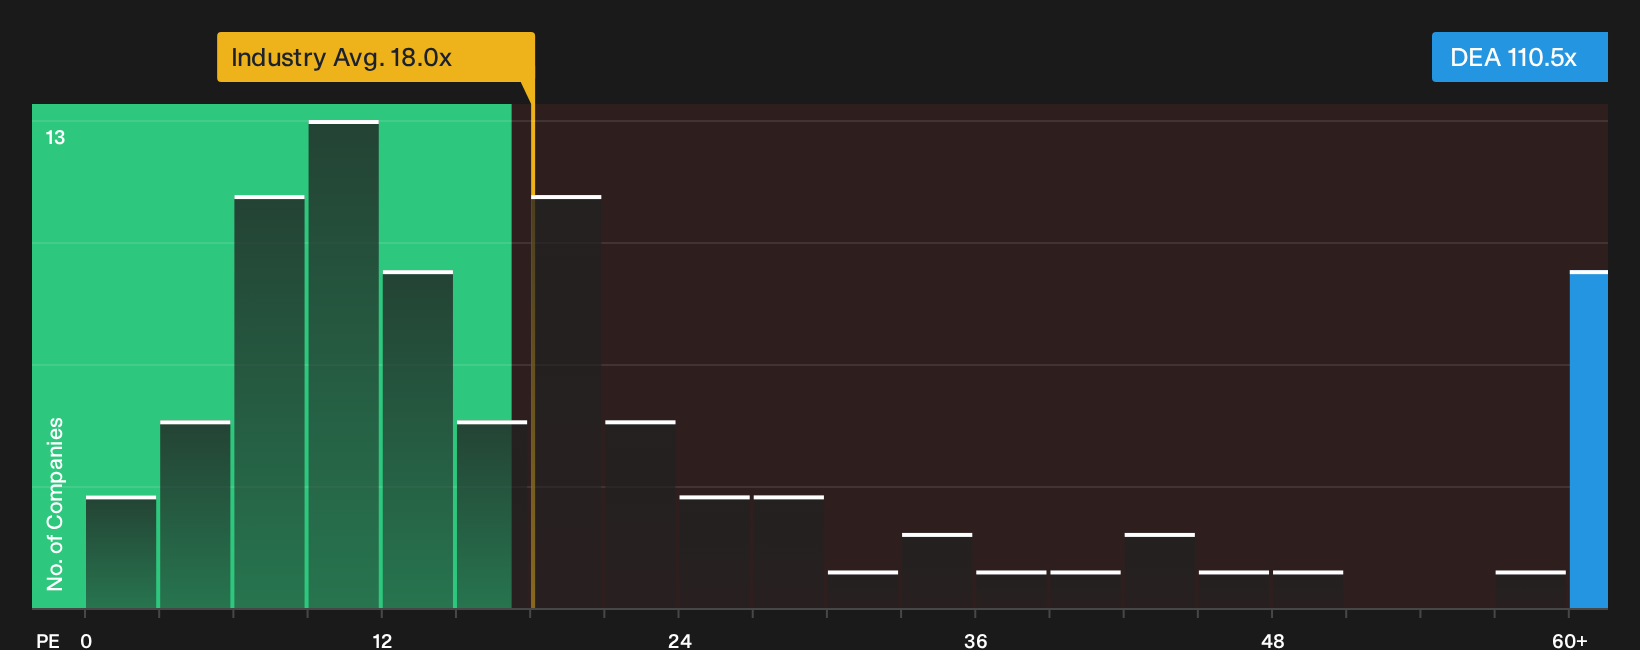
The story changes once you swap fair value models for a plain P/E check. Easterly Government Properties trades on a P/E of 110.5x, compared with a fair ratio of 39.3x and a Global Office REITs average of 17.4x. That gap points to valuation risk if sentiment cools.
If you are weighing that risk against the earlier fair value narrative, it may help to see what the numbers imply at different earnings levels and peer comparisons. You can then decide which scenario aligns best with your own hurdle rate. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Easterly Government Properties can be useful if you let them sharpen your own decision rather than blur it. Move quickly from reading to testing the underlying numbers and viewpoints yourself with 2 key rewards and 3 important warning signs.
Looking for more Easterly Government Properties style ideas?
If Easterly Government Properties has sharpened your focus on valuation and risk, do not stop here. Use fresh screens to spot other opportunities tailored to your approach.
- Target stronger upside potential by zeroing in on companies flagged in the 20 high quality undiscovered gems.
- Prioritise financial resilience by scanning the list of solid balance sheet and fundamentals (25 results) that can better handle tougher conditions.
- Lock in income-focused opportunities by reviewing the 8 dividend fortresses built around higher yields with durability in mind.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com