
Leasing Strength Could Be A Game Changer For British Land (LSE:BLND)
- British Land has reported 12% like for like net rental income growth and a 5% rise in underlying EPS for the first half, while keeping full year guidance for at least 6% EPS growth and highlighting high occupancy in its London campuses and retail parks.
- The combination of 95% occupancy in London campuses and 99% leasing in retail parks underlines how British Land is filling space that had been vacant. This tightens supply and reinforces the role of these assets in driving rental income.
- We will now look at how British Land's like for like rental growth reshapes the longer term investment narrative for the group.
Compare British Land's leasing momentum with other real estate opportunities by reviewing a curated set of list of solid balance sheet and fundamentals (9 results) in this space.
British Land Investment Narrative Recap
To own British Land, you need to believe in high occupancy and rental resilience in London campuses and retail parks, plus disciplined capital allocation. The recent 12% like for like rental income growth and at least 6% underlying EPS guidance support that operating thesis. The near term catalyst is whether leasing strength continues into the upcoming Q2 2027 trading statement. The biggest risk is still high financing costs against a balance sheet where debt is not well covered by operating cash flow.
If rental demand softened or development leasing at projects such as Canada Water stalled, that combination could pressure earnings and asset values. If the Q2 update confirms that 95% campus and 99% retail park occupancy are stable or better, it would support the view that British Land’s focus on undersupplied segments is holding up, even while interest costs and execution risk on the pipeline remain front and centre.
The most relevant upcoming milestone is British Land’s Q2 2027 sales and trading statement on 15 October 2026. This update follows a half year where like for like net rental income rose 12% and underlying EPS increased 5%, with management reiterating full year EPS growth of at least 6%. That sets a clear bar. Investors will be watching whether leasing progress in London campuses and retail parks is translating into sustained rent collection and cash generation, given previous comments that debt is not well covered by operating cash flow.
This statement also matters for the broader narrative that British Land is recycling into higher yielding assets and aligning the portfolio with what occupiers want. Any detail on letting activity at Canada Water, Regent’s Place or other mixed use developments will feed directly into views on execution risk and capital needs. If management can show that occupancy levels are holding and that development spend is matched by visible tenant demand, it would ease some concerns around cost of capital, while a weaker tone on either front would keep leverage and refinancing conditions firmly in focus.
British Land Consensus Assumptions in Focus
Analysts sketch a British Land scenario where the group reaches £592.2 million of revenue and £514.7 million of earnings by 2028. That roadmap rests on 2.0% yearly top line expansion and an earnings increase of about £176.7 million from £338.0 million today.
Uncover why British Land's fair value indicates a 6% potential upside to its current price, which could narrow quickly if sentiment around British Land shifts.
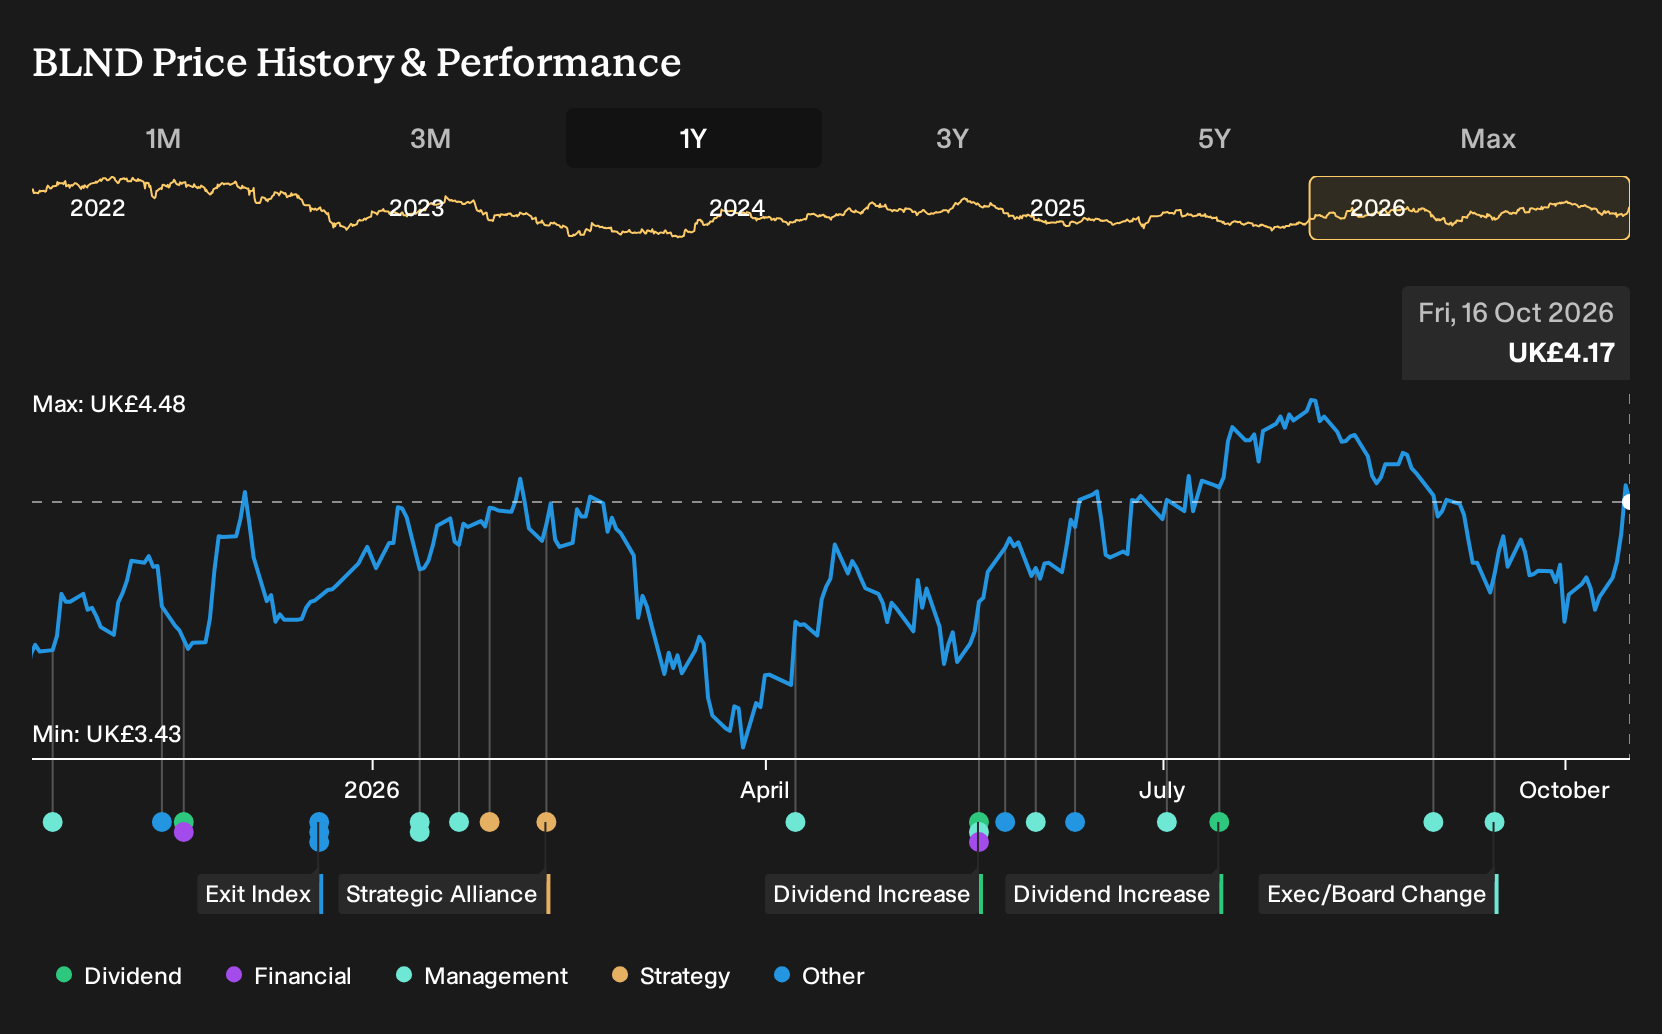
Exploring Other Perspectives
One alternate angle on British Land focuses on leasing risk in early stage science and tech space. The most pessimistic analysts were pencilling in roughly flat revenue over three years and earnings of about £538.2 million by 2029. That is a far cooler story than consensus, and the fresh Q2 2027 statement could push expectations closer to either camp.
Explore 3 other British Land fair value estimates, including one that suggests it could be worth just £4.41.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your British Land research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for British Land. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate British Land's overall financial health at a glance.
Looking for more investment ideas beyond British Land?
Once you have a view on British Land, it can help to widen the lens and see how other companies stack up on quality, value and resilience. The Simply Wall St Screener lets you filter for exactly the traits you care about, so you are not just reacting to headlines but comparing like for like across a broader opportunity set.
- If capital preservation matters to you, start with companies that screen well for balance sheet strength and steady fundamentals through our 4 resilient stocks with low risk scores.
- If you want income at the center of your plan, focus on cash generators offering robust payouts by reviewing a curated group of 4 dividend fortresses.
- If you prefer to hunt for mispriced opportunities, scan for quality businesses that look attractively valued on key metrics with the 9 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com