
3 Insurance Stocks Tied To Rising D And O Liability Demand
Washington risk has jumped from background noise to front-page driver, as talk of aggressive congressional probes puts boardrooms and executives directly in the spotlight. That kind of scrutiny often pushes companies to rethink how they protect directors and officers, and investors who ignore that shift risk missing where money quietly flows next. This piece unpacks the setup and then walks through three stocks tied to this liability story.
The three stocks that follow are just a starting sample, and the full screen surfaced 10 more US specialty insurers with D&O and professional liability angles that carry equally compelling narratives but are not covered in this article. To go deeper, analyze and identify your own highest conviction ideas directly in the US Specialty Insurers Focused on D&O and Professional Liability Coverage screener.
Ategrity Specialty Insurance Company Holdings (ASIC)
Overview: Ategrity Specialty Insurance Company Holdings is a New York based excess and surplus insurer offering specialized liability coverages to US small and mid sized businesses.
Operations: Ategrity generates about US$516.9 million of insurance revenue entirely from the United States, focused on a single insurance business segment.
Market Cap: US$1.25 billion
For investors tracking Washington driven liability risk, Ategrity Specialty Insurance Company Holdings offers a pure play way to follow demand for higher risk management and professional liability coverages as investigations and regulatory questions put more pressure on corporate decision making.
"The combined ratio has improved from 93.9% (2024) to 87.4% (Q1 2026) while GWP grew 23%+; a combination that suggests genuine underwriting discipline and technology-driven cost efficiency, not just cyclical tailwind"
What really matters from here is how one still unresolved pressure on its most complex long tailed liability book ultimately shapes future margins.
That pressure point is exactly where the story gets interesting, and the full narrative for Ategrity Specialty Insurance Company Holdings teases how Ategrity Specialty Insurance Company Holdings could see that risk decouple from headline ratios.

CNA Financial (CNA)
Overview: CNA Financial is a large commercial insurer that provides D&O, professional liability, and related coverage to corporate, professional, and healthcare clients globally.
Operations: CNA Financial generates most of its revenue from property and casualty insurance, with US$5.7b from Specialty, US$6.6b from Commercial, and US$1.5b from International, alongside a US$1.3b Life & Group book.
Market Cap: US$12.8b
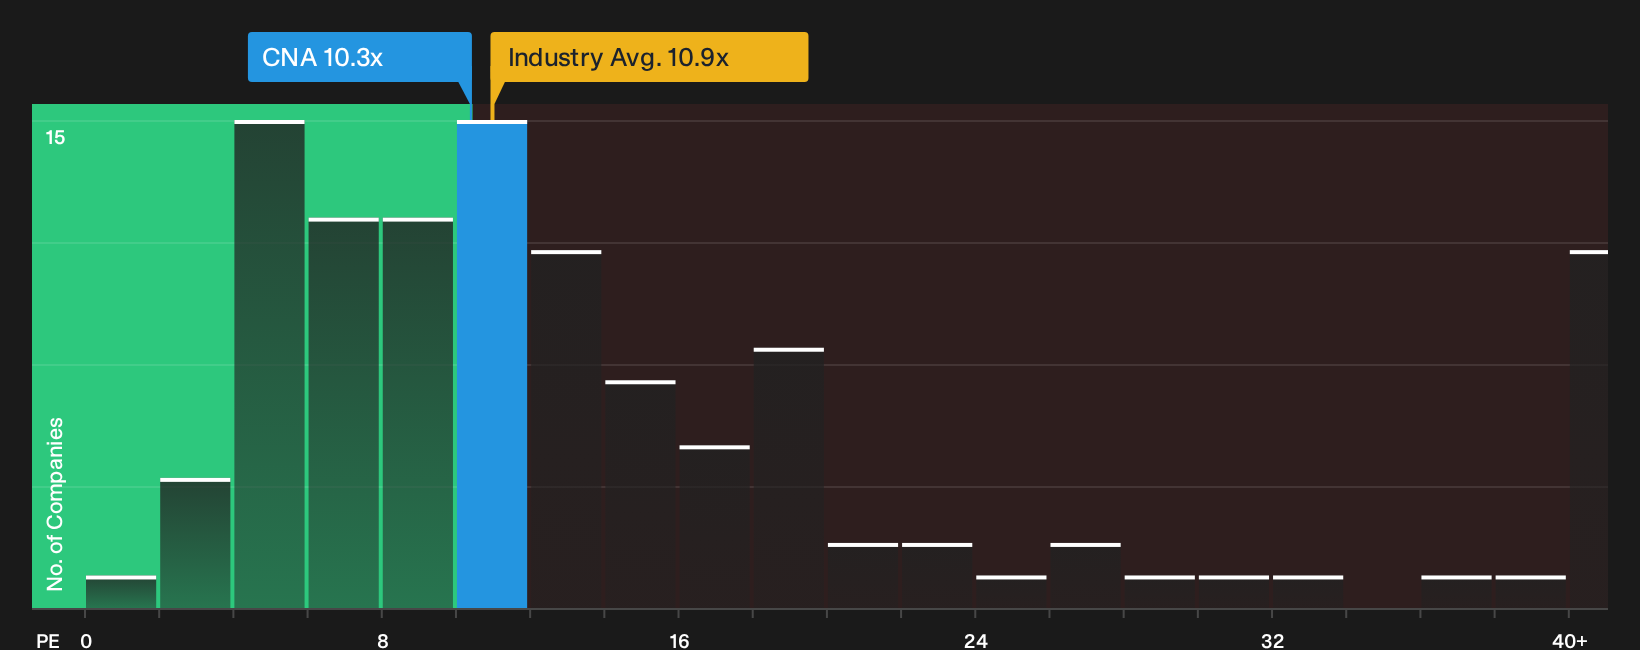
CNA Financial offers broad exposure to D&O and professional liability at scale. It is backed by a 10.3x P/E that sits below an estimated peer average near 15.3x and an 11.1% return on equity. The key swing factor for this liability-heavy portfolio is how one unseen pressure ultimately feeds through to pricing power and long-tail claim costs.
That unseen pressure is exactly where CNA Financial gets interesting. Go straight to the 4 key rewards and 2 important warning signs to see what might be masking the real opportunity.
Kinsale Capital Group (KNSL)
Overview: Kinsale Capital Group is a US specialty excess and surplus insurer focused on hard to place commercial and professional liability risks.
Operations: Kinsale Capital Group generates about US$2.0b of excess and surplus lines insurance revenue entirely from the United States.
Market Cap: US$8.0b
For a screener built around D&O, E&O and management liability, Kinsale Capital Group brings that theme into the smaller commercial arena where regulatory probes, contract disputes and professional missteps can quickly turn into lawsuits for clients that struggle to find coverage elsewhere.
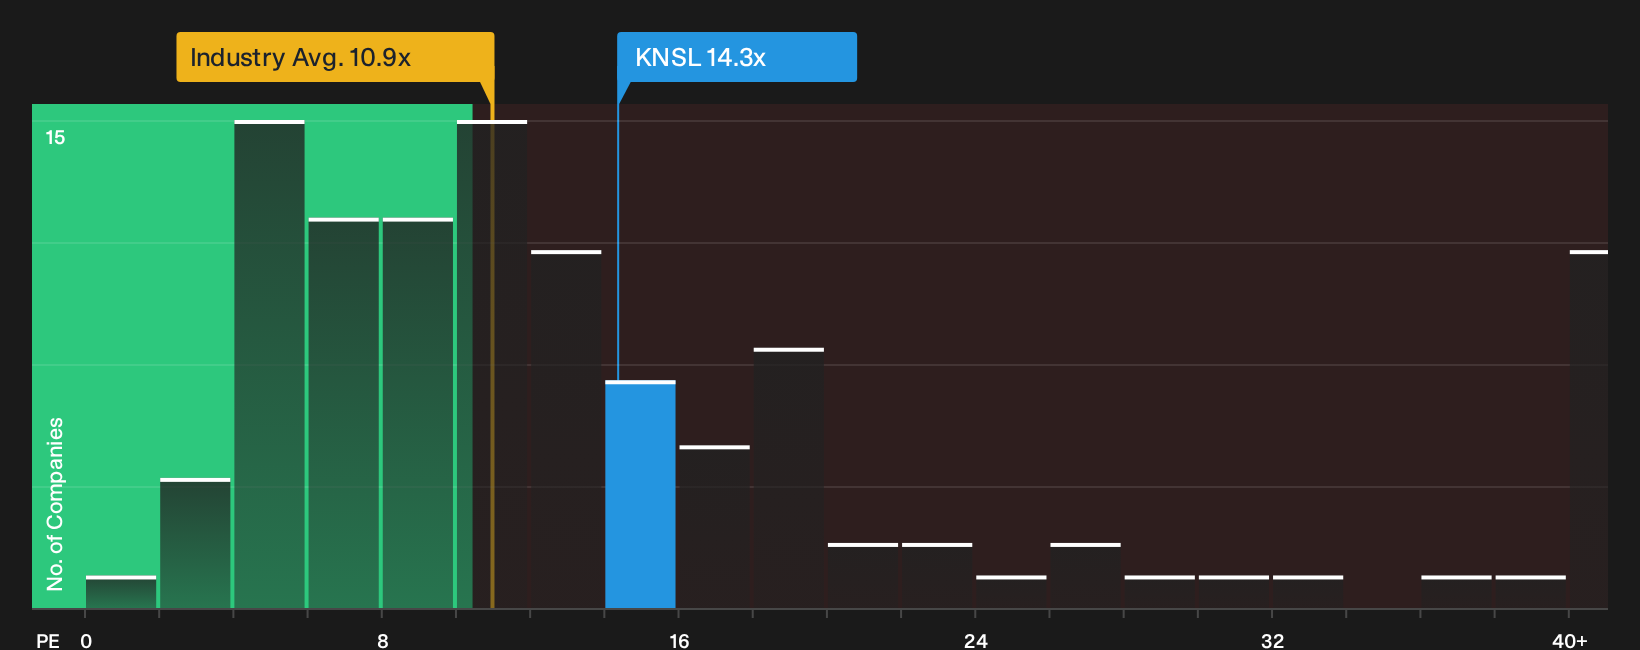
"Persistent strength in Kinsale Capital Group’s underwriting discipline, with combined ratios in the mid 70s and annualized operating ROE around the mid 20s, supports the view that current earnings quality is already high and helps explain why the stock can trade at a full multiple without relying on further margin expansion to sustain EPS."
What really decides how durable that story proves over time is how one slow moving shift in liability pricing and claim severity ultimately unfolds.
As that shift plays out, the full narrative for Kinsale Capital Group shows where Kinsale Capital Group’s liability pricing, claim trends, and valuation story could be quietly accelerating beyond headline metrics.
Seeking Alternatives Before The Crowd
Fresh breakout ideas do not stay quiet for long. Once momentum gets caught on screens, entry points start dropping fast. Scan these under the radar lists and get in early.
- Spot income workhorses that can keep paying you while markets move by reviewing the 7 dividend fortresses curated for resilience and yield focus.
- Track where real AI momentum and cash generation intersect by using the 38 profitable AI stocks that aren't just burning cash that highlights firms already funding growth from their own earnings.
- Position ahead of infrastructure spending tailwinds by checking the 41 power grid technology and infrastructure stocks featuring businesses tied to grid upgrades, reliability projects, and electrification themes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com