
Zip Co (ASX:ZIP) Launches Zip Cash, Is The Discount To Fair Value Warranted?
Zip Co (ASX:ZIP) has just put two big moves on the table: a CEO handover in its US arm and the planned launch of Zip Cash, a same-day cash loan product.
Set against these US announcements, Zip Co’s share price tells a mixed story. The A$2.17 level comes after a 1-day share price gain of 2.36%, yet the 90-day share price return has fallen 27.18% and the 1-year total shareholder return has declined 50.91%. However, the 3-year total shareholder return remains very large at about 7x, suggesting long-term holders have still seen substantial swings in perceived opportunity and risk.
Scan other lenders and payments players showing similar shifts in product mix and leadership by jumping into our curated list of list of solid balance sheet and fundamentals (12 results) around Zip Co's peer group.
Zip Co now trades at a clear discount to both analyst targets and one intrinsic value estimate. The real puzzle is whether that gap reflects mispricing or a fair response to the recent US shake up and new product risk.
Most Popular Narrative: 50% Undervalued
Zip Co’s most followed valuation story pins fair value around A$4.31 per share, almost double the A$2.17 last close. The new US leadership moves and Zip Cash rollout now sit inside a framework that already assumes a lot of progress on earnings, margins, and capital allocation.
Scaling distribution through partnerships and embedded finance with major merchants and platforms (such as Google Pay, Stripe, and large retailers in key verticals) is decreasing customer acquisition costs and increasing take rates, which should drive further operating leverage and higher earnings.
See why 89 investors see Zip Co as 50% undervalued.
Result: Fair Value of A$4.31 (UNDERVALUED)
Still, the analysts’ story on Zip Co can unravel quickly if regulators tighten BNPL rules faster than expected or if US-focused growth keeps overall margins under pressure.
Find out about the key risks to this Zip Co narrative.
Another View: Zip Co Through The P/E Lens
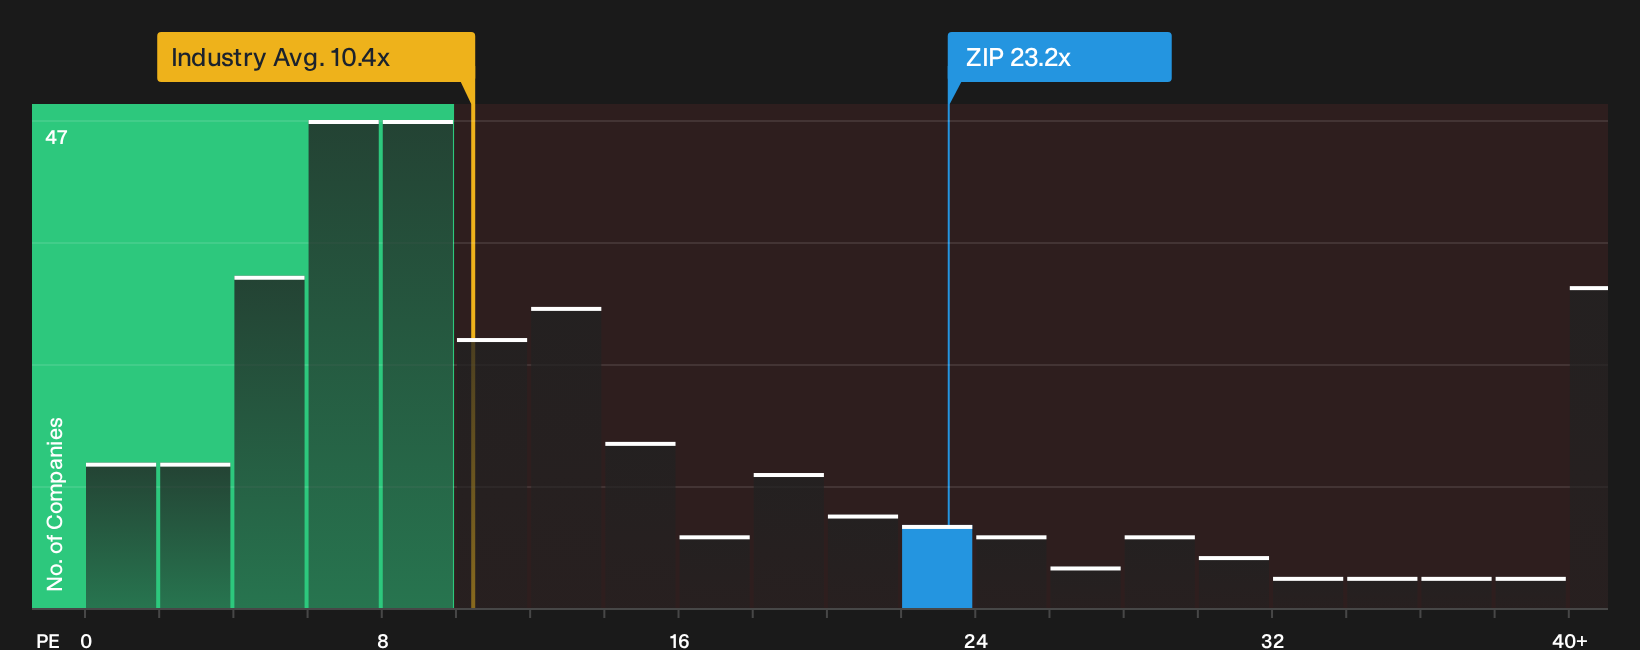
The earlier story leans on discounted cash flows and analyst fair value of about A$4.31 per Zip Co share. On simple earnings multiples, the picture looks very different. Zip trades on a P/E of 23.2x, while both local and global Consumer Finance peers sit closer to 10x.
A fair ratio for Zip Co is estimated at 28.6x earnings. This is higher than the current 23.2x level, and remains well above sector averages. That gap cuts both ways. Investors are effectively paying a premium to the industry, yet at a discount to what the fair ratio suggests the multiple could drift toward. Which side of that tradeoff feels more uncomfortable.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about Zip Co after all this.
If the crosscurrents feel strong, treat that as a signal to dig into the numbers, pressure test the story, and decide where you stand on the trade off between risk and upside. To help frame both sides, start with the 3 key rewards and 1 important warning sign
Looking for more Zip Co investment ideas?
If Zip Co leaves you on the fence, you may want to broaden your watchlist with a few targeted screens that surface clear, data backed opportunities before they move.
- Target resilient balance sheets and straightforward fundamentals by running the list of solid balance sheet and fundamentals (12 results).
- Hunt for quality companies priced below their estimated worth through the focused 4 high quality undervalued stocks.
- Seek growing businesses that the market has not fully noticed yet by scanning the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com