
How Investors May Respond To Ipsos (ENXTPA:IPS) Audience Measurement Deal
- tvbeat announced a partnership with Ipsos to deliver a new Audience Measurement System for TVNZ and Sky in New Zealand, combining large scale first party viewing data with independent audience research to support Total TV measurement.
- The collaboration gives Ipsos another real world deployment for cross platform media measurement and highlights how its research capabilities plug directly into broadcasters' need for consistent metrics across linear and streaming channels.
- Next, the focus will be on how Ipsos's role in New Zealand's Total TV measurement could reshape the broader investment narrative.
Ipsos Investment Narrative Recap
To own Ipsos, you need to believe that demand for evidence based decision making keeps building across sectors like healthcare, public affairs and consumer goods, and that the group’s mix shifts toward higher margin digital and AI enabled work. The recent New Zealand Total TV deal looks helpful but not like a game changing near term catalyst.
The more immediate swing factor remains execution on margin improvement and integration of past acquisitions, which management has flagged as dilutive for a period. The biggest operational risk is still client budget pressure, especially in public sector and Asia, combined with FX volatility that can blunt progress even when the business is doing the right things commercially.
The Human Advantage Conference in 2026 gives useful context for the tvbeat partnership. Ipsos put behavioural science and AI at the center of how it wants clients to use its data, which lines up neatly with cross platform media measurement where speed, granularity and explainability all matter.
If you care about catalysts, this sort of thought leadership matters because it shows Ipsos trying to stitch together its AI tools, behavioural expertise and audience work into cohesive offerings that can travel across sectors. The risk is straightforward. If clients delay spend or do not adopt these newer platforms at scale, earnings growth that is currently forecast in the low double digits could prove harder to realise.
Ipsos' current earnings are €186.6 million, with analysts forecasting consensus earnings of €234.3 million by 2029. This implies an increase of about €47.7 million, with revenue projections of €2.7 billion by that same year based on an assumed 2.3% yearly rise in top line performance.
Discover why Ipsos' fair value indicates a 50% potential upside to its current price, and why that opportunity could narrow quickly.
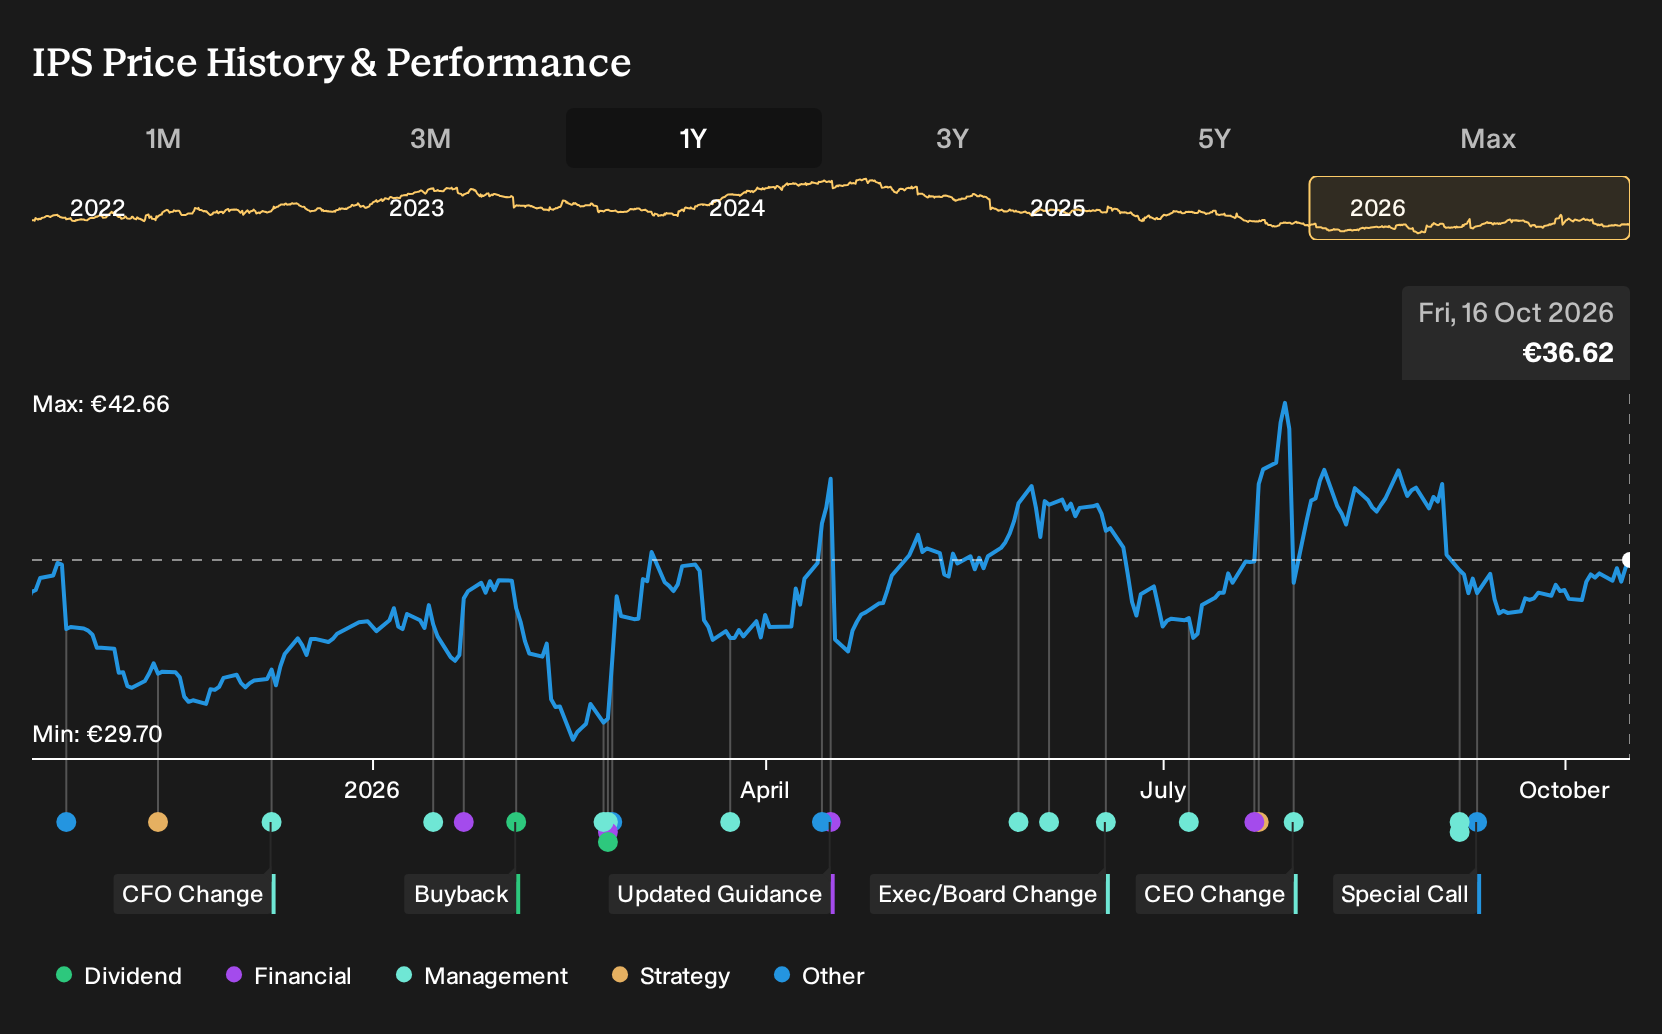
Exploring Other Perspectives
One alternate view puts Ipsos’ AI push itself at the centre of the risk. Bearish analysts worry digital tools could cannibalise higher priced work and leave earnings closer to €231.5 million on about €2.7 billion of revenue by 2029. Those pre news estimates are more cautious than consensus, and the tvbeat deal could eventually shift either story.
Explore 4 other Ipsos fair value estimates, including one that suggests it could be worth just €38.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ipsos research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ipsos. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ipsos' overall financial health at a glance.
Looking for more investment ideas beyond Ipsos?
If the Ipsos story has sharpened your view on data driven businesses, you can widen the opportunity set quickly by using targeted stock screens that surface companies with specific financial traits.
- If you want potential mispricing on quality, start with companies highlighted in 193 high quality undervalued stocks that pair stronger balance sheets and cash flows with prices that screens suggest may be out of step with fundamentals.
- If capital protection sits high on your priority list, focus on the 233 resilient stocks with low risk scores which concentrates on businesses flagged for more resilient financial profiles and lower overall risk scores.
- If you prefer established payouts to hypothetical growth stories, scan the 212 dividend fortresses which filters for stocks offering yields above 5% where the income stream is central to the thesis.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com