
How Investors May Respond To Cogeco Communications Stock After Analyst Downgrades
- Cogeco Communications is under pressure as recent analyst downgrades highlight concerns about profitability and higher leverage, set against a backdrop of relatively low valuation multiples.
- The tension between questions about earnings quality and a revenue-based valuation that sits below industry averages puts Cogeco Communications' core telecom operations in sharp focus.
- This article will now explore how Cogeco Communications' investment narrative could be reshaped by fresh worries about profitability and elevated leverage.
Look beyond Cogeco Communications and review our curated list of 6 high quality undervalued stocks, which also trade on lower revenue multiples and face questions around earnings quality.
Cogeco Communications Investment Narrative Recap
To own Cogeco Communications today, you need to be comfortable with a telecom group that is currently unprofitable and carrying meaningful debt, while still investing in network build outs and transformation. The recent analyst downgrades focus attention on whether margins can recover fast enough to keep interest costs and a 7.63% dividend manageable.
In the short term, the key potential catalyst is the expected lift in free cash flow as the heavy rural and modernization spend winds down and U.S. and Canadian operations look for efficiencies. The biggest near term risk is that competition and weak Breezeline trends keep earnings soft, which would keep leverage and interest coverage under pressure.
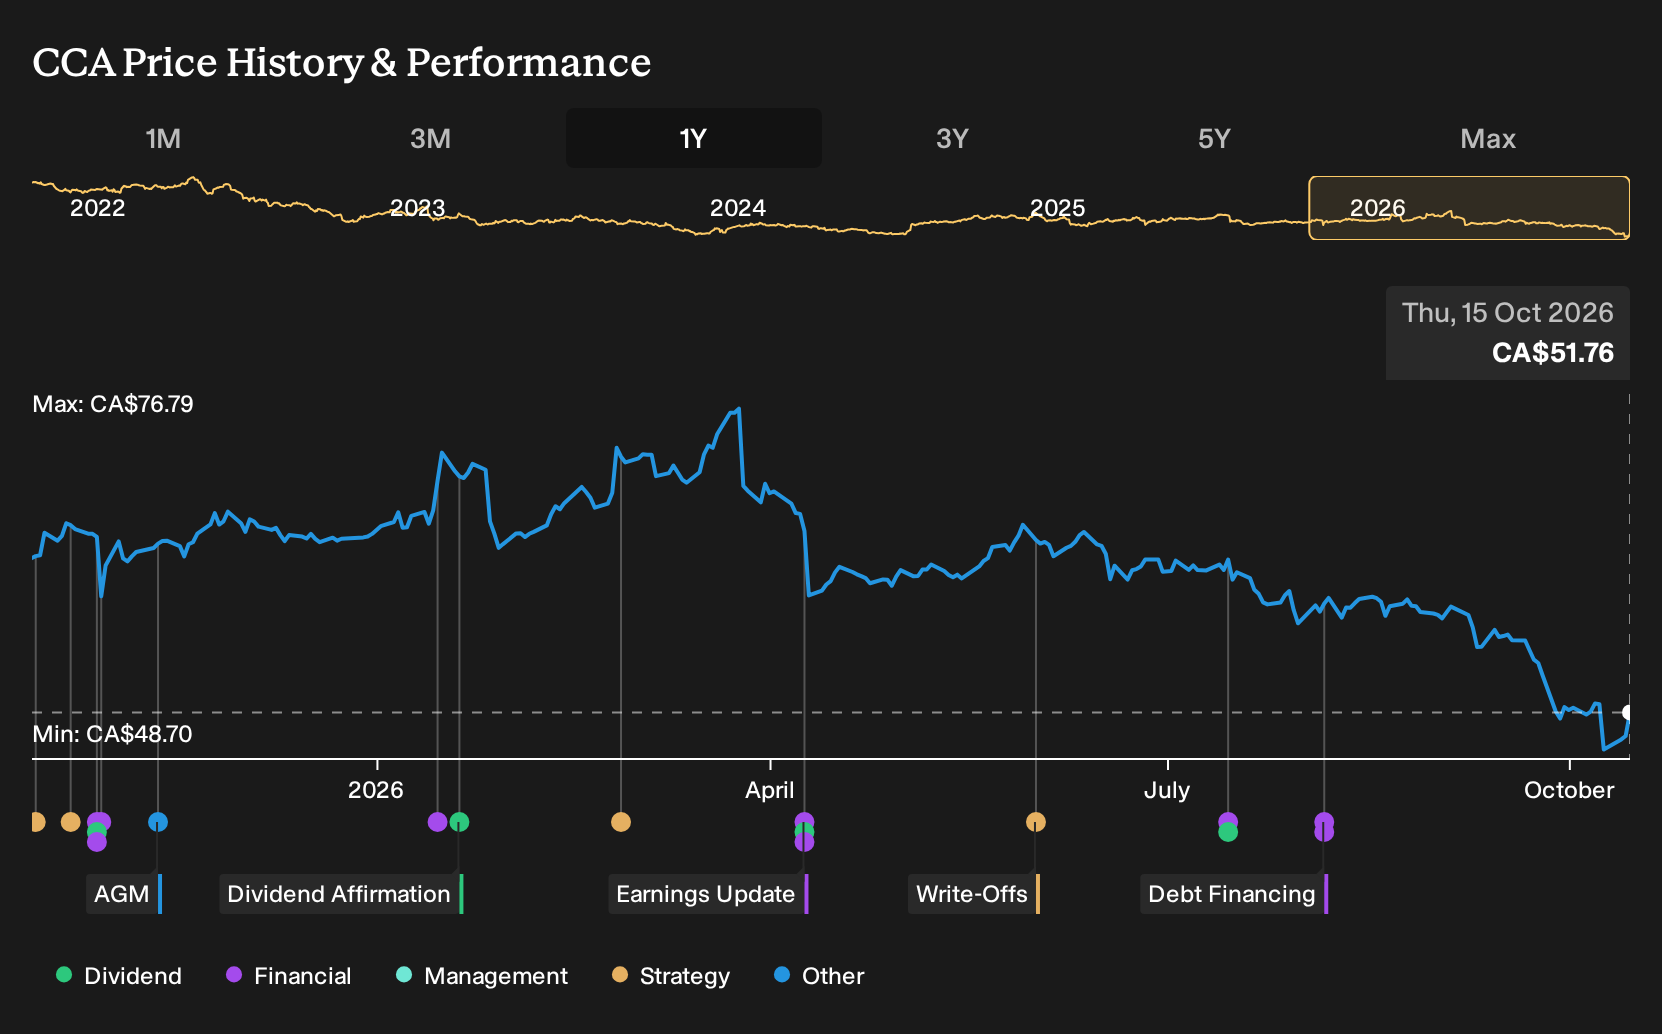
Recent commentary around profitability and leverage effectively puts every major Cogeco Communications initiative under the microscope. The rural network build, the Ontario fiber rollout, and the wireless push in both Canada and the U.S. all matter more when the stock has already fallen 38.4% over five years and interest costs are not comfortably covered.
As for catalysts, investors are watching for concrete proof that the investment cycle is actually easing and that synergies between Canadian and U.S. teams start to show up in cleaner EBITDA and cash generation. Evidence of better execution in Breezeline and signs that wireless can support customer retention would go a long way toward easing current concerns.
Cogeco Communications' current analyst narrative points to CA$2.8b in revenue and CA$354.0m in earnings by 2029. That profile sits on top of a 1.0% yearly revenue decline assumption and an earnings increase of CA$38.0m from CA$316.0m today.
Uncover why Cogeco Communications' fair value indicates a 42% potential upside to its current price. This reflects a discount that could narrow quickly as sentiment stabilizes.
Exploring Other Perspectives
One alternate view hangs on Cogeco Communications squeezing more efficiency out of its network. Before these downgrades, the most optimistic analysts were pencilling in CA$2.7b of revenue and CA$364.2m of earnings by 2029, tied to stronger margin gains. That is a more upbeat story, and this news could push those forecasts to shift.
Explore 4 other Cogeco Communications fair value estimates, including one that suggests there could be as much as 381% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider following your own analysis and judgment.
- A great starting point for your Cogeco Communications research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cogeco Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cogeco Communications' overall financial health at a glance.
Looking For More Ideas Beyond Cogeco Communications?
If you want to pressure test your thesis on Cogeco Communications, it can help to line it up against other companies with different balance sheets, dividend profiles, and risk levels. The Simply Wall St Screener lets you quickly filter for other stocks that match or contrast with what you see in Cogeco Communications today.
- For income focused investing, see which companies combine higher yields with stronger payout support through the 3 dividend fortresses.
- If capital preservation matters more to you right now, scan for businesses that pair steadier finances with lower risk scores using the 8 resilient stocks with low risk scores.
- When you want growth potential backed by fundamentals, look across a 10 high quality undiscovered gems that may not yet be widely followed by the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com