
How Investors May Respond To Jazz Pharmaceuticals (JAZZ) FDA Cancer Drug Approval
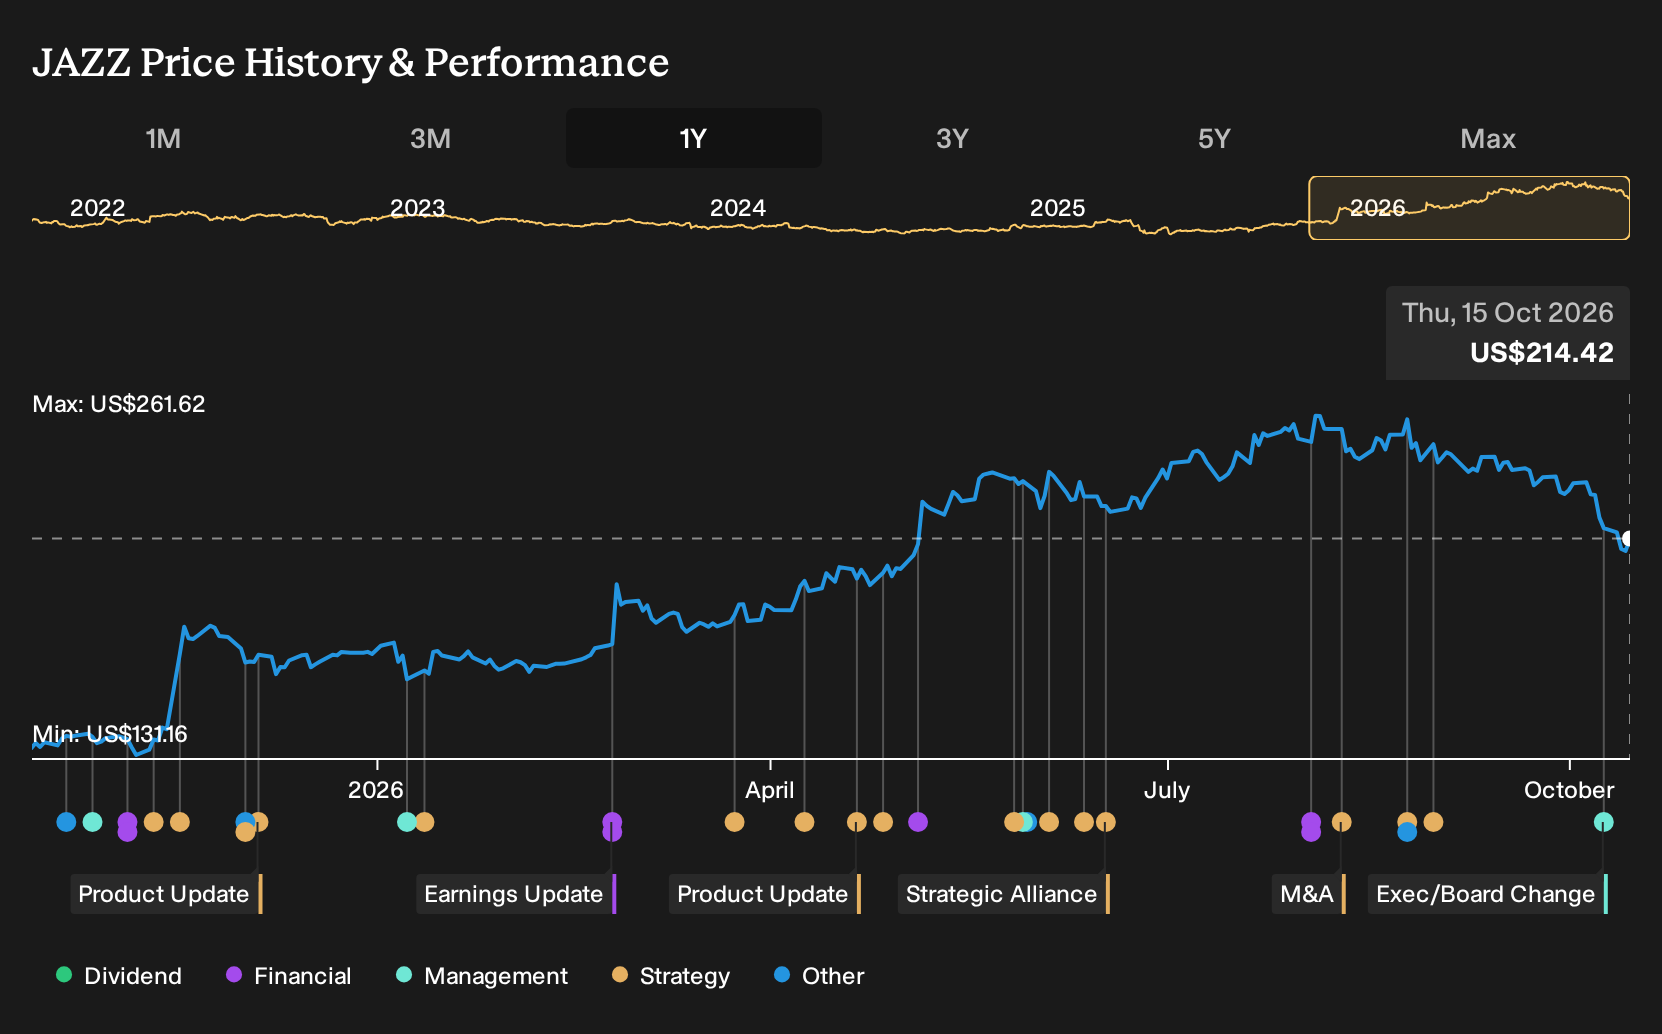
- Jazz Pharmaceuticals received US FDA approval for its oncology drug Ziihera and earlier this month disclosed that Chief Commercial Officer Samantha Pearce plans to retire by June 30, 2027 or upon appointment of a successor.
- Ziihera's entry into the US cancer market gives Jazz Pharmaceuticals another commercial product in oncology at the same time leadership prepares for a planned commercial transition.
- We will now look at how Jazz Pharmaceuticals' investment narrative could shift as Ziihera's FDA approval reshapes its oncology profile.
Jazz Pharmaceuticals Investment Narrative Recap
To own Jazz Pharmaceuticals, you effectively need to buy into two things. First, that its sleep and epilepsy therapies and newer oncology launches like Ziihera can support a multi-franchise model rather than a single-product story. Second, that management keeps execution tight even as key leaders rotate and the oncology mix becomes more complex to run.
Right now the most important near term swing factor is how Ziihera ramps and broadens Jazz Pharmaceuticals' oncology profile. The biggest risk is pressure on the older sleep franchise and the balance sheet if debt stays high while competition and patent issues bite. Samantha Pearce’s planned retirement looks meaningful, but not thesis breaking, if the commercial handover runs smoothly.
The Ziihera approval is the clearest recent announcement to focus on. It speaks directly to whether Jazz Pharmaceuticals can offset pressure from patent expirations and generic threats around Xyrem and related products. A new HER2 therapy in biliary tract cancers gives the group another oncology pillar that is less tied to its historic sleep focus and broadens its revenue mix.
For you as a shareholder, Ziihera sits alongside assets like Epidiolex and Xywav as part of a wider set of potential catalysts, rather than a single silver bullet. Execution risk is still real. Jazz Pharmaceuticals needs to turn that label into sustained prescribing, defend market share against other cancer agents, and do all of this while absorbing higher expenses and servicing its debt load.
What The Current Analyst Forecasts Assume For Jazz Pharmaceuticals
Analysts currently frame Jazz Pharmaceuticals as a business that could support higher revenue and earnings over time if Ziihera and the broader portfolio execute as expected. Their consensus points to a forecast revenue base of US$5.7b and earnings of US$1.7b by 2029, with that outlook relying on oncology, sleep, and epilepsy all pulling weight rather than a single blockbuster carrying the story.
These projections rest on several core levers. Revenue is modeled to expand at 7.4% per year over the next three years, while profit margins are expected to move from 20.4% today to 29.4% over the same horizon. On the bottom line, earnings today are quoted at US$940.8m and the 2029 consensus estimate of US$1.7b implies an increase of roughly US$759m in annual profit if the forecasts play out.
Jazz Pharmaceuticals' consensus outlook assumes revenues of US$5.7b and earnings of US$1.7b by 2029. This embeds 7.4% yearly revenue growth and around US$759m higher earnings from US$940.8m today.
Uncover why Jazz Pharmaceuticals' fair value indicates a 37% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle puts Jazz Pharmaceuticals’ execution risk at the center. The most optimistic analysts were already modeling about US$6.6b revenue and US$2.2b earnings by 2029 even before Ziihera’s approval and Samantha Pearce’s retirement plan. You can treat those bullish numbers as a ceiling that may shift as new views emerge.
Explore 3 other Jazz Pharmaceuticals fair value estimates, including one that suggests there could be as much as 416% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jazz Pharmaceuticals research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Jazz Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jazz Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Jazz Pharmaceuticals?
Once you have a handle on Jazz Pharmaceuticals, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles.
- If you want potential upside with strict quality filters on balance sheets and fundamentals, scan through the list of solid balance sheet and fundamentals (25 results) to see which businesses clear those hurdles.
- For investors who care most about price versus fundamentals, use the 33 high quality undervalued stocks to spot companies that screen as strong quality at a discount.
- If resilience and capital preservation matter more to you than aiming for the highest return, the 32 resilient stocks with low risk scores can help surface candidates with calmer risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com