
How Strong Cash Flow Could Impact Elementis Stock Investors
- Elementis is in focus after fresh analysis highlighted the company’s free cash flow forecasts and the role of cost simplification efforts in supporting future cash generation.
- An important angle is how operational efficiency programs could allow Elementis to sustain cash generation even if end-market demand remains uneven.
- We will now look at how Elementis' cash flow outlook and efficiency initiatives could influence the broader investment narrative around the business.
Compare Elementis' cash generation story with other potential mispriced opportunities by scanning our curated list of 7 high quality undervalued stocks.
Elementis Investment Narrative Recap
To own Elementis, you need to believe the specialty additives focus can keep turning into solid free cash flow, even with only modest revenue growth expected. The recent analysis on cash generation and cost simplification largely supports that view, since it points to a business that stays cash generative rather than one reliant on aggressive top line expansion.
The flip side is concentration risk and execution. The biggest near term swing factor remains how effectively Elementis delivers its next tranche of cost savings without weakening R&D or commercial capability. The main risk is that efficiency drives go too far, leaving the group underpowered just as customer needs and chemistries evolve.
Recent commentary around an extra £10 million of cost savings is central to this story. It connects directly to the free cash flow forecasts that suggest Elementis can keep generating cash even if demand in coatings or personal care is patchy, because the underlying cost base is leaner and more predictable.
For you as a shareholder, that program sits right beside the growth push into higher value rheology modifiers and new applications. Execution quality will decide whether those savings translate into lasting margin strength or creep into the risks list by stretching a relatively new management team and a still maturing R&D engine.
Elementis Forecasts In Context
Analysts sketch a simple story for Elementis. The specialty additives push only needs low single digit headline expansion to line up with the current forecasts. Revenue is assumed to rise by 1.4% a year over the next three years, which is described as a modest lift rather than a big swing in top line expectations.
Earnings today are put at US$71.7 million and consensus points to US$101.4 million by 2029. That is an increase of about US$29.7 million, which is roughly 40% higher than the current level in absolute terms. For that 2029 view to hold, analysts are also assuming a margin step up from 11.5% today to 15.5% in three years, so a portion of the profit uplift is expected to come from efficiency and mix rather than rapid volume growth.
Those same forecasts tie directly into the valuation work. By 2029, the projections used in the stock research call for Elementis to generate US$652.3 million of revenue and US$101.4 million of earnings on a P/E multiple of 20.1x. That compares with a P/E of 18.5x today and sits above the cited GB Chemicals sector level of 18.6x, which indicates that the investment case assumes some improvement in both profitability and the rating investors are willing to pay for those earnings.
Elementis' narrative projects US$652.3 million revenue and US$101.4 million earnings by 2029. This requires 1.4% yearly revenue growth and an earnings increase of about US$29.7 million from US$71.7 million.
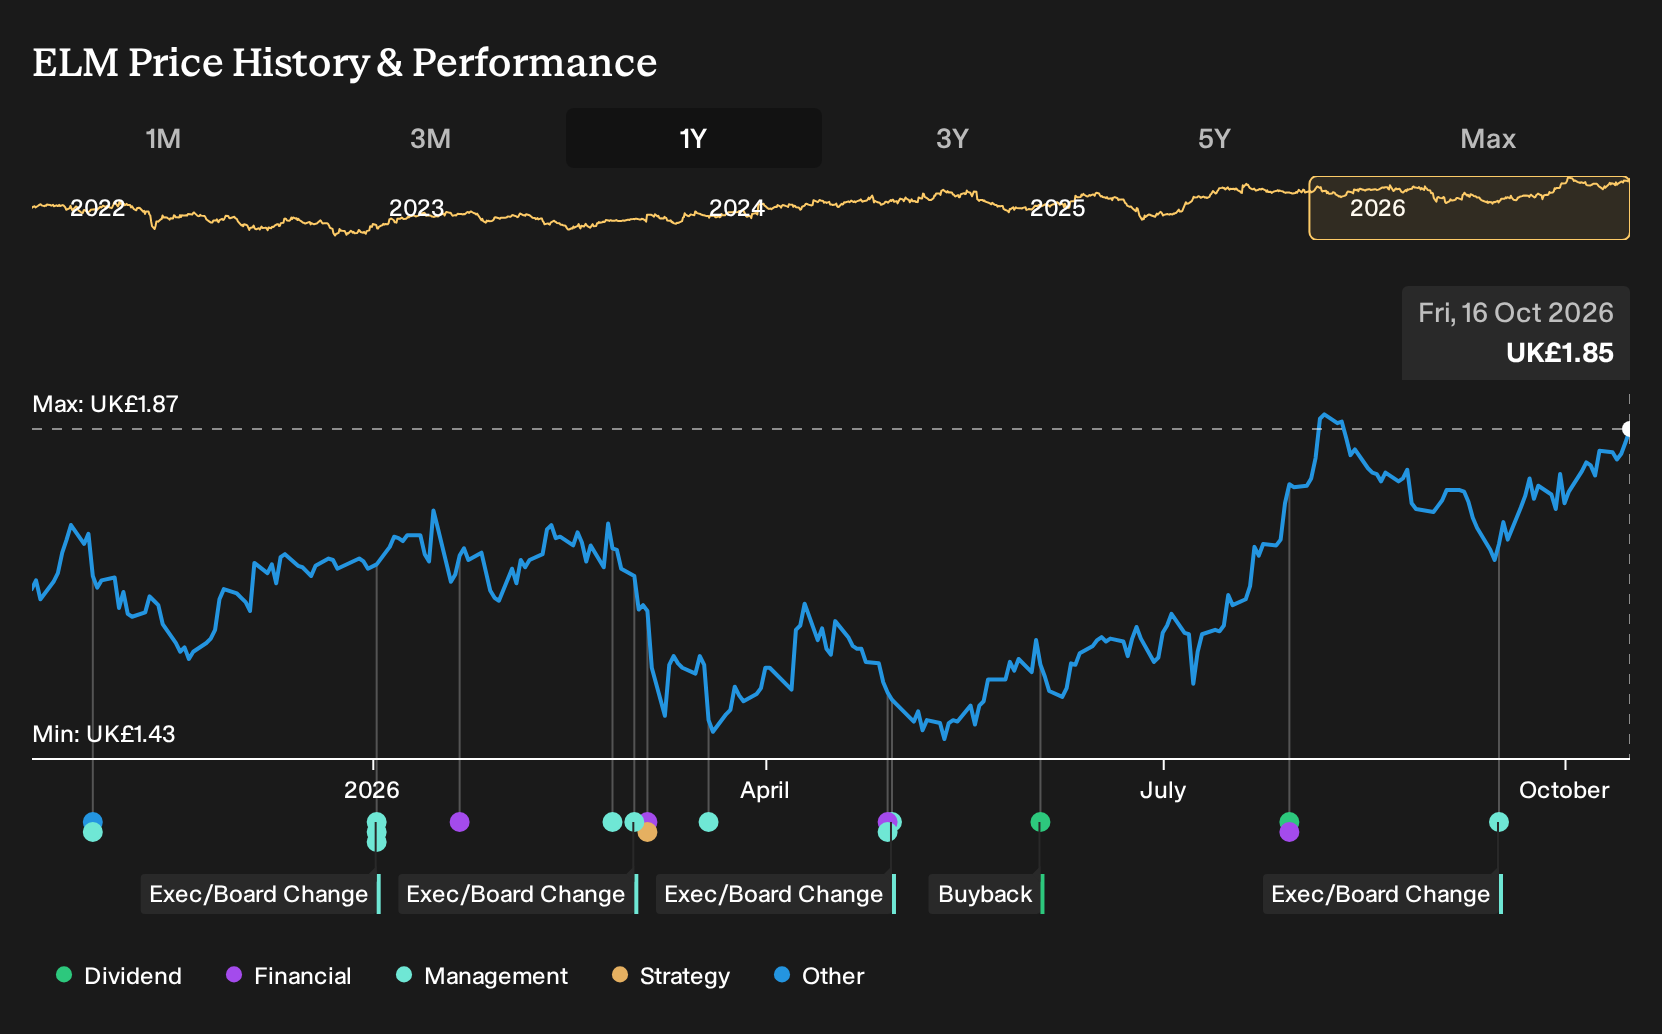
Uncover why Elementis' fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The two fair value estimates for Elementis from the Simply Wall St Community cluster tightly between 2.13 and 2.32, yet even this narrow spread shows how retail views can diverge. Those opinions do not reflect the latest focus on specialty additives or concentration risk, so you may want to weigh several fresh viewpoints before framing your own stance.
Explore another Elementis fair value estimate, including one that suggests it could be worth just £2.13.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Elementis research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Elementis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elementis' overall financial health at a glance.
Looking For More Investment Ideas Beyond Elementis?
Once you have a handle on Elementis, it can help to benchmark that thesis against other situations where the numbers and story might line up differently.
- If you care most about resilience and capital preservation, start with a 4 resilient stocks with low risk scores that have historically been less volatile and may suit a more measured approach.
- For investors who want efficient balance sheets and cleaner fundamentals, narrow your focus to a list of solid balance sheet and fundamentals (9 results) that meet strict financial health filters.
- If you like the idea of getting in early before wider attention arrives, widen your search to a 5 high quality undiscovered gems that still show strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com