
How Investors May Respond To Volution Group (LSE:FAN) Strong Results And Dividend Raise
- Volution Group reported full year 2026 sales of £484.8m and net income of £62.5m, alongside an 18.5% higher total dividend of 12.8 pence per share compared with the prior year.
- The board paired this higher payout with commentary on the Fantech integration, which points to management confidence in cash generation and the Australasian business footprint.
- We will examine how Volution Group's investment narrative is affected by robust earnings and a sharply higher total dividend payout.
Volution Group Investment Narrative Recap
To own Volution Group, you need to be comfortable with a ventilation specialist that leans on steady demand from regulation driven projects, a growing Australasian footprint and a clear focus on higher margin, low carbon products. The latest full year results show the business currently converting that positioning into higher sales, stronger earnings and solid cash generation.
The key short term catalyst is still execution on Fantech and broader integration across Australasia, where cross selling and procurement efficiencies are central. The biggest near term risk remains that integration complexity, alongside currency swings and existing leverage that could limit flexibility if trading conditions soften.
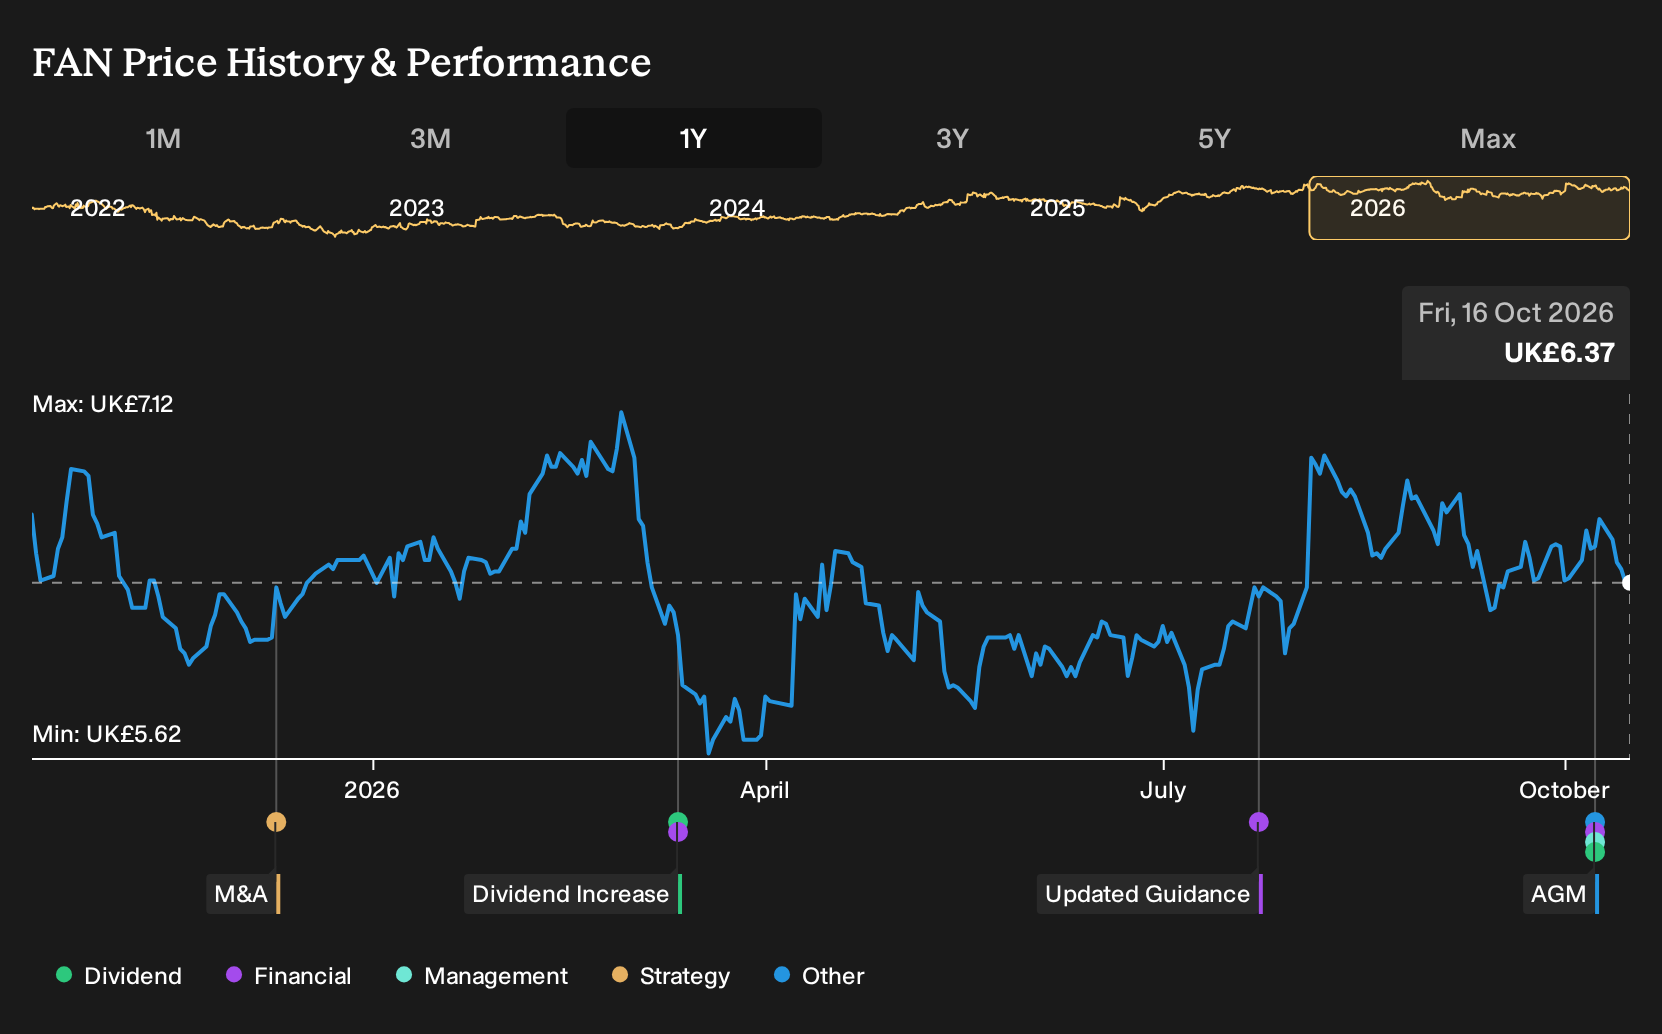
The dividend announcement on 8 October 2026 is the clearest operational signal to watch. Volution Group’s board has recommended a final dividend of 8.8 pence per share, taking the full year payout to 12.8 pence. That compares with 10.8 pence a year earlier, which represents an 18.5% higher total dividend, subject to shareholder approval in December.
This move matters because it directly links to the cash generation story that underpins the Fantech acquisition and any future deals. A higher proposed payout can reinforce the view that recent earnings momentum is backed by real cash, although it also leaves less room to reduce debt quickly if integration challenges, regional softness or currency moves start to bite.
Volution Group's current analyst narrative points to forecast revenue of £561.1 million and earnings of £75.5 million by 2029, which assumes revenue growing at 6.9% per year and an earnings increase of about £24.0 million from £51.5 million today.
Uncover how Volution Group's fair value indicates an 18% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between £5.72 and £7.54, so you are seeing a tight band rather than an extreme outlier. Set that beside the recent earnings call, the 18.5% dividend uplift and upcoming board change, and you get very different readings on how Volution Group could balance growth, cash returns and governance over time. Consider these contrasts and explore several alternative viewpoints before deciding how this situation fits your portfolio framework.
Explore 2 other Volution Group fair value estimates, including one that suggests as much as 10% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Volution Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Volution Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Volution Group's overall financial health at a glance.
Looking for more Volution Group style ideas?
If the Volution Group story has sharpened your thinking about cash generation, dividends and balance sheet strength, use that same lens to scan a wider opportunity set with the Simply Wall St Screener.
- For investors who want income without losing sleep over balance sheet resilience, review a focused 2 dividend fortresses that aim to combine higher yields with sturdier financial profiles.
- If capital preservation sits high on your priority list, filter for 4 resilient stocks with low risk scores and see which businesses score well on stability and financial health.
- When you are hunting for quality outside the usual crowd favorites, draw on a curated 5 high quality undiscovered gems that concentrate on fundamentals rather than headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com