
SK Hynix (NasdaqGS:SKHY) Stock Trades At A Discount After A 22% Fall
SK hynix has just come through a rough stretch, with the stock sliding sharply as investors reassess how much they are willing to pay for its earnings in a more crowded memory and AI chip market. After that pullback, the question is whether the current share price still lines up with what the business is earning today and what those profits can support over time.
- The share price has fallen about 22% over the past month, which puts fresh focus on whether the earnings underpinning SK hynix now justify this lower level.
- Recent headlines around Chinese rival CXMT's technology progress and comments about froth in AI related chips can influence how investors think about SK hynix's future pricing power, profitability and the earnings stream they are paying for today.
- There is a second opinion on SK hynix worth weighing. See what analysts think SK hynix's shares could be worth.
The issue now is whether the stock's current valuation is adequately supported by SK hynix's earnings power relative to the wider semiconductor industry.
If you want to stress test SK hynix against other AI exposed chipmakers, a focused stock screen built around 55 AI infrastructure stocks.
Does SK hynix Look Undervalued on Earnings?
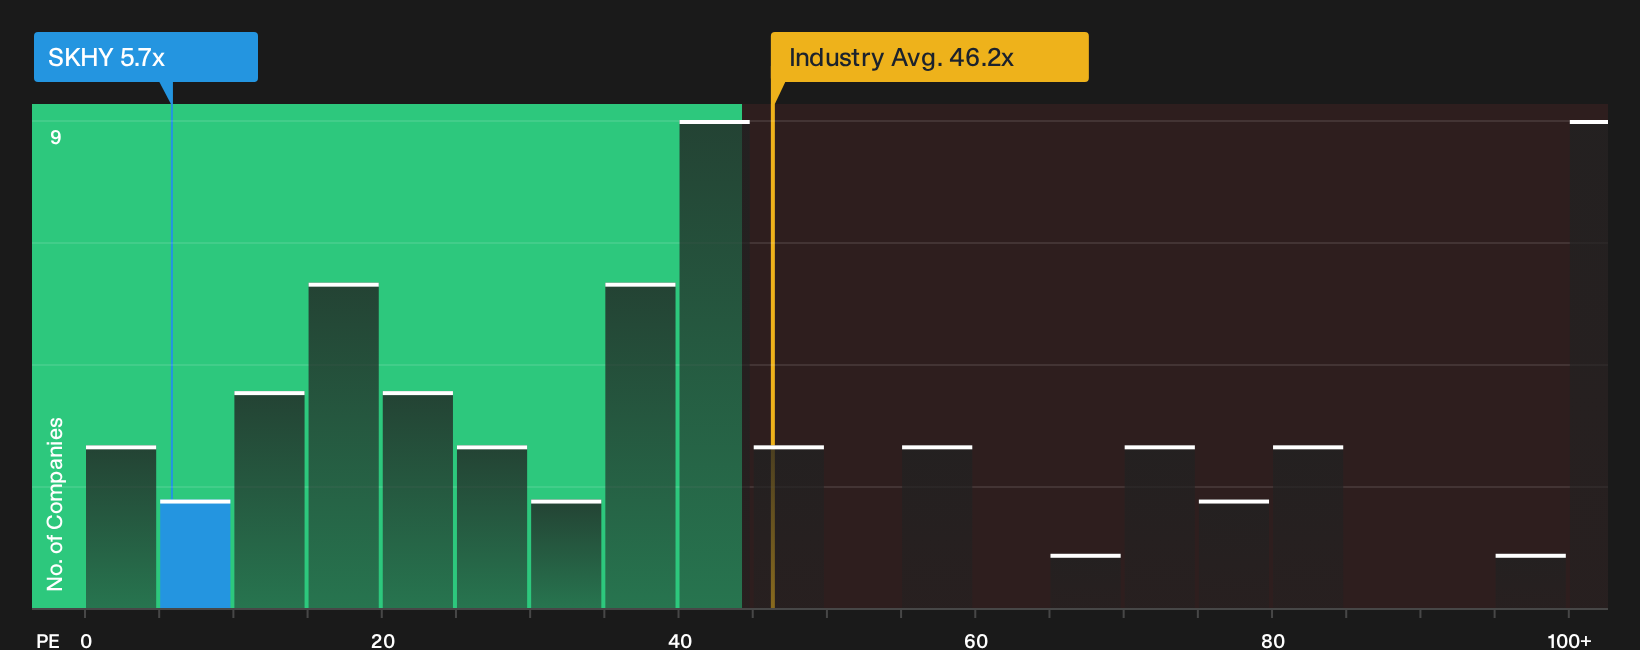
The P/E ratio suits SK hynix because earnings are the metric investors most often watch for established chip designers and memory makers. On this lens, the stock trades on roughly 5.7x earnings. The wider semiconductor group sits closer to 46.2x, while the peer set on this data screens at about 53.2x. This multiple puts SK hynix at a steep discount relative to both its sector and closer comparables.
Because recent headlines around CXMT and tougher AI sentiment have pulled prices down in the short term, this low P/E indicates that the market is pricing SK hynix cautiously despite its role in high bandwidth memory and AI infrastructure. A ratio this far below industry norms can reflect concerns about future profitability, cyclicality or competitive pressure. You need to weigh how durable the earnings stream behind that 5.7x figure is before treating it as a simple bargain. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where SK hynix's P/E puzzle leaves off. They spell out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth far more or materially less than today’s price. Each scenario ties a fair value estimate to a specific story about SK hynix's possible catalysts and risks so you can track over time which version of events appears to be unfolding.
A clear, number driven Narrative on SK hynix gives you a single place to set out what you think about issues like CXMT's technology progress, AI chip sentiment and SK hynix's China and US expansion plans, then see in real time whether the firm’s reported earnings, margins and capital decisions actually line up with those expectations. That kind of written roadmap turns a volatile headline cycle into a series of testable checkpoints rather than a stream of disconnected price moves.
Share your own Narrative for SK hynix and set out the assumptions behind your valuation.
One more SK hynix question that could matter more than the multiple
Valuation only tells part of the story for SK hynix, because separate checks have flagged potential pressure points that investors may want to inspect before leaning on the earnings multiple alone. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com