
Does Distribution Hike Change The Bull Case For Enterprise Products Partners Stock (EPD)?
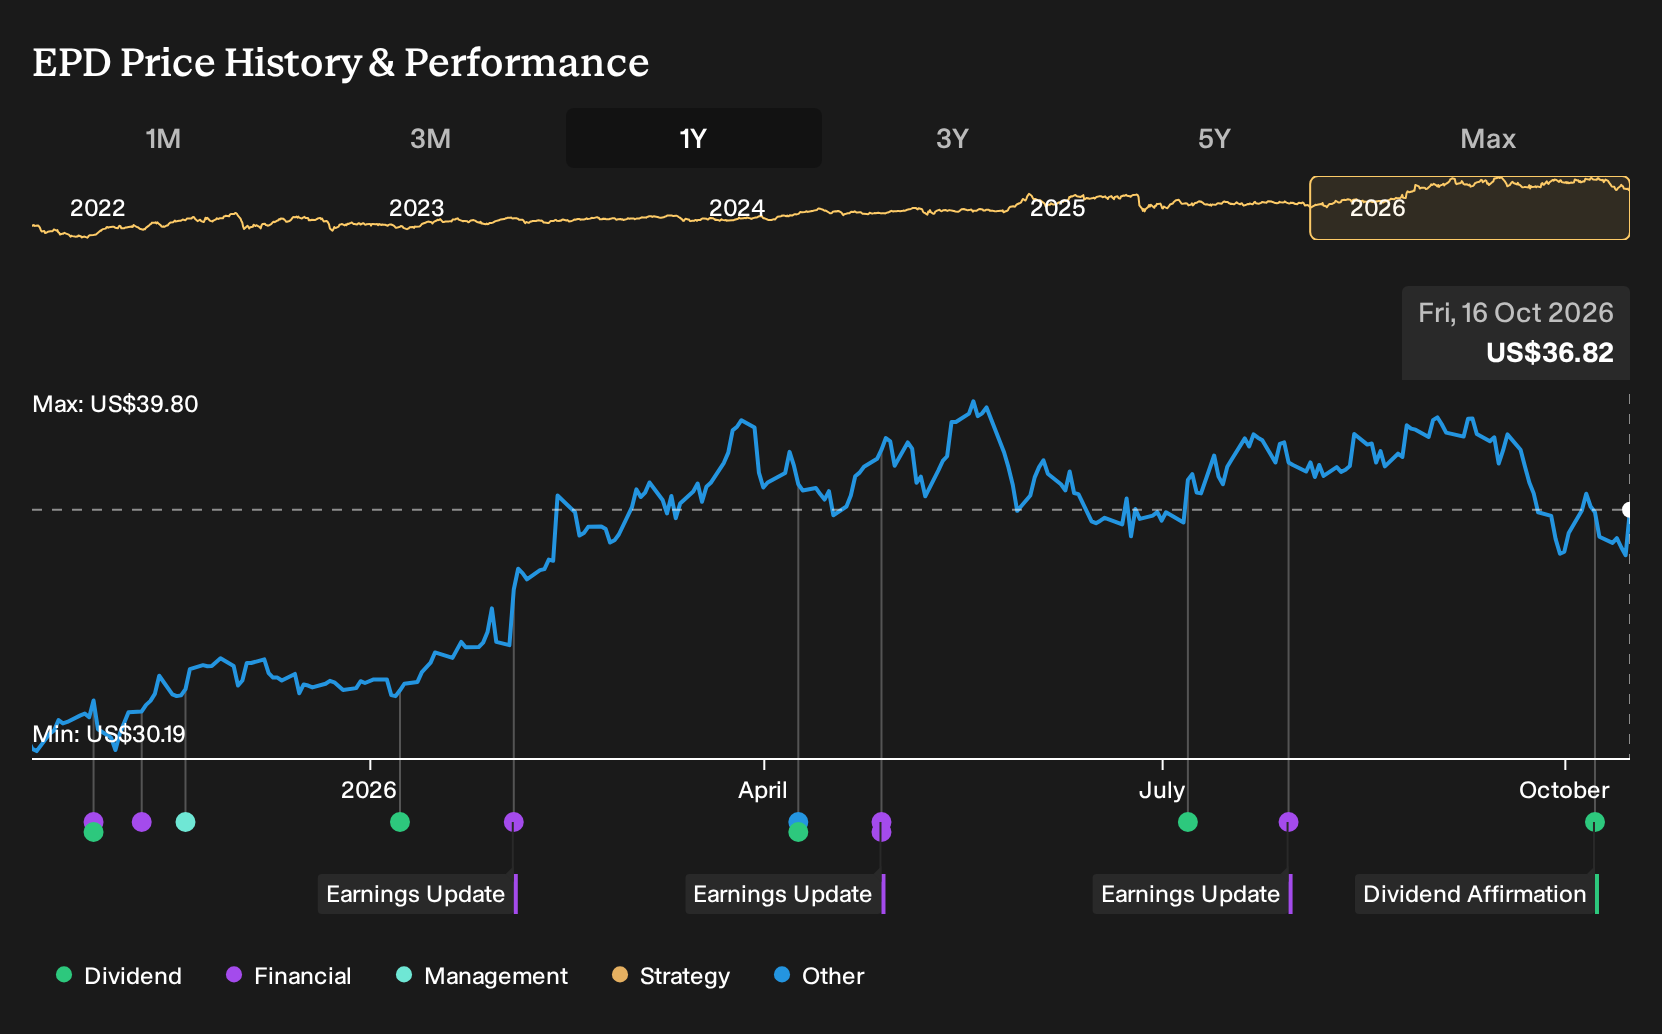
- Enterprise Products Partners raised its third quarter 2026 cash distribution to $0.56 per unit, or $2.24 on an annualized basis, a 2.8% increase over the prior year, and completed $1,822.31 million of unit repurchases under its buyback program, including $112 million between July 1 and October 9, 2026.
- The partnership reported record operational cash flow with adjusted EBITDA and distributable cash flow that covered the higher payout by about 1.9x, supported by contracted, fee-based midstream assets.
- Attention now turns to how Enterprise Products Partners' distribution coverage may influence the investment narrative and long term income profile for unitholders.
Enterprise Products Partners Investment Narrative Recap
To own Enterprise Products Partners, you need to be comfortable with a midstream operator that leans on fee based contracts, heavy Permian buildout and large scale LPG exports. The short term swing factor is how quickly new gas processing and fractionation projects fill with volumes at acceptable fees. The latest distribution and buyback updates do not materially change that core thesis.
The biggest operational risk still sits in project execution and asset reliability. PDH uptime, returns on roughly US$2.9b to US$3.4b in 2026 growth capex and potential fee pressure from Gulf Coast LPG overcapacity are what could squeeze cash generation, even with current distribution coverage near 1.9x.
The recent 2.8% lift in the quarterly distribution to US$0.56 per unit matters most because it sits on top of record operational cash flow and a distributable cash flow coverage ratio of about 1.9x. For you as an investor, that points to a payout policy that is being tested against real cash generation rather than financial engineering.
That said, the higher payout runs alongside sizeable capex and a balance sheet that already carries meaningful debt. The key question is whether Enterprise Products Partners can keep funding its US$3b area project slate, distribution and periodic unit buybacks without tightening financial flexibility if LPG fees remain soft or new Permian assets scale more slowly than planned.
Enterprise Products Partners is currently modeled around analysts’ assumptions that revenues reach US$67.7b and earnings reach US$7.6b by 2029. This view is built on a forecast 5.0% yearly revenue growth rate and an earnings step up of about US$1.4b from roughly US$6.2b today.
Uncover why Enterprise Products Partners' fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates from the Simply Wall St Community span roughly US$41 to US$93, drawn from 2 different member views, so you are seeing almost a 2x gap in what Enterprise Products Partners might be worth. Those opinions were formed before the latest buyback and higher distribution, so reassess them alongside project execution risks and LPG fee pressure, and compare several alternative viewpoints before leaning on any single narrative.
Explore another Enterprise Products Partners fair value estimate, including one that suggests as much as 153% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Enterprise Products Partners research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enterprise Products Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enterprise Products Partners' overall financial health at a glance.
Looking For More Investment Ideas Beyond Enterprise Products Partners?
Once you have formed a view on Enterprise Products Partners, it can help to cross check that thinking against other income and quality focused opportunities. The Simply Wall St Screener is built for that kind of comparison, letting you filter for traits that match how you like to invest rather than just serving up the usual tickers.
- If you want potential income with some protection on the downside, start with resilient companies screened as 32 resilient stocks with low risk scores that may help smooth out portfolio volatility.
- When value is the priority, compare Enterprise Products Partners with a 33 high quality undervalued stocks that combines balance sheet strength with solid cash generation.
- If you are hunting for under-followed opportunities, broaden your watchlist with a 20 high quality undiscovered gems that already show underlying business quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com