
iFAST (SGX:AIY) Gains Attention From China Tax Shift, Is It Cheap Enough?
China’s new 20% tax on offshore trust income is pushing wealthy investors to rethink where they park assets, putting iFAST (SGX:AIY) and its Hong Kong ePension platform in sharper focus for regional wealth flows.
The iFAST share price at SGD7.93 reflects a mixed picture, with the 3 month share price return down 17.14% and the 1 month move down 9.99%. At the same time, the 3 year total shareholder return of 46.21% contrasts with a weaker 5 year total shareholder return of 13.32%.
Scan how other wealth platforms are positioned for this shift by reviewing the curated list of solid balance sheet and fundamentals (203 results) alongside iFAST.
iFAST now trades at a clear gap to both analyst targets and intrinsic estimates after a sharp pullback. Does that discount signal opportunity, or a fair mark on the risks being priced in?
Most Popular Narrative: 34% Undervalued
At SGD7.93, iFAST trades well below the most followed fair value estimate of about SGD11.97, which leans heavily on its digital banking and ePension rollout to justify that gap.
The ongoing ramp-up and onboarding of trustees for the Hong Kong ePension (eMPF) platform is expected to drive strong and recurring revenue growth in the coming quarters, providing higher margin and operating leverage as onboarding completes and opex efficiencies can be realized. The successful turnaround and scaling of iFAST Global Bank, with rapid growth in customer deposits and the rollout of new products, positions the group to capitalize on sustained demand for digital personal and business banking, expanding both fee and interest income streams and earnings potential.
See why 24 investors see iFAST as 34% undervalued.
Result: Fair Value of SGD11.97 (UNDERVALUED)
Still, the iFAST narrative can crack if Hong Kong ePension costs stay elevated for longer than expected, or if competition squeezes fees from key B2B partners.
Find out about the key risks to this iFAST narrative.
Another View: iFAST Through The Earnings Lens
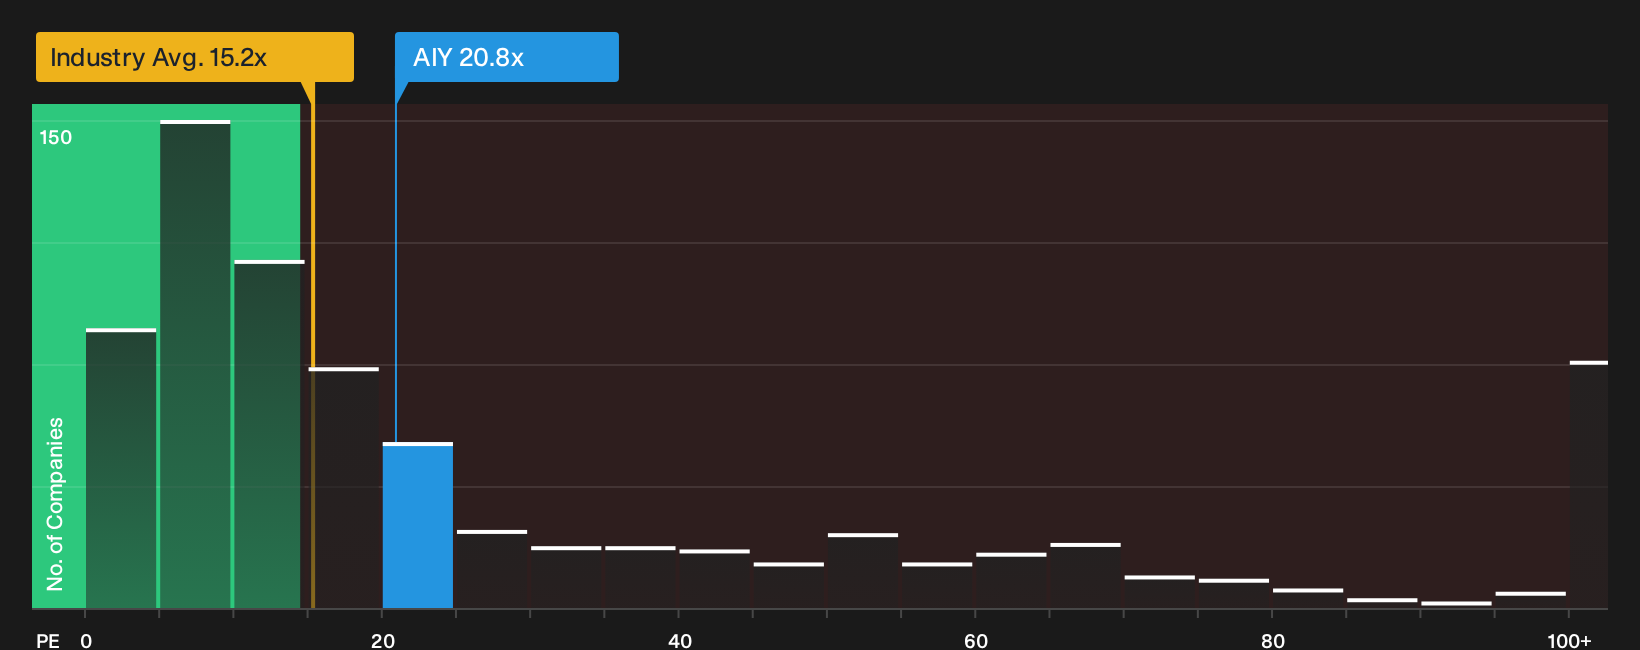
While the DCF work and fair value of about SGD11.82 point to iFAST trading at a discount, the simple earnings multiple tells a tighter story. The shares trade on a P/E of 20.8x, compared with 15.1x for the Asian Capital Markets group and a fair ratio of 17.8x for iFAST.
That premium against both peers and the fair ratio suggests the market already assigns a higher bar to iFAST, which can mean less margin for error if growth or profitability assumptions fall short. Are you comfortable paying a richer multiple when the broader sector and the fair ratio sit lower on the scale?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism runs through the iFAST story, yet the real edge comes from you checking the data yourself and deciding where you stand. To see what those bright spots look like in detail, review the 4 key rewards.
Looking for more investment ideas beyond iFAST?
If you only stop at iFAST, you might miss other opportunities that fit your style. Use the Simply Wall St Screener to widen your watchlist intelligently.
- Hunt for quality at a discount by focusing on companies that screen as 191 high quality undervalued stocks.
- Stack potential income ideas by zeroing in on 213 dividend fortresses that aim to combine yield with resilience.
- Prioritize resilience over thrills by filtering for 233 resilient stocks with low risk scores that aim to balance upside with calmer price swings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com