
Net profit increased by more than 195 times. What is the valuation support of Ganfeng Lithium (01772), which continues to bottom out?
Why can't a “bursting” three-quarter report be exchanged for “positive feedback” from stock prices?
The Zhitong Finance App learned that on October 15, Ganfeng Lithium (01772) released its report for the third quarter of 2026. In the first three quarters, it achieved operating income of 36.159 billion yuan, an increase of 147.24% over the previous year, and net profit of shareholders of 5,012 billion yuan, an increase of 195.4 times over the previous year. The stock price did not rise but fell. The stock price fell rapidly after opening on the next trading day, falling by more than 6% at the close. Since May of this year, its market value has shrunk by more than 70%.
The sharp increase in performance in the first three quarters was due to a rebound in the sales price of lithium series products and an increase in sales of lithium battery products. However, in the third quarter, the price of lithium carbonate fell by more than 20%. The company's revenue and shareholders' net profit were 13.275 billion yuan and 754 million yuan respectively, down from month to month, with net profit falling sharply by nearly 70% from month to month. Up to now, the price of lithium carbonate fell by nearly 20% in the fourth quarter, and the company's results for the next quarter are not optimistic.
However, as the world's largest producer of lithium metal and the largest supplier of lithium compounds in China, Ganfeng Lithium runs through the development of lithium resources, deep processing of lithium salts, lithium metal smelting, lithium battery manufacturing and recycling, and the complete battery chain from mining to battery, and is the most resilient in this round of price pulses. The company's dynamic PE valuation also retreated to around 6 times. As lithium carbonate prices continue to fall, where is the support?
Lithium carbonate is the anchor of valuation, and lithium battery performance exploded in the first three quarters
The Zhitong Finance App learned that the price of lithium carbonate is the valuation anchor for the lithium battery sector. In the second half of 2025, the lithium carbonate market began to rise. It continued to boom in 2026, reaching an annual high of 200,000 yuan/ton in mid-May, more than tripling from the low of 59,000 yuan in June 2025, which also led to a doubling of the performance and valuation of the lithium battery sector. Since June, the price of lithium carbonate has continued to fall. Up to now, it has reached a high point and fell below the 100,000 mark. The lithium battery sector has also followed the correction, and the market value has generally fallen by more than 50%.
Although the price of lithium carbonate fell sharply in the second half of the year, there was still a high year-on-year increase. This also became the price basis for lithium companies' collective profit reversal. According to the forecasts of major lithium battery companies for the third quarter, they all made huge profits.
The performance of the lithium battery industry chain exploded. From October 12 to 15, Xinzhoubang, Salt Lake Co., Enjie Co., Ltd., Jiayuan Technology, Everweft Lithium Energy, and Ganfeng Lithium successively disclosed their performance forecasts for the first three quarters. From upstream lithium salt to midstream materials and downstream batteries, profits increased almost across the board. Among them, Salt Lake shares made the most money in the first three quarters. Net profit from shareholders was 88.4 to 9.05 billion yuan, an increase of 87.96%-92.42%. The highest increase was Ganfeng Lithium, which increased 195.4 times.
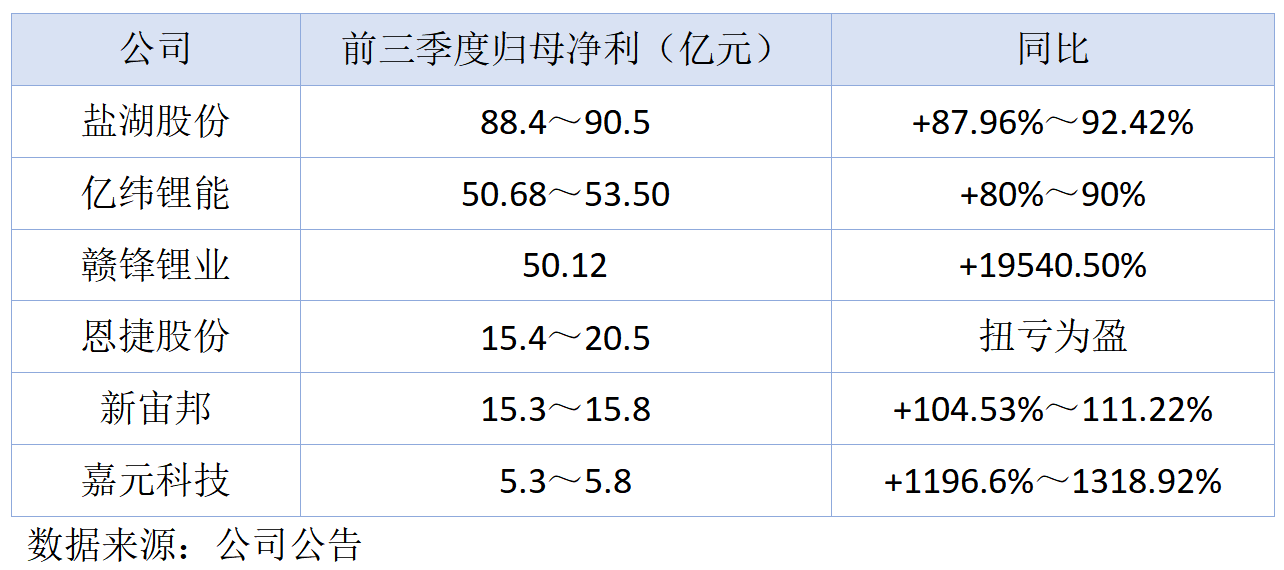
For money in the same cycle, the “way to make money” is different. Salt Lake Co., Ltd. is a two-wheel model of “potash fertiliser+salt lake lithium extraction”; Tianqi Lithium interprets “resources as king” to the extreme. Relying on Greenbush mine and SQM equity income, revenue basically comes from lithium ore and lithium products, which are most flexible when prices rise; Ganfeng Lithium is an uncompromising “player in the whole industry chain”, accounting for more than 60% of lithium metal and lithium compounds, but there is also an additional battery curve accounting for more than 30%.
As a result, it can be seen that in the third quarter, Ganfeng's net profit in a single quarter fell by nearly 70% compared to the second quarter. Tianqi did not announce third quarter results, but the decline is expected to be even greater. Salt Lake fell about 10% month-on-month, and the transmission of lithium price correction from May's high had a big impact on the reports of Ganfeng and Tianqi's two resource-based companies. However, as far as the capital market is concerned, this table only answers “how much money has been earned this time,” and “how long can it be earned” determined by the structure and profit margin.
The market's pricing logic for lithium battery companies is shifting from “flexibility” to “sustainability.” Can Ganfeng Lithium, as a player in the layout of the entire industry chain, withstand this wave of valuation tests brought about by lithium carbonate adjustments?
Valuation logic or “shift”, Ganfeng fell into an “allocation zone”
Ganfeng Lithium has a complete lithium ecosystem. It started with midstream lithium compounds and lithium metal manufacturing, and successfully expanded to the upstream and downstream of the industrial value chain. On the resource side, the company has laid out a global core lithium resource belt, including two major spodumene projects in Australia to develop multiple high-quality lithium salt lake assets in Argentina; on the manufacturing side, lithium compounds and lithium metal production bases cover places such as Fengxin, Yichun, and Sichuan Dazhou in Jiangxi, while the lithium battery business has laid out production lines for power batteries, energy storage batteries, consumer batteries and PACK systems in Xinyu, Jiangxi, Chongqing, and Inner Mongolia.
The company has formed a vertically integrated business model. Its products cover battery-grade lithium carbonate, battery-grade lithium hydroxide, lithium metal, solid-state batteries, etc., which are widely used in applications such as electric vehicles, energy storage, aerospace, functional materials and pharmaceuticals. The industrial chain layout and diversified products make the company's performance grow and resilient. Looking at the revenue structure, the company has formed a two-wheel drive pattern of lithium products and lithium batteries.
The revenue from lithium series products has always been the company's largest revenue source. From 2019 to 2025, business revenue increased from 4.161 billion yuan to 12.876 billion yuan, while the lithium battery and materials business grew even more rapidly, rapidly rising from 603 million yuan to 8.234 billion yuan, and the revenue share continued to rise. In the first half of 2026, the above two product lines accounted for 63.2% and 35.3% of revenue respectively. In addition, the company's lithium resource products accounted for 1.5%.
In the first three quarters of 2026, the two core businesses continued to drive high performance growth and doubled revenue. Net profit of shareholders was 5,012 billion yuan, after deducting non-net profit of 4.636 billion yuan, an increase of 592.14% over the previous year. The “scale” after excluding one-time profit and loss was solid enough. In addition, the financial side is stable, with a balance ratio of 54.91%, continuous net inflow from operating activities, with net cash flow of 2,295 billion yuan, an increase of 634.77% over the previous year. As of September, the company's cash equivalent was 8.96 billion yuan.
It is worth noting that the company's industrial chain is progressing vertically. Among them, on the lithium battery side, the company continued to produce energy storage cells at full capacity in the first half of the year, and the production capacity utilization rate was close to 100%. The construction of a self-developed 588Ah large battery cell production line has begun commissioning and trial production, and it is planned to officially start production capacity climbing in the third quarter of 2026. In the second half of 2026, the price of lithium carbonate declined to reduce the profit margin of lithium salt products, but the self-sufficiency rate will increase dramatically. If upstream prices continue to recover, it is expected that it will increase the share of lithium battery investment and increase the share of lithium battery revenue.
Returning to the capital market, Ganfeng Lithium's Hong Kong stock market value fell 74% from its May high, but it still rose 64% from the starting low last year. The sharp decline in valuation is not an exception; the entire lithium battery sector has also declined sharply. In terms of valuation, the company's PB value is 0.9 times, the dynamic PE value is 6.5 times, and the lithium battery sector is 3 times and 23 times, respectively. Obviously, the company's valuation has fallen into the “allocation zone”. However, Ganfeng's valuation coordinate system is shifting from “cycle stocks” to “growth stocks,” and the closed loop between commercialization and profit for lithium batteries, especially solid-state batteries, has become a core variable in valuation.
From the perspective of investment banks, most of them are pessimistic. For example, the Dahua Jixian Research Report said that the futures contract fell close to a high of more than 200,000 yuan per ton in early September 2026 compared to mid-May, mainly due to the assumption that the market expected supply increased and lowered the average sales price of Ganfeng lithium industry. The target price was drastically lowered from HK$75 to HK$28; however, there are also optimists. For example, Huatai Securities Research Report is optimistic that the company's energy storage capacity expansion and product iteration will go hand in hand to promote the commercialization of solid-state batteries. It has an “gain” rating.
Taken together, the upward cycle of lithium carbonate in the first half of this year brought huge wealth to the lithium battery industry. Performance and valuations exploded one after another, but the fall in prices in the third quarter also caused industry profits to decline sequentially, and valuations shrank sharply. As an industry leader, Ganfeng Lithium has strong support for the current valuation base. The layout of the entire industry chain, dual wheel drive for lithium products and lithium batteries, and the deep cost of integration, as well as the long-term vision of solid state batteries. The price of lithium carbonate continues to affect valuation fluctuations in the lithium battery sector. If the company's valuation-driven logic shifts from “cyclical stocks” to “growth stocks,” the bottom of the valuation may be an opportunity on the left.