
How Earnings Expectations Will Impact Lockheed Martin Stock Investors
- Lockheed Martin recently reported a mix of contract wins, facility expansions and program milestones, including the delivery of a C-130J-30 for conversion into the E-130J Phoenix II TACAMO platform and new long term manufacturing partnerships aimed at scaling missile and munitions capacity.
- These moves highlight how Lockheed Martin is leaning into record backlog and multiyear demand by expanding advanced manufacturing, deepening mission systems integration and tightening international cooperation, which all connect directly to execution risk, cost control and the visibility of long duration defense revenue.
- We will now look at what this means for Lockheed Martin's investment narrative, focusing on the record backlog and the build out of munitions capacity.
See how Lockheed Martin's backlog story fits into a wider defense build out by reviewing a curated group of 41 power grid technology and infrastructure stocks.
Lockheed Martin Investment Narrative Recap
To hold Lockheed Martin, you need to believe its record backlog and long munitions frameworks can turn into sustained cash generation without major stumbles on complex, fixed price programs. The key short term swing factor is execution on ramping PAC 3, THAAD, PrSM and JATM while keeping supply chains and production quality tight.
The biggest risk still sits in cost or technical issues on legacy and classified contracts, which could hit segment margins and temper that backlog story. The latest TACAMO aircraft delivery and broader munitions build out do not change that risk profile, but they do keep the operational focus firmly on delivery.
The Grand Prairie expansion tied to Hadrian looks closest to the heart of the current Lockheed Martin catalyst. Management is spending US$300 million on that facility within an US$8 to 9b munitions build out plan, with new automated machining cells and nearly 6,000 planned US jobs that support higher missile output.
If this automation heavy footprint runs well, it strengthens the case that seven year missile agreements can support better capacity and cost control. If commissioning or integration with Hadrian’s on site cell slips, investors would need to factor rising execution risk into the munitions growth narrative that sits behind the backlog story.
Lockheed Martin's current analyst story ties together a forecast for US$91.4b in revenue and US$8.4b in earnings by 2029. It is built on an assumed 5.9% yearly revenue growth rate and a move from US$6.3b in earnings today to that US$8.4b level, which is an increase of about US$2.1b by the forecast year.
Uncover why Lockheed Martin's fair value indicates a 13% potential upside to its current price that may not last much longer.
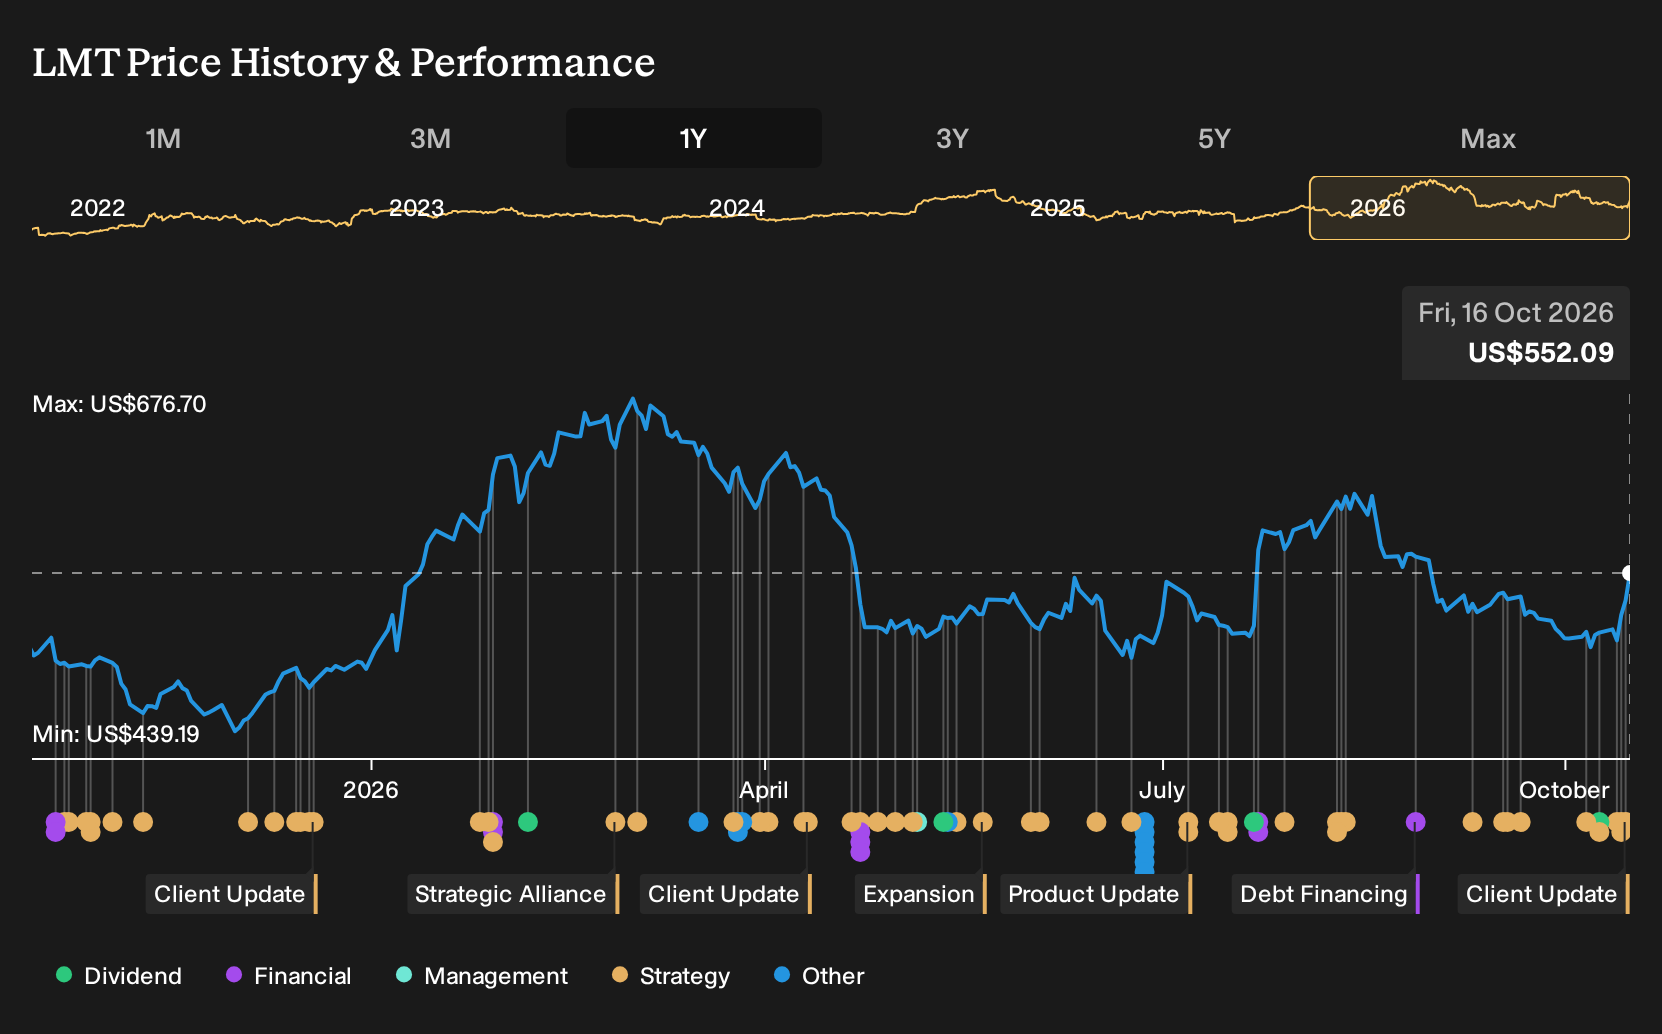
Exploring Other Perspectives
One alternate view focuses on execution risk around Lockheed Martin’s space and interceptor projects. Before this week’s TACAMO delivery and munitions expansion news, the most cautious analysts were penciling in revenue of about US$86.8b and earnings of roughly US$8.1b by 2029. That is a more muted slope than the consensus path, and the gap shows how strongly opinions can diverge. Use it as a prompt to compare several narratives yourself and decide which assumptions fit your own expectations.
Explore 6 other Lockheed Martin fair value estimates, including one that suggests it could be worth just $601.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and forming independent views.
- A great starting point for your Lockheed Martin research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lockheed Martin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lockheed Martin's overall financial health at a glance.
Looking For More Ideas Beyond Lockheed Martin?
Once you have formed a view on Lockheed Martin, it can help to compare it with other opportunities that fit different goals, risk levels, and income needs. The Simply Wall St Screener makes that search faster by surfacing focused sets of companies that match clear financial characteristics.
- If you want to concentrate on quality at a reasonable price, scan through 33 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into their share prices.
- For investors who care most about capital preservation, consider reviewing 32 resilient stocks with low risk scores that the screener filters for more resilient balance sheets and lower overall risk scores.
- If income is a priority, look at 8 dividend fortresses that offer higher yields while still meeting a set of financial strength checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com