
Kuehne + Nagel International (SWX:KNIN) Draws Fresh Analyst Interest, Is The Rally Already Priced In?
Fresh analyst coverage and rising earnings estimates have pushed Kuehne + Nagel International (SWX:KNIN) into the spotlight, as investors weigh strong year to date returns against mixed signals across the wider transportation sector.
Recent trading has backed up that renewed interest. The share price is now at CHF231.8, with a 30-day share price return of 6.67% and a year to date share price gain of 33.22%. The 1 year total shareholder return of 55.50% contrasts with a flat 5 year total shareholder return, which indicates that strong momentum has only emerged more recently.
Scan how Kuehne + Nagel International’s momentum compares with other logistics and transportation plays by reviewing the hand picked list of solid balance sheet and fundamentals (203 results) in today’s market.
Bulls point to Kuehne + Nagel International’s earnings upgrades and sector beating run. Bears see a fully priced logistics leader. Which story do the current valuation markers lean toward as you price in that recent surge?
Most Popular Narrative: 13% Overvalued
Kuehne + Nagel International closed at CHF231.8, while the most followed narrative pegs fair value at CHF204.78. As a result, the recent rally sits above that framework and puts more weight on whether earnings and margins can live up to optimistic assumptions.
The main thing that has to go right is that AI productivity programs, structural cost reductions and mix shift toward tech, semicon, healthcare and aerospace continue to offset pressure in Sea Logistics and early-stage margin dilution in Contract Logistics.
The view that Kuehne + Nagel International is fairly valued and has a positive outlook implies that the current share price already reflects both ongoing earnings upgrades and the risk that Sea Logistics margins and airfreight-related free cash flow remain volatile.
See why 31 investors see Kuehne + Nagel International as 13% overvalued.
Result: Fair Value of CHF204.78 (OVERVALUED)
Still, the story of Kuehne + Nagel International can weaken if Sea Logistics pricing stays soft or if Contract Logistics margins remain under pressure for longer than analysts expect.
Find out about the key risks to this Kuehne + Nagel International narrative.
Another View: Kuehne + Nagel International Through Cash Flows
The analyst narrative frames Kuehne + Nagel International as 13% overvalued on a fair value of CHF204.78. Our DCF model points in a different direction. Based on future cash flows, the shares are assessed at CHF323.57, which implies the current CHF231.8 level screens as undervalued.
The gap between a DCF-based view and the analyst target raises a straightforward question: Which set of assumptions do you consider more reasonable as Sea and Contract Logistics work through their margin pressures, the market’s caution or the cash flow model’s optimism?
Look into how the SWS DCF model arrives at its fair value.
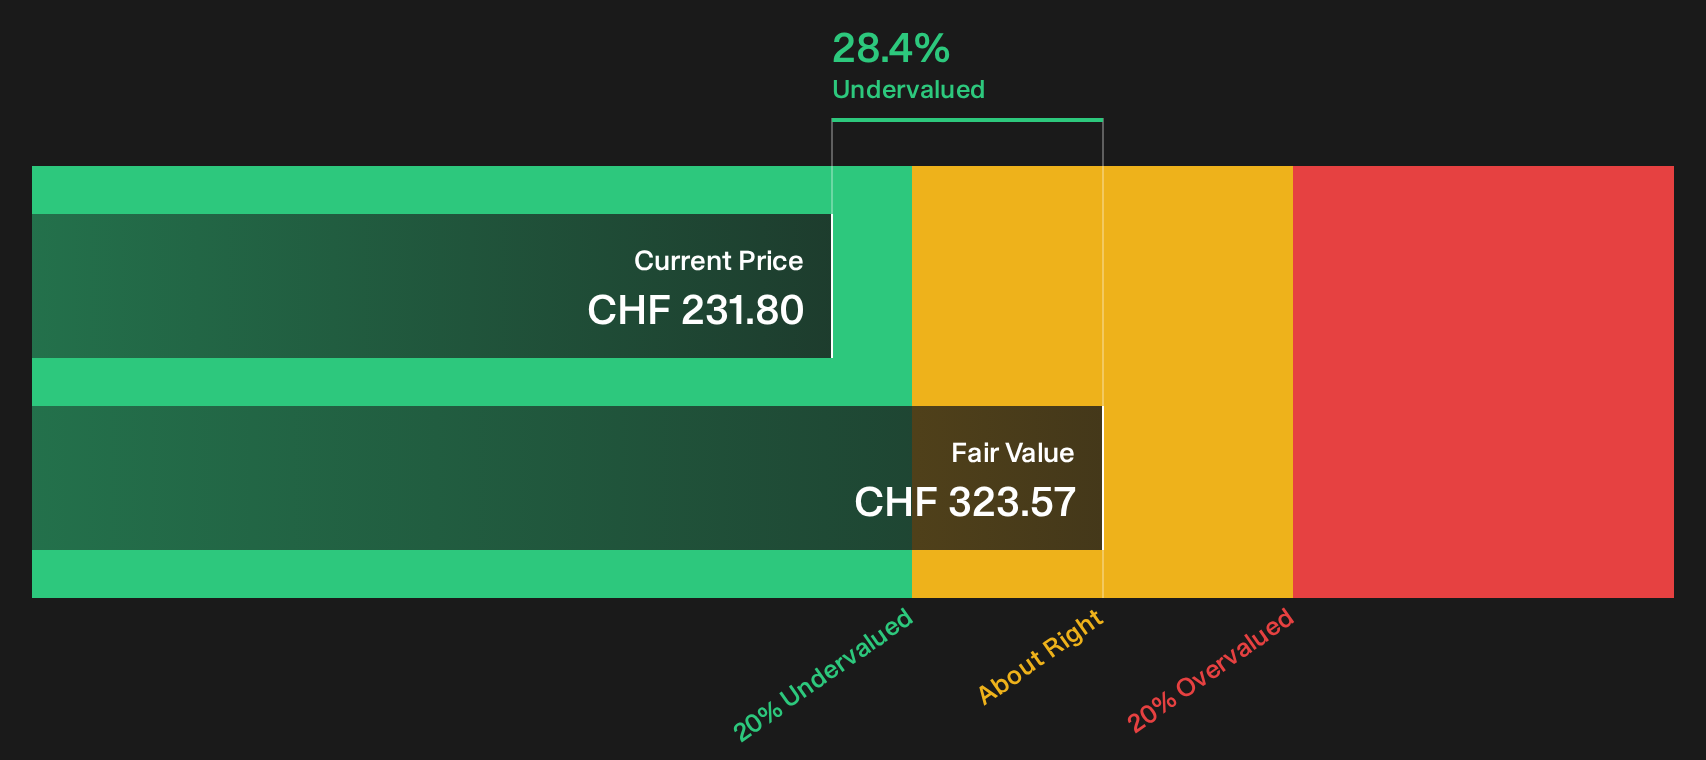
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kuehne + Nagel International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around valuation can tilt sentiment either way, so move quickly, review the detailed numbers, and weigh both the 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Kuehne + Nagel International?
If you stop with Kuehne + Nagel International, you risk missing other opportunities that could fit your goals even better. Widen your search using focused stock lists instead.
- Target resilient compounding potential by reviewing companies screened as 191 high quality undervalued stocks that combine quality fundamentals with prices the market may not fully appreciate yet.
- Strengthen your income stream and stress test payout reliability by scanning the stocks grouped as 214 dividend fortresses for robust yields backed by solid profiles.
- Prioritise capital protection and sleep better at night by starting with the curated 233 resilient stocks with low risk scores that highlight businesses with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com