
Compañía De Minas BuenaventuraA (BVN) Cuts San Gabriel Guidance, Is The Pullback Already Priced In?
Compañía de Minas BuenaventuraA (BVN) just put fresh production numbers on the table for the third quarter and year to date, along with updated 2026 guidance that hinges on San Gabriel's gold output constraints.
Investors have been reminded how sensitive Compañía de Minas BuenaventuraA can be to operational headlines, with the 1 day share price return falling 2.34% to US$30.42 after the San Gabriel update, even though the 1 year total shareholder return of 23.02% sits on top of a very large 3 year gain of about 3x.
Scan how Compañía de Minas BuenaventuraA stacks up against peers by reviewing hand picked 36 elite gold producer stocks with scale, diversified mines, and similar production stories.
The question now is simple: Is this pullback in Compañía de Minas BuenaventuraA a clear reflection of San Gabriel's constraints, or primarily a reset in sentiment that the valuation already incorporates?
Most Popular Narrative: 19% Undervalued
Against a last close of $30.42, the most followed narrative pegs Compañía de Minas BuenaventuraA’s fair value at $37.53. This frames this pullback as a move that still sits inside a wider undervaluation debate.
The ongoing ramp-up of the San Gabriel project, with management now targeting throughput of 2,000 tonnes per day by 3Q 2026 and 3,000 tonnes per day by the end of 2027, along with a step up in gold recoveries toward about 70% by late 2026 and 85% by late 2027 after installing a flotation circuit, could support higher gold volumes and improved net margins.
See why 20 investors see Compañía de Minas BuenaventuraA as 19% undervalued.
Result: Fair Value of $37.53 (UNDERVALUED)
Still, this narrative around Compañía de Minas BuenaventuraA can break if San Gabriel’s longer ramp, rising capex and cost inflation squeeze free cash flow harder than expected.
Find out about the key risks to this Compañía de Minas BuenaventuraA narrative.
Another View: Cash Flows Paint A Tougher Picture
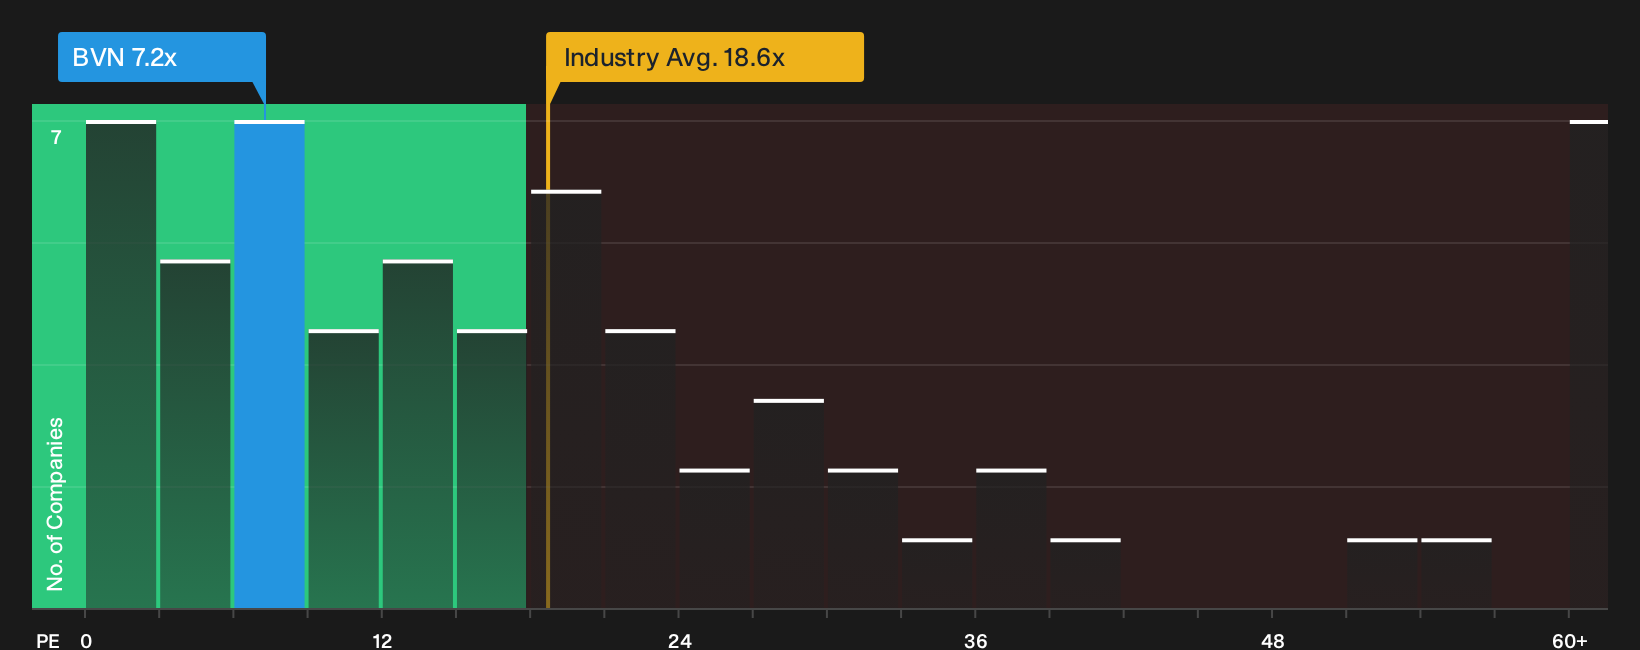
On price multiples, Compañía de Minas BuenaventuraA looks inexpensive, with a P/E of 7.2x compared with a fair ratio of 15.8x and an industry average of 18.6x. That gap suggests the market is either cautious about future earnings quality or leaving room for potential upside. Which side do you think it reflects?
To see how this earnings based view compares with a fuller valuation framework, including peers and that fair ratio, take a look at See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Compañía de Minas BuenaventuraA for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed message or clear signal? If Compañía de Minas BuenaventuraA appears finely balanced between concern and optimism to you, consider acting promptly and testing that view against the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Compañía de Minas BuenaventuraA?
If this update on Compañía de Minas BuenaventuraA sharpened your thinking, do not stop here. Broaden your watchlist with fresh, high conviction ideas uncovered by data.
- Target forward looking value by scanning a focused set of 33 high quality undervalued stocks that combine compressed pricing with solid underlying fundamentals.
- Anchor your portfolio’s income stream by reviewing a curated pool of 8 dividend fortresses built around durable, higher yielding payouts.
- Strengthen downside protection by filtering for 32 resilient stocks with low risk scores where balance sheets, earnings quality, and business profiles point to greater resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com