
How New Bond Issues At DBS Group Holdings (SGX:D05) Have Changed Its Investment Story
- DBS Group Holdings recently completed two US$500 million senior unsecured fixed-rate Eurobond issues maturing in 2029 and 2031, alongside a US$500 million floating rate note due 2029, each priced at 100% of principal.
- The mix of fixed and floating US$ funding across multiple maturities gives DBS Group Holdings added flexibility in managing its funding costs and balance sheet structure across different interest rate conditions.
- The next point of interest is how DBS Group Holdings' new US$1.5 billion funding program fits into the existing investment narrative.
Scan how DBS Group Holdings’ latest bond issues compare with other funding focused opportunities by reviewing the hand picked 233 resilient stocks with low risk scores shaping the market right now.
DBS Group Holdings Investment Narrative Recap
To own DBS Group Holdings you need to be comfortable with a large Asian bank that leans heavily on wealth management, transaction services and a broad regional footprint. The recent US$1.5b of new bonds mainly speak to funding diversification rather than a shift in that core story, so they do not materially change the near term thesis.
The key short term swing factor remains how net interest margins hold up as deposit growth, regulatory hedges and rate trends interact. The biggest current risk is ongoing regulatory pressure and capital requirements, which can absorb balance sheet capacity and limit how aggressively DBS Group Holdings can grow loans or return capital.
The fresh 5.284% and 5.491% senior unsecured notes, both issued at 100% of principal, are the clearest reference point for this development. Those bonds extend DBS Group Holdings’ US dollar curve out to 2029 and 2031, which gives a clearer read on its wholesale funding cost and duration profile in hard currency.
For catalysts, the relevance is practical. Stable term funding in US$ supports cross border corporate banking, transaction services and wealth-related lending that analysts already flag as important drivers. The trade off is that higher fixed coupons can weigh on funding costs if rate cycles move against the bank, which matters for margins and earnings resilience.
DBS Group Holdings' current analyst narrative points to revenues of SGD 27.1b and earnings of SGD 13.0b by 2029, based on a forecast revenue growth rate of 6.7% a year, compared with earnings today of SGD 10.9b. This implies an earnings increase of about SGD 2.1b by that forecast year.
Uncover why DBS Group Holdings' fair value indicates a 6% potential downside to its current price, which leaves little room for error.
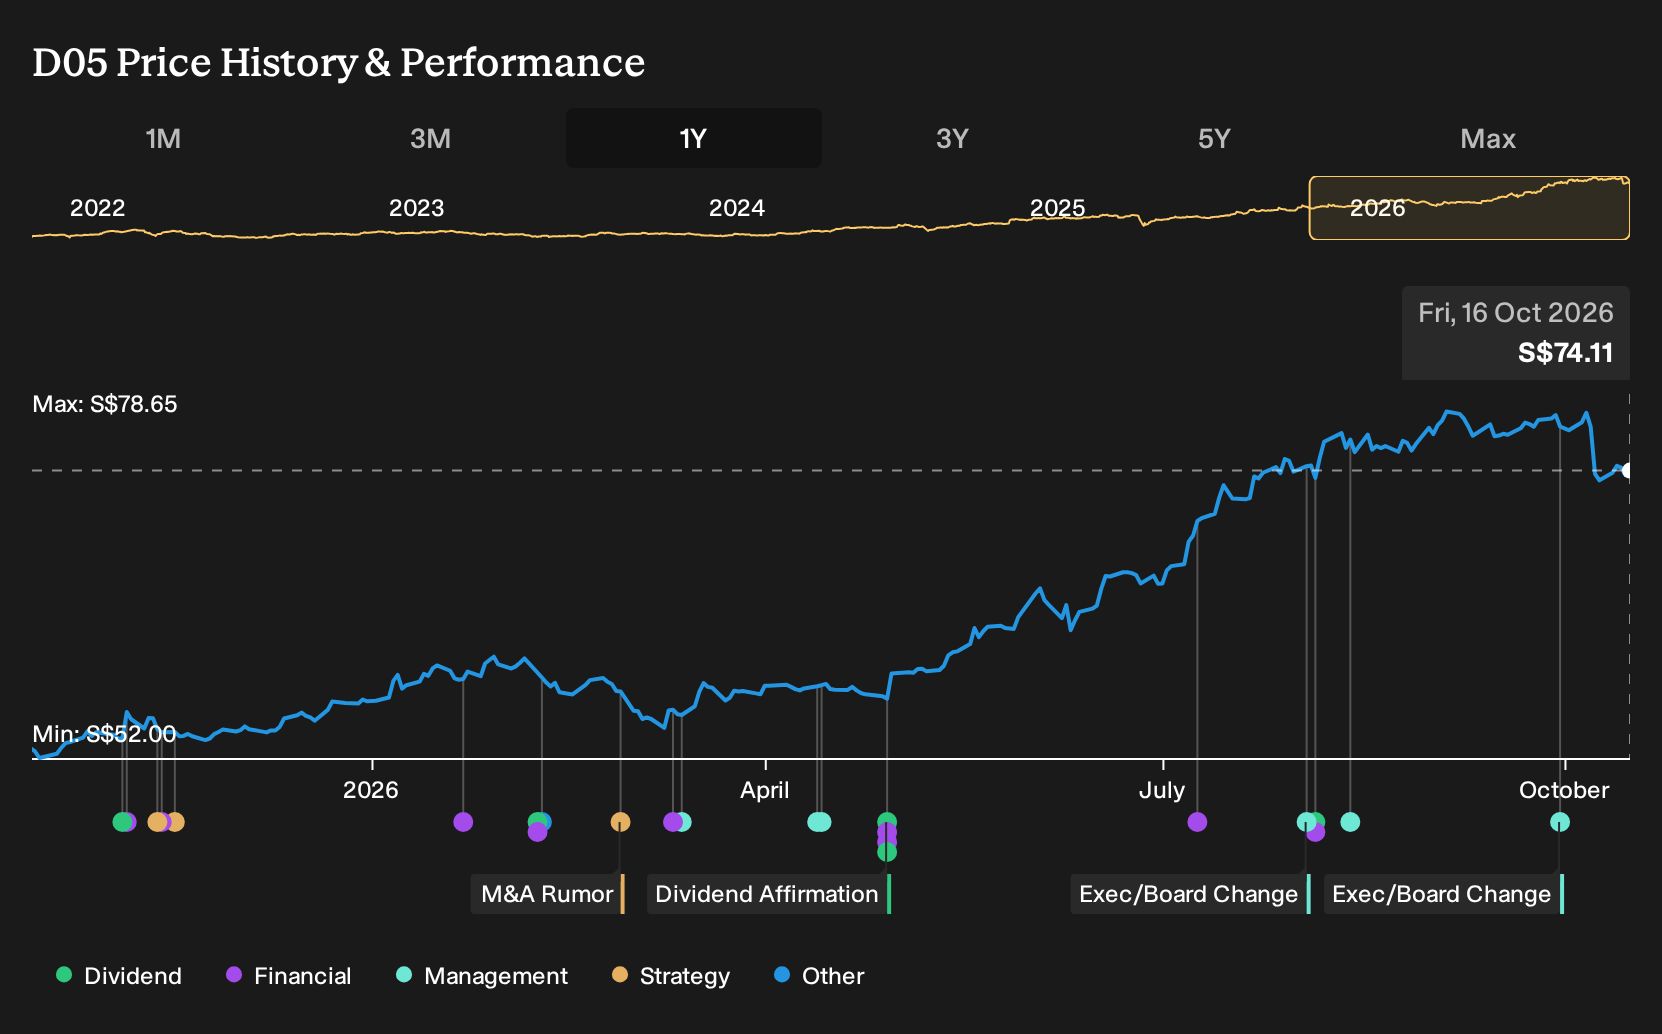
Exploring Other Perspectives
You might focus on regulatory risk for DBS Group Holdings, yet the most optimistic analysts were leaning hard into fee income growth before this bond deal. They were pencilling in revenue of about SGD 29.1b and earnings of roughly SGD 14.5b by 2029, versus more cautious SGD 27.1b and SGD 13.0b views. Those projections were all set before this new US$1.5b funding move, so treat them as starting points rather than the final word. Use this spread in expectations as a reminder to compare several narratives before deciding how this funding step fits your own view.
Explore 3 other DBS Group Holdings fair value estimates, including one that suggests as much as 24% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DBS Group Holdings research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DBS Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DBS Group Holdings' overall financial health at a glance.
Looking for more DBS Group Holdings style ideas?
Once you have a view on DBS Group Holdings, it can help to widen the lens and compare it with other companies that fit different risk and income profiles. The Simply Wall St Screener lets you do that quickly by filtering for balance sheet strength, value, or income themes that suit your own approach.
- If capital preservation is high on your list, start with a curated set of 233 resilient stocks with low risk scores that aim to keep drawdowns in check while still offering equity exposure.
- For investors hunting for value opportunities, there is a focused group of 191 high quality undervalued stocks that pair stronger fundamentals with more modest pricing.
- Income focused readers can zero in on companies with robust cash returns through a hand picked selection of 214 dividend fortresses that put yield front and centre.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com