
Missed CNOOC's Run? What Holders Had To Believe
CNOOC’s interim 2026 update put one concrete marker on the table. The group moved Brazil’s Buzios 8 into production while booking record first half profit and a richer interim dividend. For CNOOC shareholders, the return over the past year was 36.6%, including dividends. If you were weighing a purchase back on 16 October 2025, what did you need to believe about reserve projects, Asia Pacific demand and energy transition risk for that outcome to feel reasonable?
CNOOC has already moved. See which of 191 high quality undervalued stocks still trade below our estimates.
The Argument CNOOC Investors Were Really Having
The shares cost HK$18.96 at the start of the period, and anyone looking at CNOOC then was really choosing between two clear stories.
The bullish narrative pointed to a Fair Value of HK$22.46, a price that would only make sense if revenue grew 1.8% with profit margin holding near 32.3% and a future P/E of 9.4x. That view leaned on aggressive reserve investment and steady Asia Pacific energy demand.
The bearish script anchored on a Fair Value of HK$10.59 and focused on global decarbonization risk. This case treated rising renewables, ESG pressure and sanctions as serious threats to CNOOC’s hydrocarbon portfolio and international funding access.
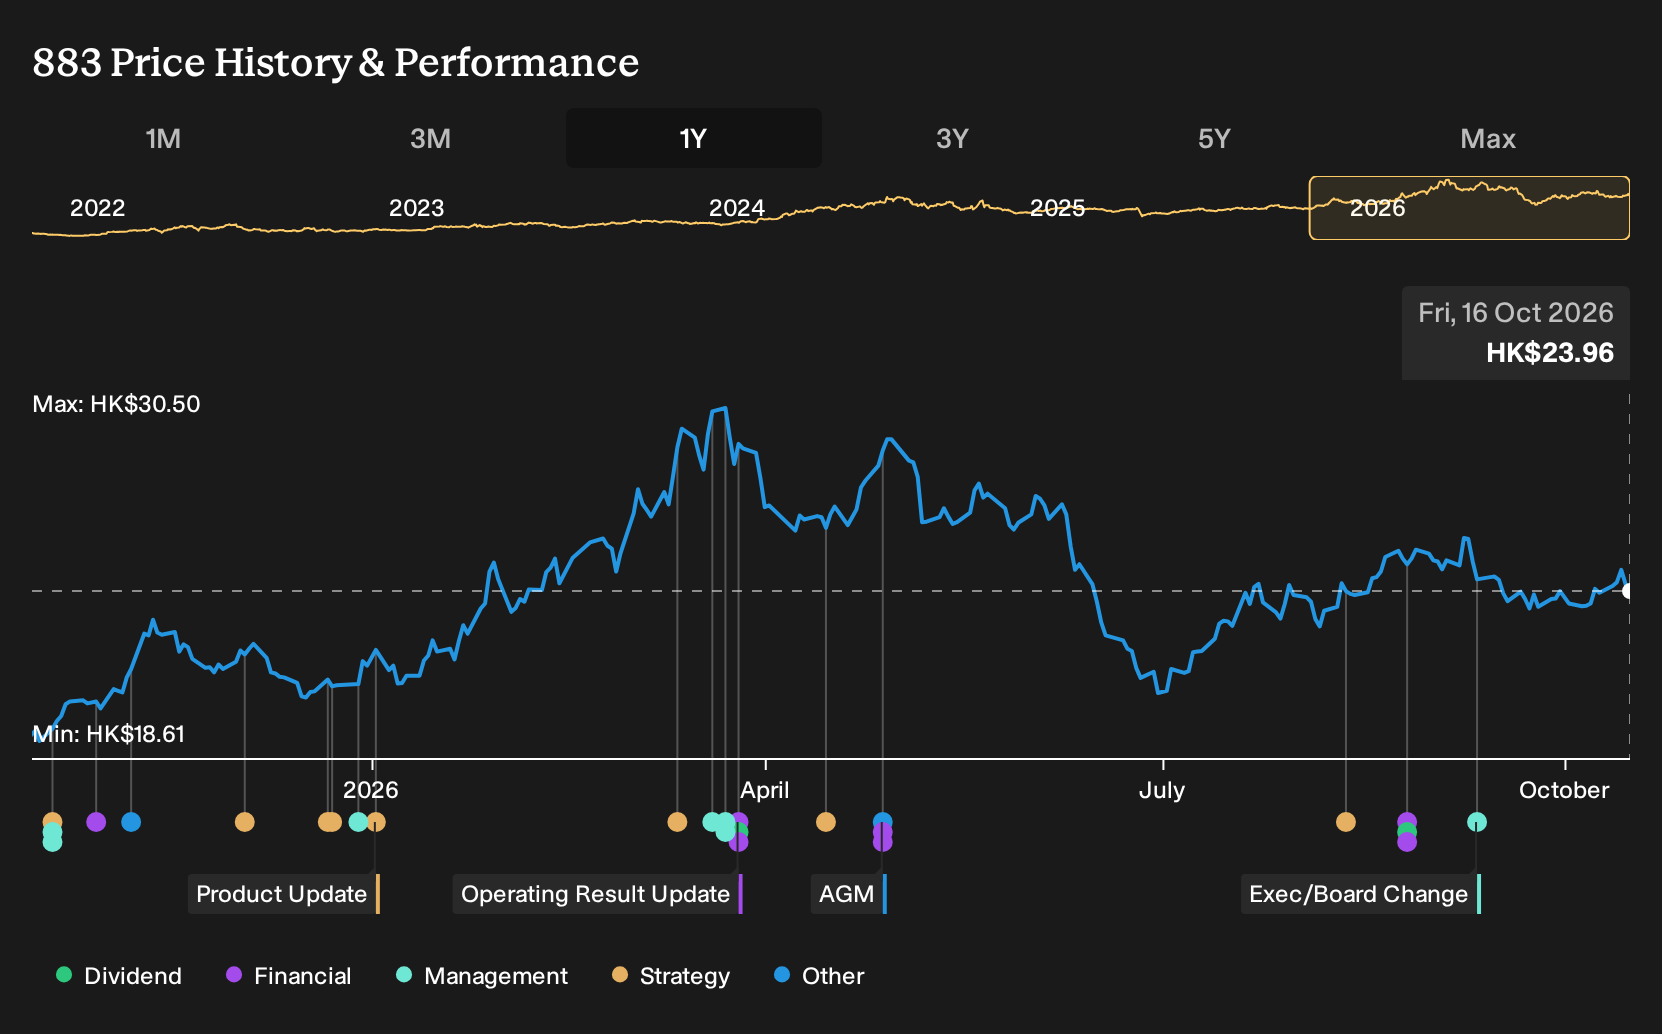
What The 2026 Results Did To The CNOOC Debate
CNOOC’s interim 2026 numbers put hard data behind the bullish script. Revenue reached ¥126.6b in Q2 2026, up from ¥100.8b a year earlier, while net income rose from ¥32.97b to ¥46.67b and net margin widened from 32.7% to 36.9%. Record first half profit, higher oil and gas sales, new discoveries and Buzios 8 coming onstream all leaned toward the optimistic reserve and demand case. Ongoing ESG and policy concerns still kept the cautious story alive, so the evidence cut both ways.
The lesson is simple. When a thesis hinges on reserves, project delivery and margin resilience, you test it against production volumes, new field startups and the reported net margin line. Use those figures to cross check any CNOOC style growth story at another producer, rather than relying on sentiment or macro headlines.
What Today’s CNOOC Price Already Assumes
CNOOC now trades at HK$23.96, up from HK$18.96 over the past year. The selected Narrative’s Fair Value sits below the current price, which implies its author treats today’s level as already baking in strong recent delivery.
The argument focuses on whether current cash generation, new fields and higher spending can still translate into durable earnings. A buyer at today’s price has to judge that CNOOC converts heavier capex and transition exposure into sustained profit rather than thinner margins over time.
"The main thing that has to go right is that CNOOC converts its current wave of new projects, rising production and high cash generation into durable earnings and dividends despite higher capital spending and transition risks. The current view that CNOOC is fairly valued and bearish implies the share price already reflects strong recent profits and record dividends alongside material long term transition and geopolitical headwinds."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 34% below our estimate - expands fee earning real asset funds by tapping tax efficient retail capital sources.
- Company 2 - 31% below our estimate - builds AI centric peripherals and services for an expanding enterprise collaboration customer base.
- Company 3 - 45% below our estimate - converts a technology and industrial backlog into data center focused modular electrical projects.
That is three of the list. See every one of the 203 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com