
FormFactor Is Up 150%, But The Story Isn't Finished
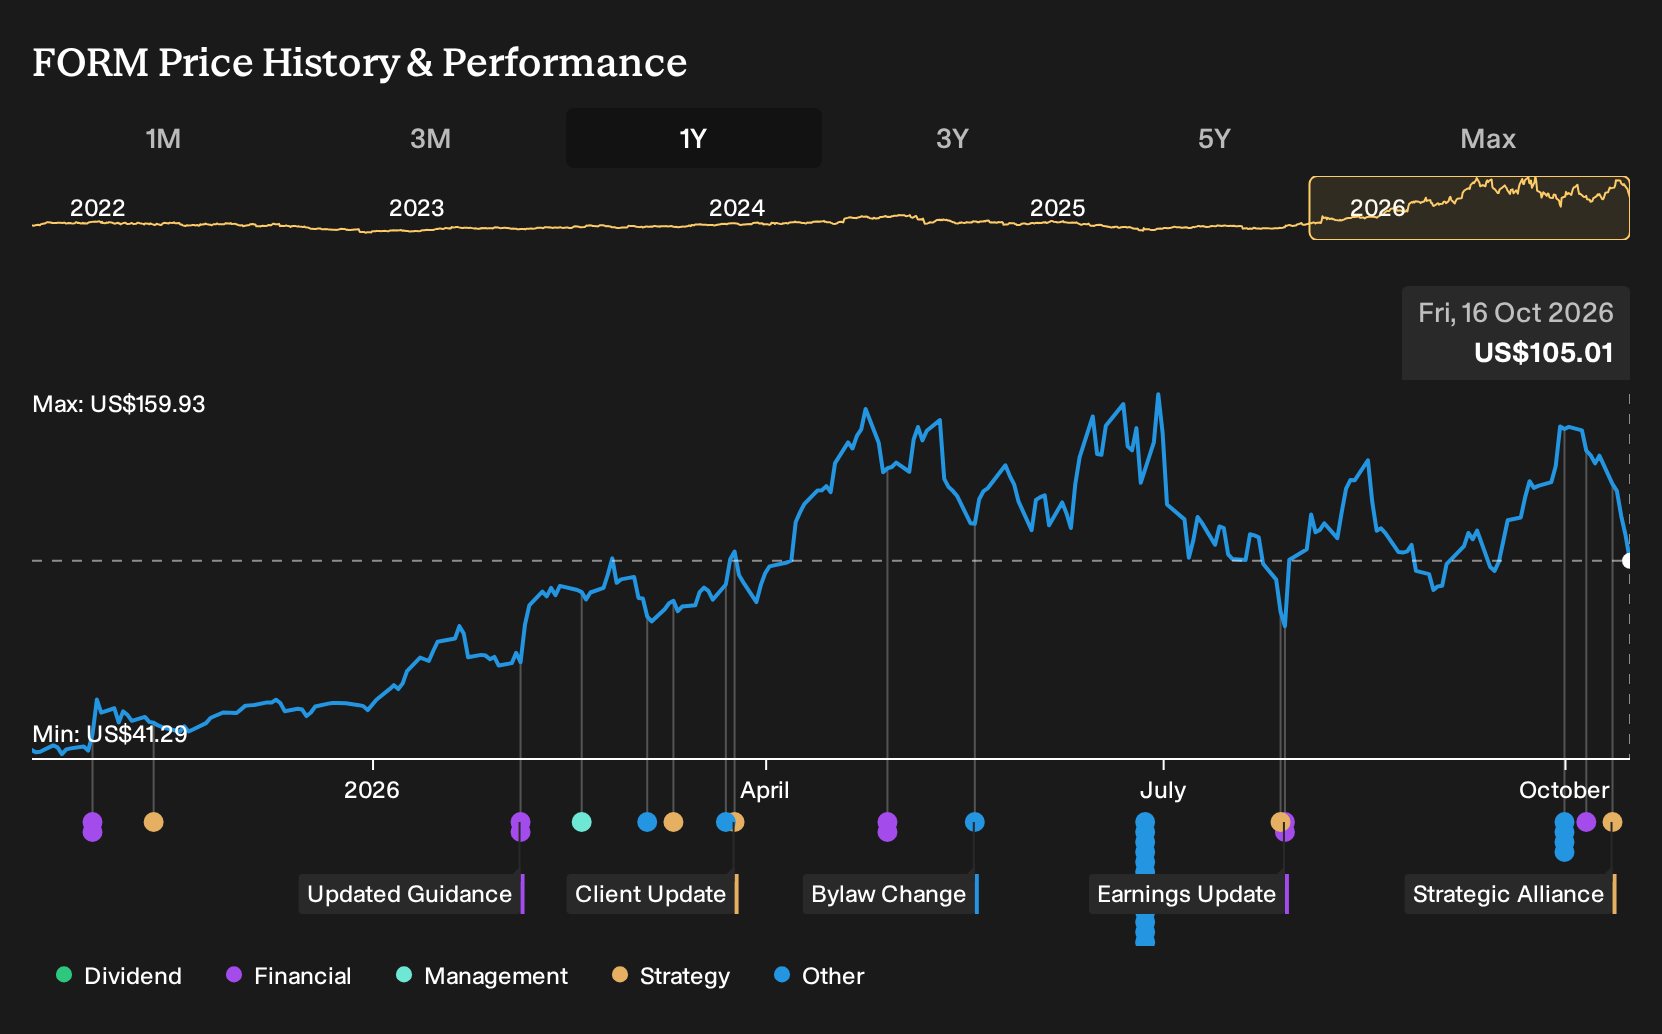
If FormFactor sat on your watchlist instead of in your portfolio, the outcome may feel painfully expensive. Holding FormFactor over the past year would have returned 149.7%, including dividends. That kind of move naturally raises a question. Back on 16 October 2025, when analysts debated whether AI driven chip testing could justify more capacity and higher margins, what specific assumptions about high bandwidth memory probe card demand might have helped you recognize the potential before it appeared in the share price?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
FormFactor has already moved. Pinpoint other ways to investigate the theme among 55 AI infrastructure stocks.
The Argument You Would Have Been Weighing Up On FormFactor
The shares cost US$41.9 at the start of the period, so any view on FormFactor needed to start with what analysts thought that price already implied.
The bullish narrative put fair value at US$45. It was built on the idea that high bandwidth memory probe cards and broader AI related testing could support an aggressive capacity build out, with the HBM market described as capable of doubling the size of the company.
The bearish view anchored fair value at US$23 and stressed that a heavier tilt toward lower margin DRAM products, together with rising tariffs and higher capital spending, could hold back profitability even if sales increased.
What The Results Changed For The FormFactor Thesis
FormFactor’s Q2 2026 report showed revenue of US$258.2 million and net income of US$56.2 million, with net margin at 21.8% versus 4.6% a year earlier. Record sales tied to high bandwidth memory and broader AI testing clearly backed the bullish focus on capacity, mix improvement, and earnings leverage. Sector wide selloffs during the period kept the cautious view on cyclicality in play, so the evidence cut both ways.
The hinge assumption was whether extra HBM and AI demand would flow through to margins, not just sales. When testing a different stock, track net margin alongside top line growth and ask whether new capacity, product mix, and pricing are actually widening that percentage or simply adding more low quality volume.
What FormFactor’s Run Already Prices In
FormFactor now trades at US$105, and this Narrative’s Fair Value sits below that level. The view is that a rich P/E, tight flexibility during heavy Farmers Branch spending, and reliance on higher value HBM and systems mix all crowd the margin of safety.
Anyone paying today’s price is effectively assuming that elevated margins and dense test demand for advanced packaging, GPUs, and co packaged optics can outlast temporary supports. The question is how the risks around tariff refunds, metal reclaim, and Texas ramp costs affect that assumption.
"The numbers imply that FormFactor’s share price embeds a rich valuation multiple relative to semiconductor peers, which leaves limited room for error if growth or margin expansion underperforms these expectations."
The price and this Narrative do not agree. → Uncover what this Narrative says FormFactor is actually worth
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 39% below our estimate - expands payment routing that lets large online platforms reach diverse local tender options.
- Company 2 - 26% below our estimate - scales injectable therapies targeting diabetes and weight management across expanding patient populations.
- Company 3 - 41% below our estimate - rebuilds a payments platform and digital tools to strengthen fee-based customer relationships.
That is three of the list. See all 33 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com