
Novo Nordisk (NVO) Stock May Be Undervalued As Buybacks Continue
Novo Nordisk has seen its stock lose ground in recent years, even as headlines focus on new treatments and an active share repurchase programme. That gap between the share price story and the earnings power of the business raises a clear question for you as an investor: whether today's valuation can be explained by what the company earns.
- The share price has fallen 57.1% over the past 3 years, which puts the spotlight squarely on whether current earnings are being priced too cautiously or still reflect high expectations.
- The ongoing plan to repurchase up to DKK 15b of stock may support earnings per share over time, since the same profit can be spread across a smaller pool of shares.
- There is a second opinion on Novo Nordisk worth weighing. See what analysts think Novo Nordisk's shares could be worth.
The issue now is whether Novo Nordisk's current share price is justified by its earnings when compared with the Fair Ratio benchmark.
If you want a wider lens on stocks where price and earnings are both in focus, a targeted screener of 33 high quality undervalued stocks.
Does Novo Nordisk Look Undervalued on Earnings?
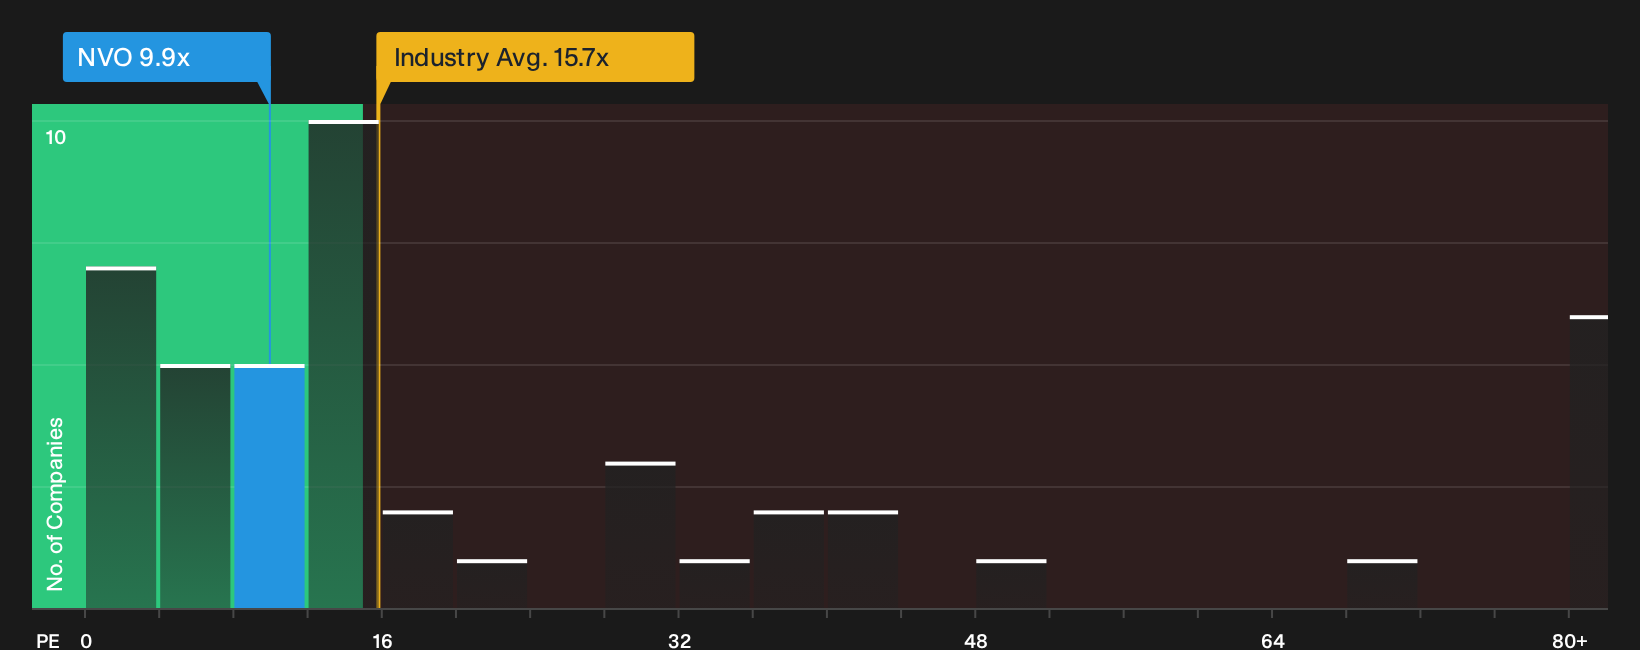
The P/E ratio suits Novo Nordisk because earnings are a key focus for investors in large, established pharmaceuticals. Novo Nordisk currently trades on a P/E of 9.9x, which is well below the Pharmaceuticals industry average of 15.7x and far under the peer group at 58.5x. On a simple earnings multiple, the market is pricing each dollar of profit at a discount to both the wider sector and similar stocks.
The Fair Ratio, which aims to reflect what a more tailored P/E might look like once growth prospects, margins, scale and risk are weighed, also sits above the current 9.9x figure. This framework points toward the shares looking undervalued on earnings. Because the share price has fallen sharply from its peak even as Novo Nordisk continues a DKK 15b repurchase programme, the low P/E suggests recent caution has not fully closed the gap implied by this model. Explore the numbers behind Novo Nordisk's P/E valuation.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Novo Nordisk's Simply Wall St Narratives pick up where this valuation puzzle leaves off. They spell out which combinations of future growth, profitability and earnings power would need to hold for the stock to be worth meaningfully more or less than today’s price. Each one treats fair value as a thesis about Novo Nordisk's business that you can keep tracking over time rather than a one off snapshot.
One of the top community narratives on Novo Nordisk: 59% undervalued
"Current sentiment has swung deeply negative, but expectations are now low, and the embedded upside is material…"
Discover why this Narrative puts Novo Nordisk at 59% undervalued.
Before you act on Novo Nordisk's valuation, there is one more piece to consider
Price and earnings only tell part of the story for Novo Nordisk, since internal checks have also highlighted potential pressure points that could matter for future risk and reward. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com