
Cimpress (CMPR) Backs Earth Brands, Is The Packaging Push Already Priced In?
Cimpress (NasdaqGS:CMPR) just led a US$10 million funding round in Earth Brands, tying its mass customization platform more tightly to American made, sustainability focused packaging for food service customers.
The Cimpress share price has pulled back sharply over the last three months, with a 90 day share price return down 25.86%, even though the year to date share price return is up 16.13% and the 1 year total shareholder return is 17.31% including dividends. Recent announcements, including the Earth Brands funding and the upcoming Q1 FY2027 Q&A call on 29 October 2026, arrive while momentum is fading in the near term. This can signal that investors are reassessing both growth potential and risk around Cimpress's expanding custom packaging push at a US$76.25 share price.
Scan beyond Cimpress and this packaging pivot by reviewing a curated set of resilient printers and customization players in our list of solid balance sheet and fundamentals (25 results), which might handle similar shifts in demand.
Cimpress now trades well off its recent highs even as it leans harder into custom, sustainability focused packaging. Does that pullback leave enough upside potential to justify the risks at today's valuation?
Most Popular Narrative: 33% Undervalued
Cimpress is pinned by the most followed narrative as worth $114.5 per share, compared with the recent $76.25 close, which puts cost savings, mix shift and small business cohorts in the spotlight.
Cimpress is targeting US$70 million to US$80 million of total cost savings from efficiency projects between fiscal 2026 and fiscal 2028, with manufacturing and supply chain changes, shared tech platforms and AI driven simplification expected to support adjusted EBITDA expansion and stronger net margins as these savings flow through.
See why 3 investors see Cimpress as 33% undervalued.
Result: Fair Value of $114.5 (UNDERVALUED)
Still, the Cimpress story can break if cost savings from AI and shared production fall short, or if higher value categories fail to offset weaker legacy print demand.
Find out about the key risks to this Cimpress narrative.
Another Angle On Cimpress Valuation
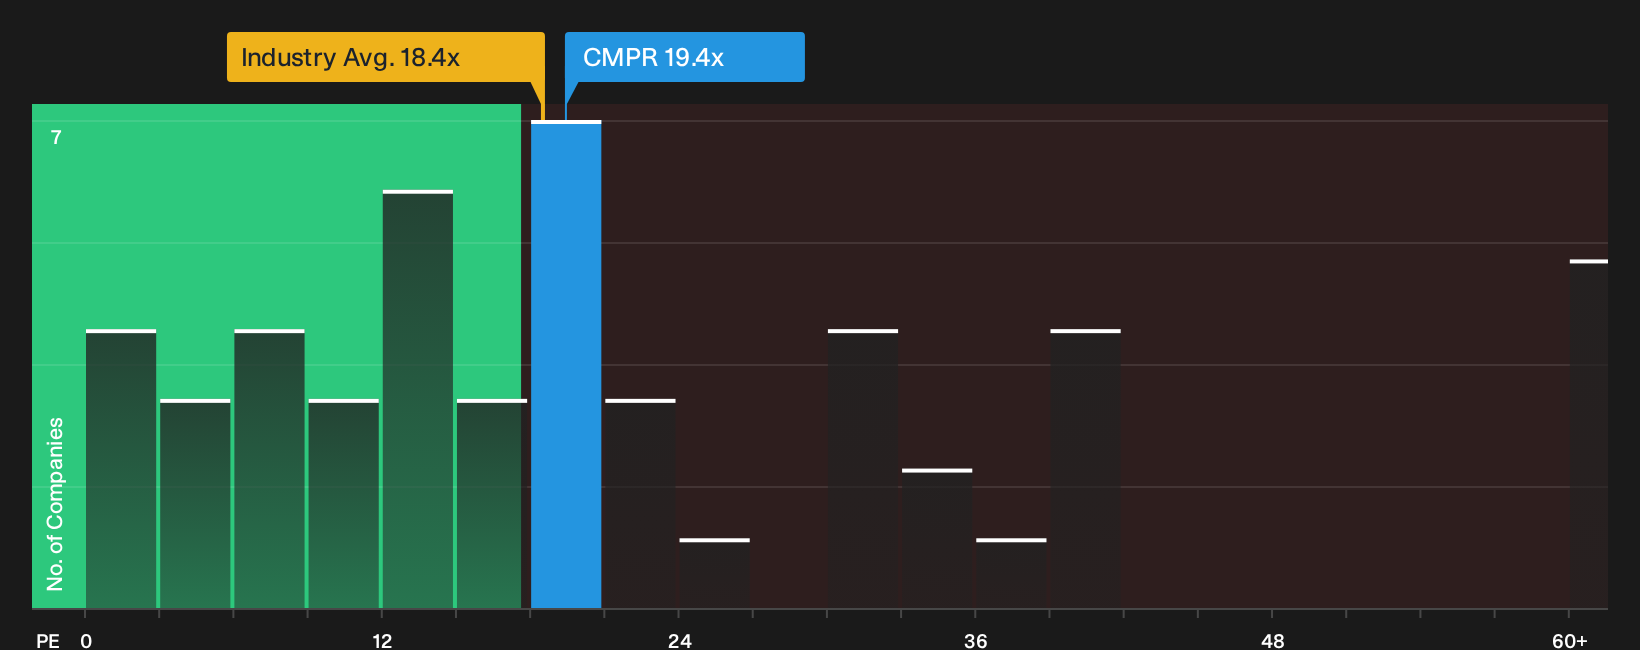
That $114.5 fair value hinges on analyst forecasts and future profitability. A quick check against current pricing multiples tells a more cautious story. Cimpress trades on a P/E of 19.4x, which is higher than both the US Commercial Services industry at 18.6x and its peer group at 14.9x.
The fair ratio for Cimpress sits at 20.7x, only slightly above today’s 19.4x, so the room for rerating on this measure alone looks limited and leaves less margin for error if earnings or sentiment soften. Which lens do you trust more when pricing the risk around this pullback: the narrative fair value or what comparable companies are trading on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Cimpress leaves you undecided, move quickly to review the data directly, then weigh both sides with 3 key rewards and 2 important warning signs.
Looking for more Cimpress-sized investment ideas?
If Cimpress has sharpened your focus on pricing, do not stop here. Cast a wider net and compare it with fresh ideas that fit your risk and income goals.
- Target potential mispricings by lining up Cimpress against companies screened for quality and value using the 33 high quality undervalued stocks.
- Lock in income candidates by weighing Cimpress beside resilient payers in the 8 dividend fortresses.
- Reduce portfolio stress by pairing Cimpress with steadier businesses from the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com