
Insurance Deal Might Change The Case For Investing In Howard Hughes Holdings Stock (HHH)
- Howard Hughes Holdings is reshaping its model after acquiring insurance firm Vantage for US$2.1b and reporting a Q2 revenue result that far exceeded analyst expectations, while also realigning leadership in its Texas master planned communities.
- The push to pair an insurance platform with fee-based capital from third party partners marks a shift away from pure real estate exposure toward a multi engine business.
- The focus now turns to how this move toward an insurance centric holding structure could reshape Howard Hughes Holdings' investment narrative.
Howard Hughes Holdings Investment Narrative Recap
To own Howard Hughes Holdings, you need to believe the real estate engine in its master planned communities can keep throwing off cash while an insurance platform gets built alongside it. The Vantage acquisition, and the plan to put US$2.5b to US$3b into that unit, makes the near term story about execution and integration rather than just land and rent.
The strongest short term catalyst is whether the recent Q2 revenue beat can translate into steadier earnings from recurring MPC and operating asset income while the insurance arm scales. The main risk right now is simple. Management is stretching into a complex, regulated business while still carrying US$5.2b of debt that needs consistent cash generation to stay comfortable.
The Vantage deal is the announcement that matters most here. Howard Hughes Holdings is not just buying an insurance company. It is trying to create a second operating pillar that can use fee based float and third party capital alongside the existing property portfolio, which already spans operating assets, MPCs and strategic developments.
For you, the key question is whether management can run an insurance balance sheet responsibly while still tending to the undeveloped land bank and rental properties that underpin current revenue of about US$2.37b. Execution on this pivot affects future capital allocation, the reliability of earnings and how much flexibility the firm has if operating cash flow remains tight against its debt load.
Howard Hughes Holdings' current analyst storyline points to US$3.6b in revenue and US$369.4m in earnings by 2029. That setup is based on a 15.3% yearly revenue growth rate and an earnings increase of about US$77m from US$292.1m today.
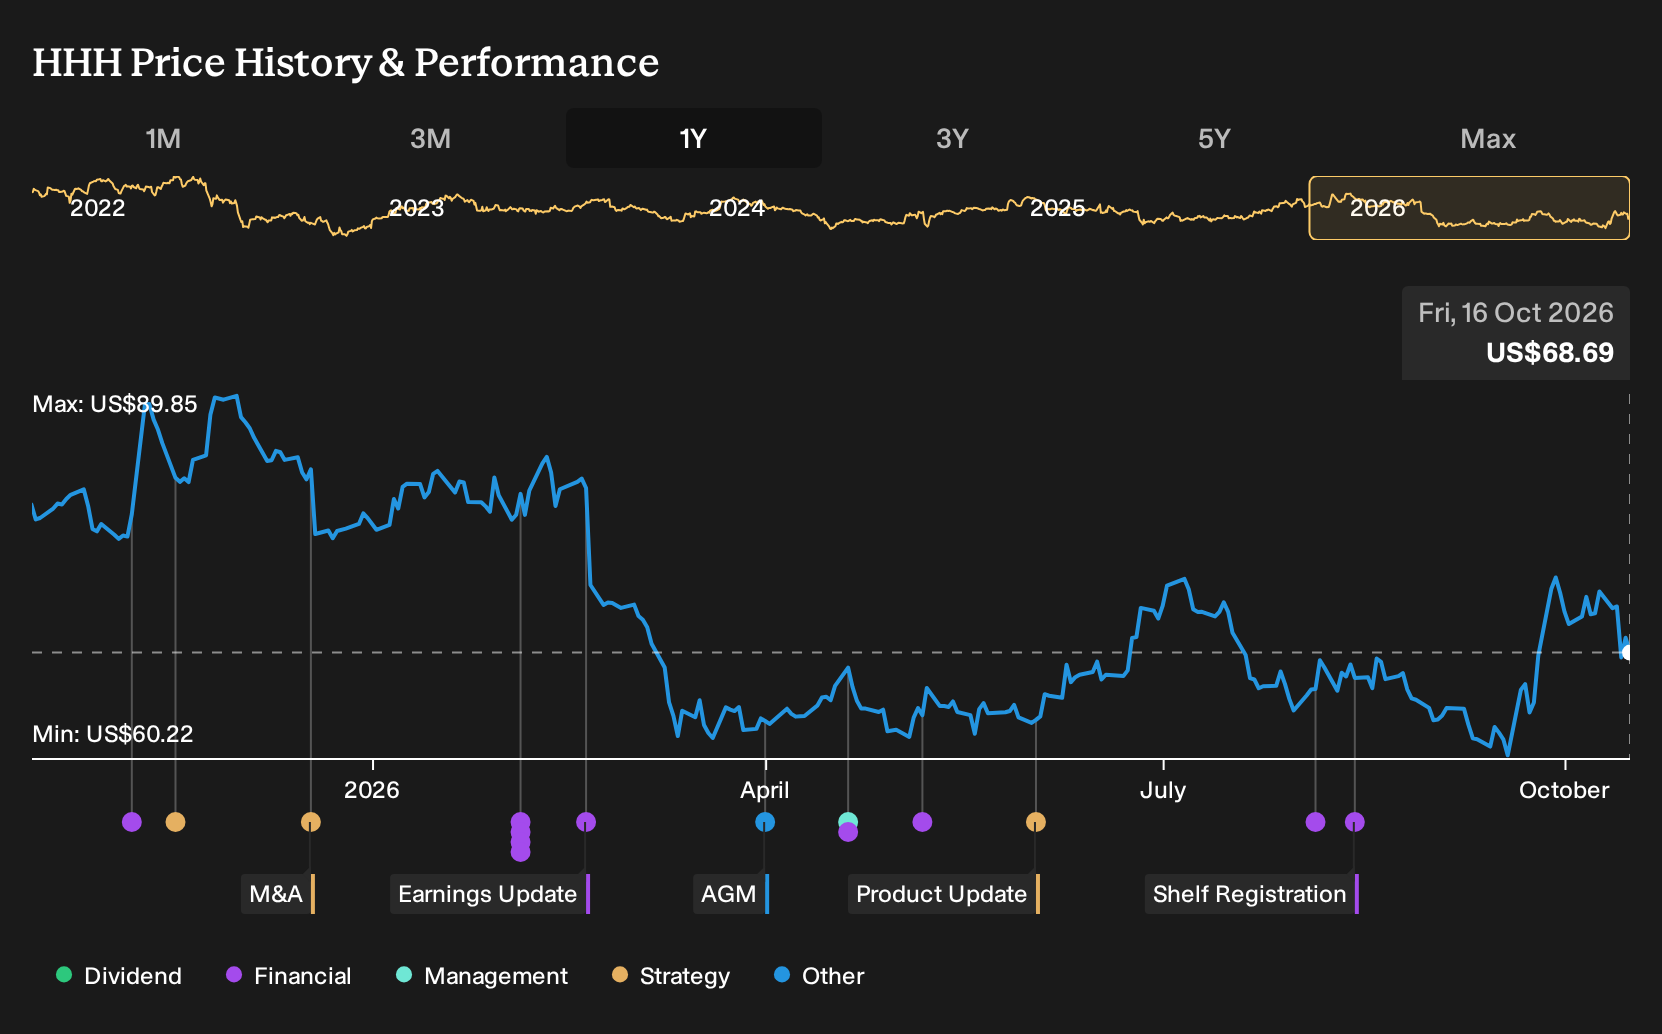
Uncover why Howard Hughes Holdings' fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community span from US$84 to about US$140, so some retail analysts see Howard Hughes Holdings as tightly priced while others pencil in far higher potential. You also need to weigh that spread against execution risk around the Vantage build out, which could reshape how this business performs over time.
Explore 5 other Howard Hughes Holdings fair value estimates, including one that suggests it could be worth just $84.00!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Howard Hughes Holdings research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Howard Hughes Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Howard Hughes Holdings' overall financial health at a glance.
Looking for more Howard Hughes Holdings style ideas?
If you like the blend of real assets and recurring income that Howard Hughes Holdings is aiming for, it can help to widen your watchlist with other businesses that share similar traits in different corners of the market.
- If you want potential mispricing with quality fundamentals as a filter, scan our hand picked 33 high quality undervalued stocks that already clear strict balance sheet and cash flow checks.
- For investors who care most about resilience and risk control, focus on businesses in our 32 resilient stocks with low risk scores that score well on financial stability and volatility screens.
- If your first priority is capital strength and clean accounts, start with the list of solid balance sheet and fundamentals (25 results) and build a shortlist from companies that already pass those core tests.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com