
How Earnings Expectations At KeyCorp (KEY) Have Changed Its Investment Story
- Kroenke Sports & Entertainment renewed its three year partnership with KeyBank, naming it exclusive Official Retail Bank Partner of the Colorado Avalanche and granting prominent arena branding plus a small business spotlight platform.
- The refreshed agreement links KeyCorp’s consumer banking, premium in arena hospitality and small business outreach. This creates a focused channel to deepen Colorado client relationships.
- We will look at how KeyCorp's investment narrative is influenced by this Avalanche partnership renewal and upcoming earnings expectations.
Scan how KeyCorp’s renewed Avalanche partnership compares with other regional banks that are focusing on visibility and customer growth by reviewing the hand picked 33 high quality undervalued stocks.
KeyCorp Investment Narrative Recap
To own KeyCorp, you need to be comfortable with a regional bank that leans heavily on interest income, fee businesses and disciplined capital return, while working through credit watchpoints. The short term story is still about whether repricing more than US$9b of low yielding fixed rate assets and managing deposit costs can lift net interest margin toward management’s targets.
The recent Avalanche partnership taps into brand reach and local client engagement, but it does not materially change that core earnings driver. The bigger swing factor remains asset quality, with nonperforming assets at 74 bp of loans in Q2 2026 and the risk this pockets of stress widen into a broader credit issue.
The Kroenke Sports & Entertainment renewal is the headline, yet the more financially relevant near term catalyst is the earnings report where analysts expect US$0.46 in EPS and US$2.03b of revenue, both above last year. A slightly higher consensus EPS estimate over the past month signals some optimism around how KeyCorp is running the balance sheet.
If repricing of roughly US$30b of assets through year end 2027 progresses as planned, investors will likely focus on whether reported net interest margin starts moving toward the 3.25% management has tied to that shift. Any disappointment on that front, or a further build in nonperforming loans in real estate or consumer exposures, would quickly overshadow branding wins from the Avalanche partnership.
KeyCorp is modeled to reach US$9.5b in revenue and US$2.5b in earnings by 2029, based on analyst estimates that include 8.9% yearly revenue growth and an earnings increase of about US$0.6b from US$1.9b today.
Uncover how KeyCorp's fair value indicates a 27% potential upside to its current price that may be short lived.
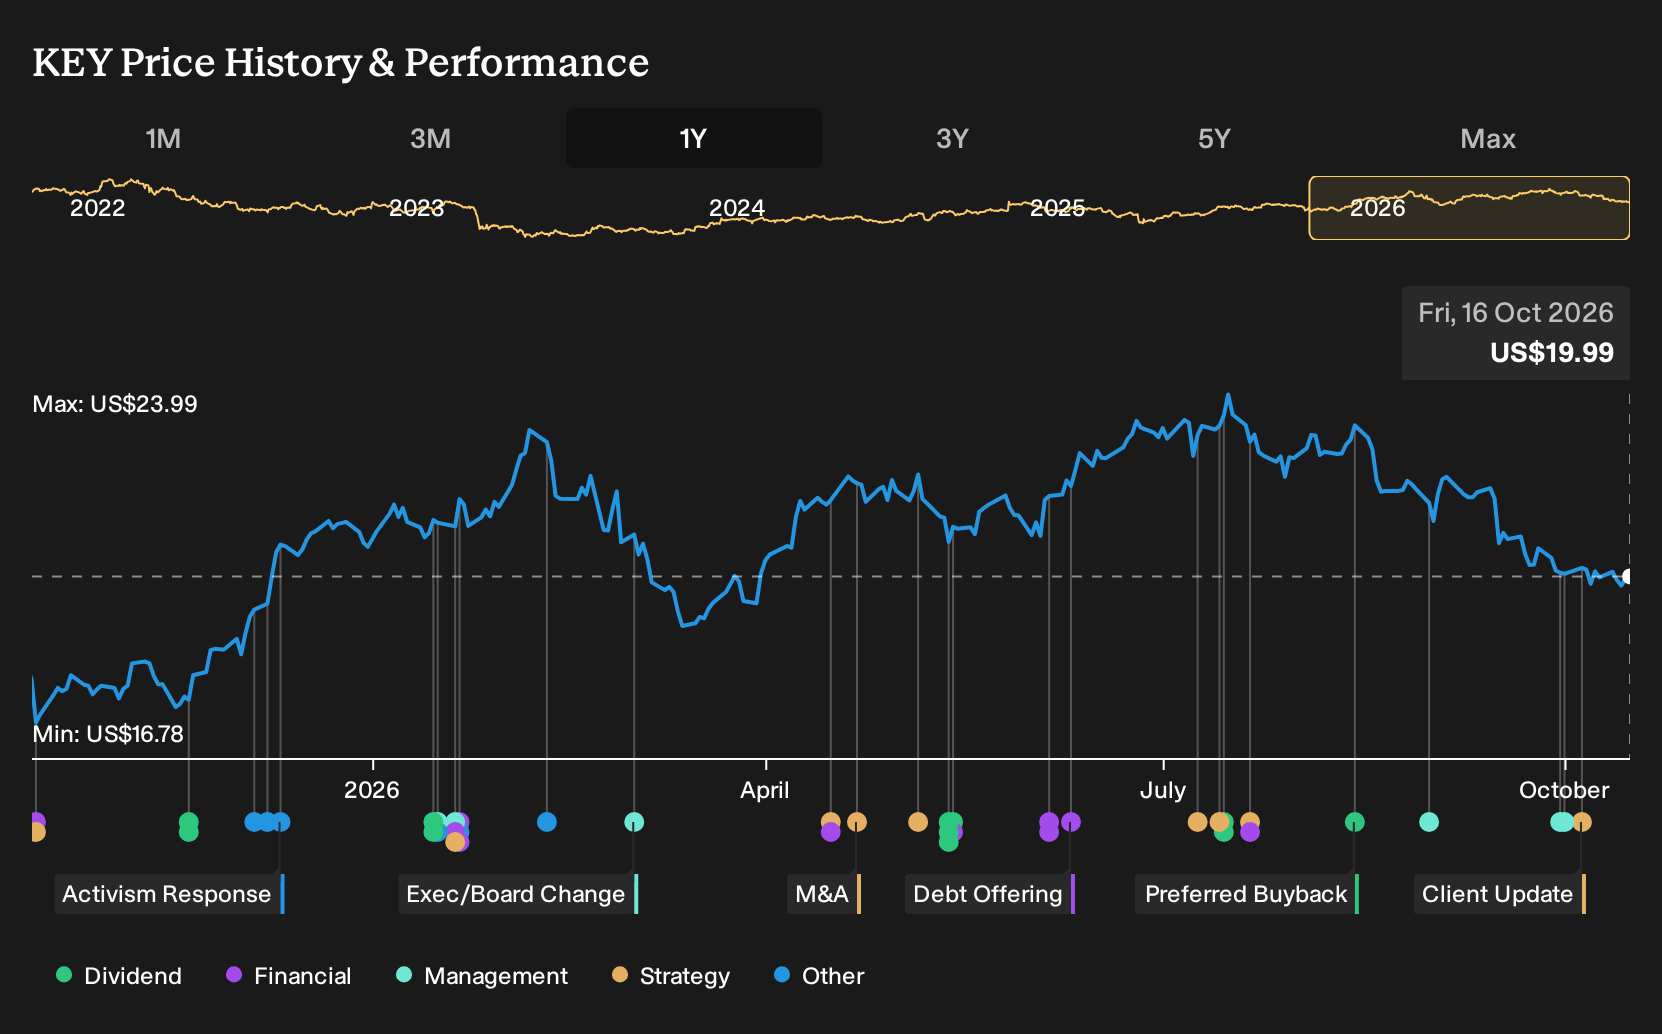
Exploring Other Perspectives
Some of the most optimistic analysts focus less on KeyCorp’s credit watchpoints and more on earnings potential if loan remixing and fee growth click. Before this Avalanche news, the bullish camp was already modeling about US$9.8b of revenue and US$2.7b of earnings by 2029. You can compare those stronger assumptions with your own view and decide which narrative feels closer to reality, knowing fresh information like this sponsorship renewal can shift opinions quickly.
Explore 2 other KeyCorp fair value estimates, including one that suggests as much as 97% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your KeyCorp research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for KeyCorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KeyCorp's overall financial health at a glance.
Looking for more KeyCorp investment ideas?
Once you have a view on KeyCorp, it can help to put that thinking alongside a wider watchlist of potential opportunities using the Simply Wall St Screener.
- If you care most about quality at a reasonable entry point, start with a curated group of resilient businesses trading below estimated value through the 33 high quality undervalued stocks.
- Income focused investors who want yield plus staying power can review a hand picked 8 dividend fortresses anchored by strong cash generation.
- If capital preservation and steadier profiles matter more to you than headline upside, spend time with a 32 resilient stocks with low risk scores that screens for sturdier balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com