
Does SmartLife Expansion Change The Bull Case For Calix (CALX)?
- Calix announced that its SmartLife applications, spanning SmartHome, SmartBiz, SmartMDU and SmartTown, are now available on prplOS-based devices within open, prpl-compliant management environments.
- This move extends SmartLife across multi-vendor gateways and links it to the AI-native Calix One platform, which can help service providers scale differentiated subscriber experiences with greater operational flexibility.
- Next is a look at how Calix's investment narrative could be shaped by SmartLife's wider reach across prplOS-compatible hardware platforms.
Calix Investment Narrative Recap
To own Calix, you need to believe its shift toward cloud software and subscriber experiences like SmartLife can keep deepening relationships with broadband providers while memory cost inflation and zero margin surcharge revenue are managed carefully. The SmartLife prplOS move supports that belief operationally, but does not change the near term focus on improving gross margin quality.
The key short term swing factor remains how quickly higher margin software and services scale relative to pressured appliance economics and any fallout from shareholder investigations. The expanded SmartLife reach could help utilization of the Calix One platform over time. However, governance and component cost risks still sit at the front of the story.
The most directly relevant side development is the US$100m increase in Calix's share repurchase authorization to US$625m on 8 October 2026. That decision sits alongside SmartLife on prplOS as a signal that management is leaning into both platform reach and capital returns while the business works through component cost and margin constraints.
For you as a shareholder, the enlarged buyback amplifies the importance of execution on the AI native Calix One and SmartLife franchises. If software and services revenue mix keeps improving and SmartLife adoption on prplOS devices helps support contract wins, repurchases could matter more for per share outcomes, while any margin setbacks or governance issues would cut the other way.
What The SmartLife Expansion Means For Calix's Analyst Case
Calix's SmartLife push onto prplOS devices lands on top of an analyst framework that already assumes meaningful scaling in both revenue and earnings. Those projections matter because they underpin how much weight you might give to cloud and subscriber experience growth, compared with the very real headwinds from memory costs and governance questions.
Analysts are currently building in revenue growth of 15.2% per year over the next three years. That pace reflects expectations around broader adoption of platforms like Calix One and SmartLife, including use across MDUs, utilities and larger global customers, while still allowing for pressure from low margin surcharge revenue.
Earnings sit at US$51.2 million today on the analyst numbers, with consensus looking for US$185.1 million by 2029. That is an earnings increase of about US$134 million. This implies analysts are anchoring on both higher profit margins and a richer mix of software and services tied to offerings such as SmartLife, even as appliance margin pressure and investigations remain in focus.
The profit margin assumptions make that shift explicit. Forecasts move from a 4.6% margin today to 10.9% in three years. This places a lot of weight on improved gross margin quality and cost discipline as SmartLife, SmartHome and related services scale across more prplOS compatible hardware and more Calix One workflows.
Calix's narrative projects US$1.7b revenue and US$185.1 million earnings by 2029. This requires 15.2% yearly revenue growth and an earnings increase of about US$134 million from US$51.2 million today.
On top of that, analysts expect the share count to decline by about 5% per year over the next three years. For you as an investor, that assumption amplifies the importance of how effectively Calix converts SmartLife and Calix One demand into actual cash generation, because fewer shares only help if aggregate earnings and free cash hold up against higher component costs.
The valuation overlay ties these operating expectations into a single snapshot. Analyst targets center on a consensus price of US$62.33, with a range from US$52.00 to US$85.00. These are built on 2029 forecasts that include US$1.7b in revenue, US$185.1 million in earnings and a P/E of 23.4x on those 2029 earnings, discounted back using roughly an 8.8% rate.
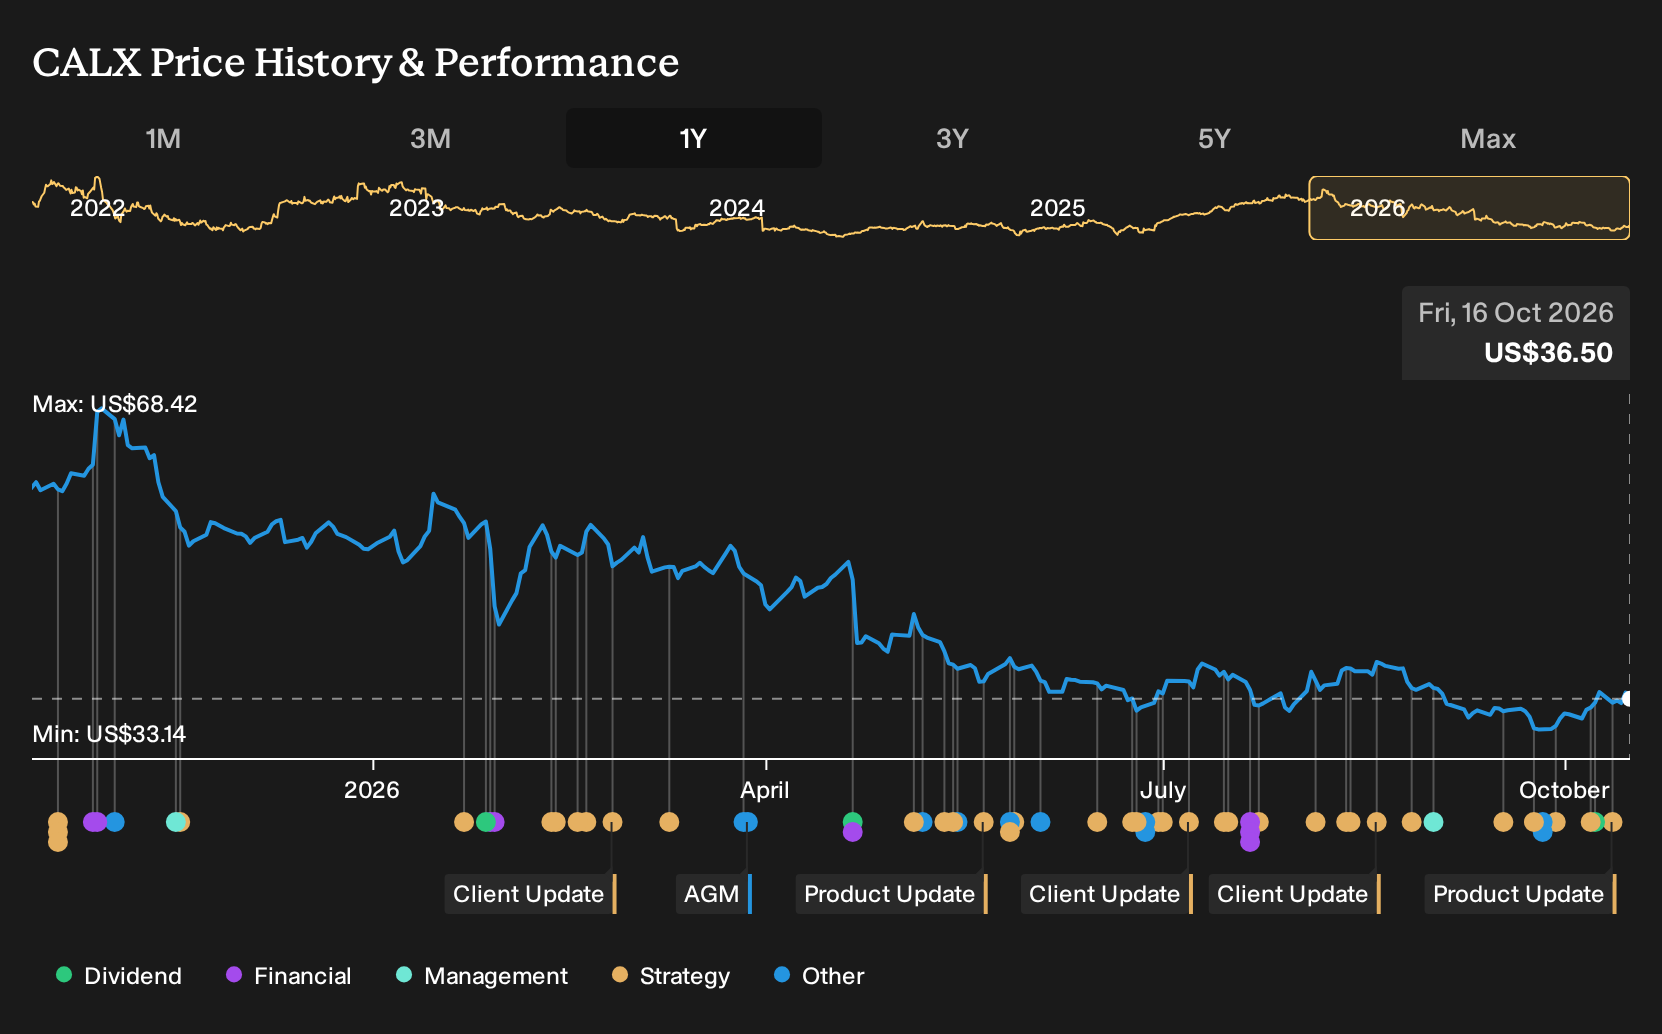
Compared with the current Calix share price of US$34.34, that consensus target sits 44.9% higher. This highlights how much of the upside case depends on the firm meeting its SmartLife and Calix One scaling goals. The projected P/E of 23.4x on 2029 earnings also sits below the 35.3x multiple quoted for the broader US communications group in the analyst report. That reflects an expectation that the current 42.2x multiple compresses as earnings grow.
Those numbers only come together if recurring software and services tied to SmartLife, SmartBiz, SmartMDU and SmartTown keep gaining traction, while low margin surcharge revenue and memory costs are kept in check. They also assume governance issues from the recent shareholder investigations do not widen in a way that depresses profitability or valuation multiples more than analysts are currently building into their models.
Uncover why Calix's fair value points to a 71% potential upside to its current price that could narrow quickly if Calix executes on its plan.
Exploring Other Perspectives
One alternate view focuses on execution risk rather than memory costs. The most bearish analysts worry that Calix could struggle to turn its AI toolkit into consistent upsells, even though they were still modeling about US$1.6b revenue and US$165.7 million earnings by 2029. Those forecasts were set before the SmartLife prplOS news. As a result, opinions may shift, so it can be useful to explore several viewpoints before deciding what you believe.
Explore 4 other Calix fair value estimates, including one that suggests it could be worth just $59.31!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Calix research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Calix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Calix's overall financial health at a glance.
Looking For More Investment Ideas Beyond Calix?
If the Calix story has sharpened your thinking about broadband, AI and recurring software, it can be useful to compare it with other opportunities that line up better with your own risk and income preferences.
- For investors who care most about valuation support and quality fundamentals, it can be helpful to start with companies screened for both, using the 33 high quality undervalued stocks as a filter for your next watchlist candidate.
- If capital preservation sits higher on your priority list, you might prefer businesses that score well on financial resilience and risk metrics, which you can zero in on using the 32 resilient stocks with low risk scores to narrow the field quickly.
- Those hunting for less crowded opportunities can focus on smaller, under-researched stocks with solid metrics by scanning the 20 high quality undiscovered gems and seeing which stories you find most compelling.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com