
SoftwareOne Holding (SWX:SWON) Following OpenAI Partner Win And The Case For An Undervalued Stock
SoftwareOne Holding (SWX:SWON) has been named an OpenAI Select Partner, giving the Swiss software specialist a formal role in delivering GPT-6 Astra and ChatGPT Work solutions to enterprise customers worldwide.
Recent trading reflects that this OpenAI news is landing in a stock that already has some momentum behind it, with SoftwareOne Holding’s share price at CHF9.48 after a 90-day share price return of 15.33% and a 1-year total shareholder return of 19.38%, even though investors who bought three to five years ago are still sitting on sizeable total return declines over those longer periods.
Scan beyond SoftwareOne Holding and see which other AI-focused stocks screen strongly for quality and momentum in our curated list of 38 profitable AI stocks that aren't just burning cash.
SoftwareOne Holding now has a fresh AI partnership story and a stock that has already moved. The real question is whether that combination is already fully reflected in the current valuation.
Most Popular Narrative: 16% Undervalued
SoftwareOne Holding is framed as undervalued in the most widely followed narrative, with a fair value of CHF11.27 against the last close at CHF9.48. This places the new OpenAI Select Partner badge alongside an existing view that the shares trade below estimated worth.
Growth in global digital transformation and the rising complexity of software licensing and compliance continue to drive enterprise demand for third-party expertise in advisory, cloud migration, and managed services. SoftwareOne's investment in AI, cybersecurity, and cloud offerings positions it well to capture incremental revenue and profitability as businesses increase IT and software spend.
See why 6 investors see SoftwareOne Holding as 16% undervalued.
Result: Fair Value of CHF11.27 (UNDERVALUED)
Still, the bullish SoftwareOne Holding story can break if heavy reliance on Microsoft cuts into licensing income or if the Crayon integration delivers weaker cost savings than expected.
Find out about the key risks to this SoftwareOne Holding narrative.
Another View: What Multiples Say About SoftwareOne Holding
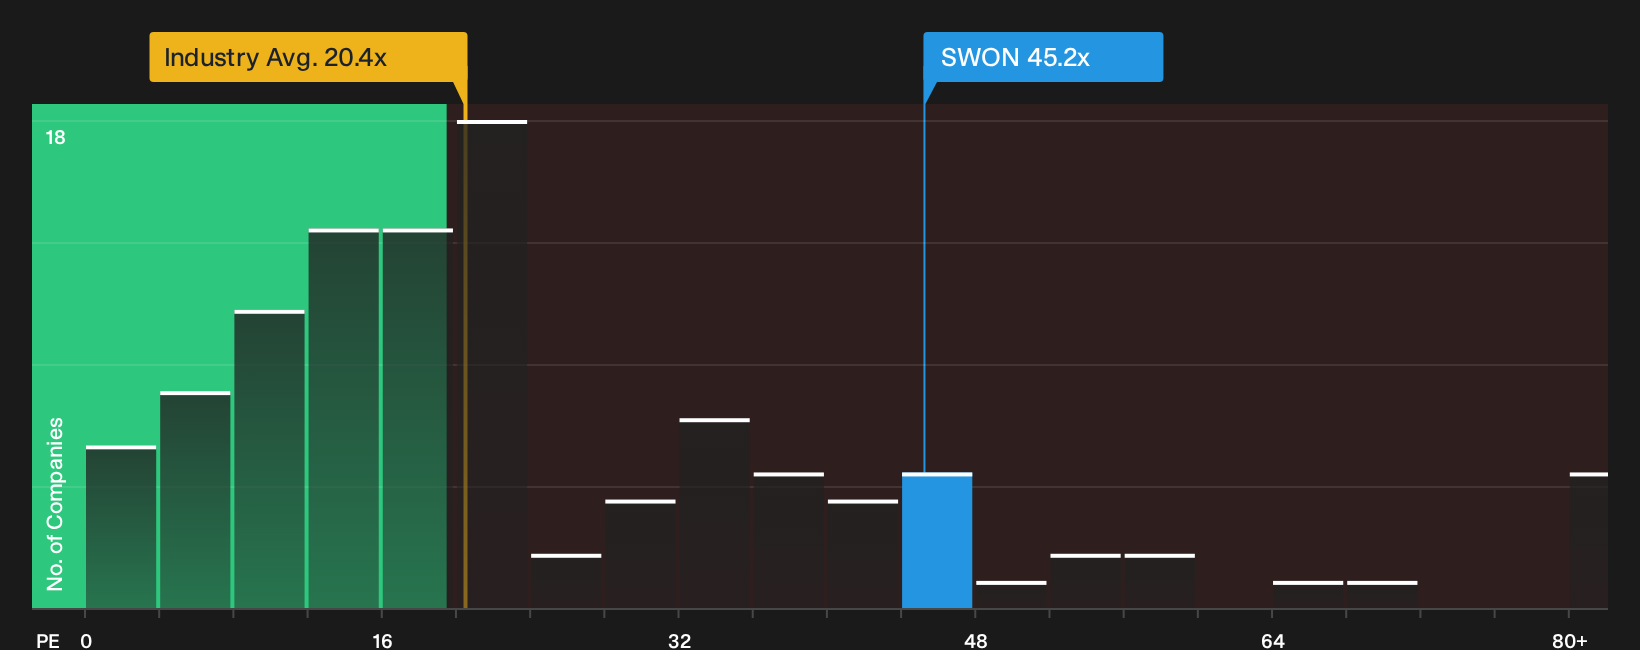
That fair value of CHF11.27 paints SoftwareOne Holding as undervalued, yet the current P/E of 45.2x is more demanding than the European Electronic industry at 20.2x and still above the 49.5x fair ratio the market could drift toward. Is the premium simply paying up early for the OpenAI and Crayon story?
Our valuation work based on this pricing yardstick breaks down the gap versus peers and that fair ratio in more detail. This can help you judge whether today’s level feels like overpayment or a risk you are comfortable underwriting, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the optimism around SoftwareOne Holding outweighs the concerns? Act quickly, review the numbers, and form your own view with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SoftwareOne Holding?
Do not stop at one opportunity. Broaden your watchlist with a few focused sets of ideas that match different priorities, from value to resilience.
- Target bargain hunters by scanning the 191 high quality undervalued stocks that combine quality fundamentals with prices that sit below many investors’ radars.
- Prioritise stability and let the 234 resilient stocks with low risk scores guide you toward businesses with more durable balance sheets and lower overall risk scores.
- Hunt for tomorrow’s potential leaders through the 617 high quality undiscovered gems, so you are not only reacting once everyone else has already moved.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com