
ConocoPhillips (COP) Stock Looks About Right On Tight Oil Market News
ConocoPhillips has delivered a strong share price run in recent years, which puts a spotlight on whether its current US$146.51 price is still in line with what its earnings can support. With the energy sector back in focus and this stock firmly in the mix, the key issue is how much of its profit story may already be reflected in the valuation.
- Over the past 5 years ConocoPhillips has returned 131.0%. This raises the question of how much further upside its earnings power can reasonably justify from here.
- Recent commentary pointing to tight fuel markets and a focus on upstream projects, including potential North Sea assets and production expansion, can influence expectations for future profitability and the durability of cash generation that underpins any earnings based valuation.
- There is a second opinion on ConocoPhillips worth weighing. See what analysts think ConocoPhillips's shares could be worth.
The stock's next move may depend on whether its current P/E multiple and overall price look supported by the earnings that ConocoPhillips is generating today.
If you want to balance ConocoPhillips' earnings story with other oil and gas producers, a focused stock screen is a useful next step. You can start with 17 top copper producer stocks.
Is ConocoPhillips Fairly Priced on Earnings?
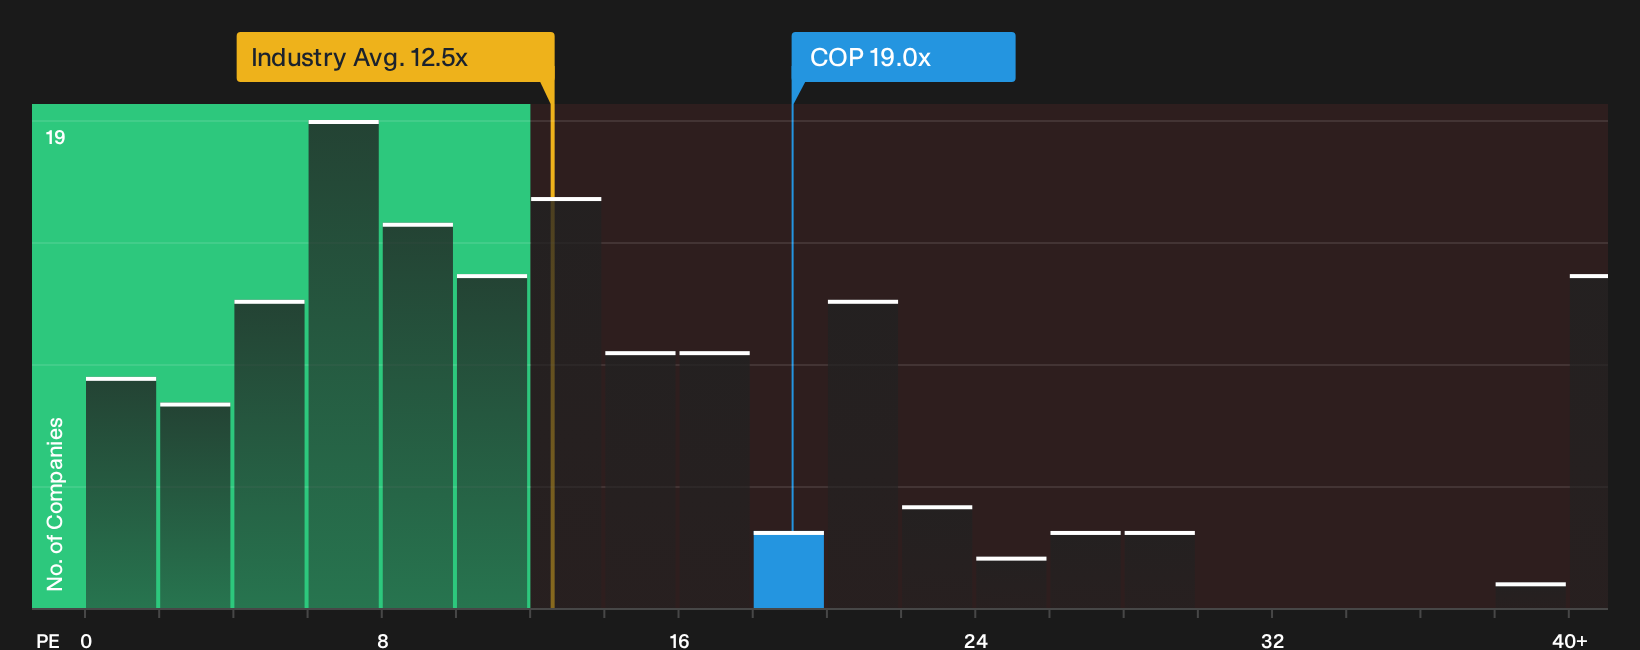
The P/E ratio is a useful lens for ConocoPhillips because earnings are a core driver of how investors weigh oil and gas producers. At roughly 19.0x, the stock trades close to both its own peer group near 19.6x and the tailored fair multiple implied by its fundamentals. That places ConocoPhillips on a richer earnings tag than the broader Oil and Gas sector average of about 12.5x, which is a wide gap for a mature producer and worth weighing against your expectations for future profitability and commodity pricing.
Because recent analyst enthusiasm and price target hikes have pulled sentiment higher, the current P/E suggests investors already assign ConocoPhillips a quality premium relative to the sector, rather than a clear bargain. The key question for you is whether the company’s free cash flow profile, project pipeline and balance sheet justify paying around peer level for each dollar of earnings, given that more cyclical producers in the industry trade on materially lower multiples. Explore the numbers behind ConocoPhillips's P/E valuation.
The ConocoPhillips Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off by spelling out which future paths for ConocoPhillips' growth, margins and earnings would need to occur for the current share price to look materially higher or lower. Each one ties a specific fair value to a defined mix of potential catalysts and risks, so you can track over time which version of ConocoPhillips' story is coming through in the numbers on Simply Wall St's Community page.
ConocoPhillips attracts two very different readings, with one camp seeing more embedded potential while another focuses on execution risk and downside.
Bull case: roughly fairly valued
"Global LNG market tightness, combined with ConocoPhillips securing 12 MTPA of LNG offtake and expecting first LNG from projects such as Port Arthur from 2027, points to a growing contribution from LNG marketing that could support higher revenue and cash flow than currently reflected in the stock…”
Discover why this Narrative puts ConocoPhillips at roughly fairly valued.
Bear case: 16% overvalued
"The plan to drive a $7b free cash flow inflection by 2029, including around $1b of incremental free cash flow per year from 2026 to 2028 and a further $4b from Willow, concentrates expectations on a narrow set of large projects…”
Explore why this Narrative puts ConocoPhillips at 16% overvalued.
Before you act on ConocoPhillips' valuation, there is one more piece to check
Market pricing only tells you what investors think today. The next layer is how professional forecasters see ConocoPhillips a few years from now, and how that lines up with the current multiple. Explore where analysts expect ConocoPhillips to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com