
Independent Bank (INDB) Could Be 15% Undervalued After Q3 Earnings Beat
Independent Bank (INDB) just delivered third quarter results that topped revenue and profit expectations, with loan and deposit growth supporting stable net interest margins despite tougher competition and a more challenging credit backdrop.
The third quarter beat has come alongside a share price that jumped 3.6% on the day to US$79.88 and has gained 3.7% over the past week, even though the 3 month share price return is down 5.8% and the 1 month return is down 2.9%. Over a longer horizon, total shareholder return of 24.5% over 1 year and 95.2% over 3 years points to momentum that has been building over time as investors weigh Independent Bank’s record earnings, lower net charge offs and ongoing shift toward relationship lending against a tougher credit backdrop.
Scan how Independent Bank’s Q3 story compares with other regionals that screen well for balance sheet strength and disciplined lending using our hand picked list of solid balance sheet and fundamentals (25 results)
Independent Bank now trades below both intrinsic value estimates and the average analyst target, even after this week’s jump. Is the discount reflecting real credit concerns, or is an overly cautious market setting up a valuation gap?
Most Popular Narrative: 14.5% Undervalued
Independent Bank’s most followed valuation story pegs fair value at $93.43 using a 7.24% discount rate, compared with the latest close at $79.88. This puts the focus squarely on whether the market is fully recognising its balance between credit risk and capital return.
The main factor that has to go right is that Independent Bank maintains credit discipline while working through remaining office exposures and elevated criticized commercial loans, even as it absorbs higher near-term expenses from the core conversion and softer CRE demand.
Any renewals, sales or additional downgrades that are less favorable than expected could lift credit costs and reduce earnings.
See why 5 investors see Independent Bank as 15% undervalued.
Result: Fair Value of $93.43 (UNDERVALUED)
Still, the CRE book and core conversion plan both carry execution risk that could lift credit costs or keep efficiency stuck at a higher level if outcomes skew unfavorably.
Find out about the key risks to this Independent Bank narrative.
Another View: Independent Bank Through The P/E Lens
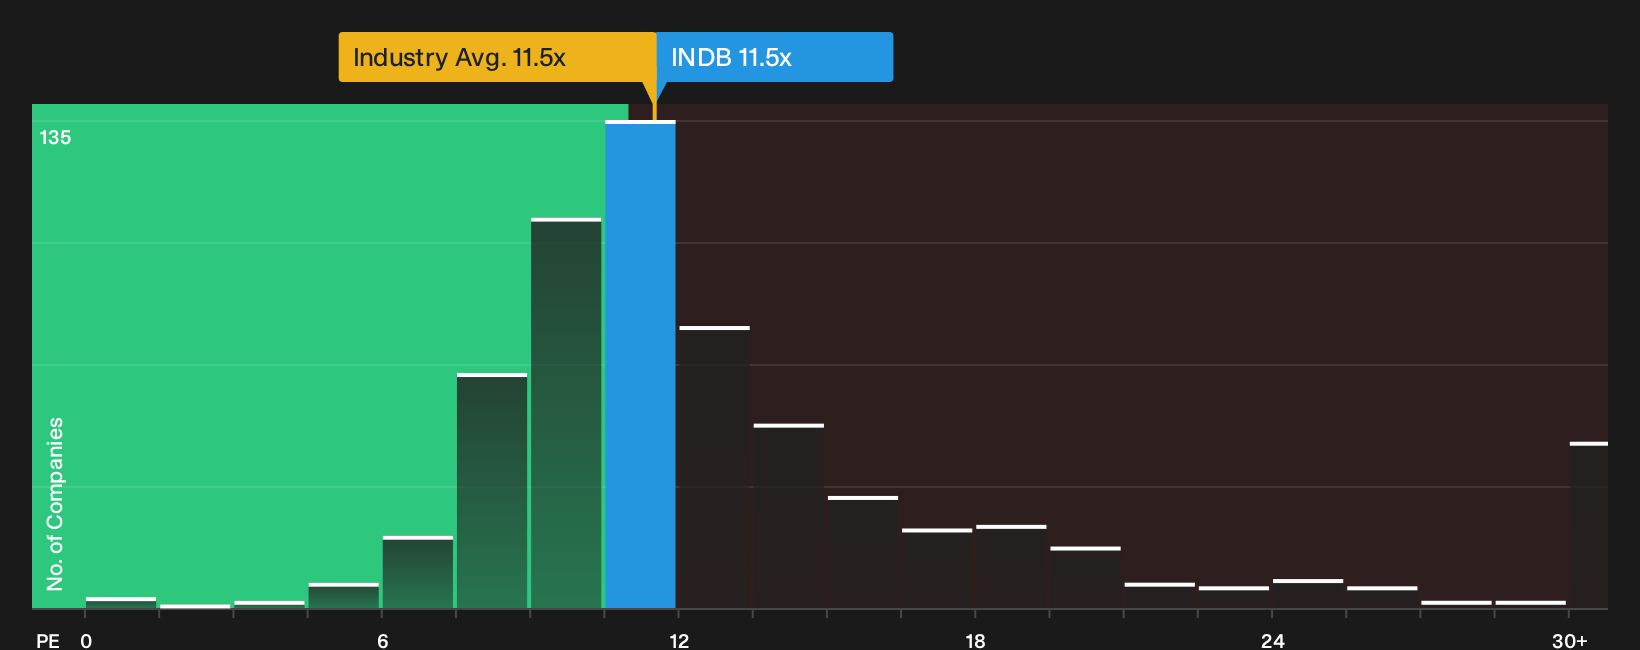
Independent Bank might look cheap on fair value models, yet its 11.5x P/E sits almost exactly in line with the broader US Banks industry at 11.5x and only slightly below the peer average of 12.3x. The fair ratio of 12.1x points to only modest upside before the valuation story changes, which raises the question of how much margin of safety is really here for new money.
For a closer look at how this earnings multiple stacks up against fundamentals, and what that gap could mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
For further context on how Independent Bank trades against sector peers on key valuation metrics, review
Next Steps
Mixed signals around Independent Bank’s valuation and risk profile can feel messy, so consider the details while they are fresh and weigh both sides for yourself with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Independent Bank?
Do not stop your research with Independent Bank. Broaden your watchlist and pressure test your thesis by lining it up against other high quality opportunities from the Simply Wall St screener.
- Target stocks that combine quality and value by running your filters against the 33 high quality undervalued stocks.
- Strengthen your income stream by focusing on payout resilience and yield with the 8 dividend fortresses.
- Dial down portfolio risk by concentrating on financially robust businesses via the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com